



PW Consulting: Linear Sorter Market Valued at USD 3,240.5 Million in 2025, Poised to Reach USD 5,289.27 Million by 2032 at a 7.25% CAGR

Linear Sorter Market 2026: Strategic Imperatives for Supply Chain Leaders — PW Consulting Insight Preview
Executive summary
As companies recalibrate logistics strategies for a post-pandemic, e-commerce-first world, linear sorters have moved from niche automation tools to foundational infrastructure in modern distribution networks. PW Consulting’s forthcoming Linear Sorter Market report — base year 2025, forecast 2026–2032 — quantifies these shifts and translates them into actionable guidance for executives preparing capital plans, procurement roadmaps, and operational transformations in 2026.
Linear Sorter Market
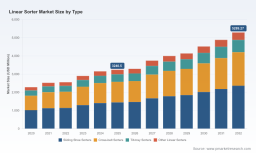
At the aggregate level, the market demonstrates a steady, durable expansion: the global linear sorter market climbed from an estimated USD 2.28 billion in 2020 to roughly USD 3.24 billion in 2025, and our forward view shows continued momentum through 2032 underpinned by a compound annual growth rate (CAGR) of approximately 7.25% over the 2026–2032 forecast window. By 2032 the market is projected to be materially larger than today, reflecting sustained investment by parcel carriers, third-party logistics providers, and large-scale retailers.
Linear Sorter Market
Why this matters for 2026 decision-makers
-
CapEx timing and scale: The combination of steady CAGR and near-term market expansion signals a continued buyer’s market for modular, upgradeable systems—but shrinking vendor lead times and rising demand for turnkey solutions mean procurement cycles must be compressed. Organizations that move from exploratory pilots to firm procurement windows in 2026 will capture technology, pricing, and delivery advantages.
Linear Sorter Market -
Operational resilience: Linear sorters are a direct lever to reduce headcount variability and address recruiting friction in peak seasons. Our analysis situates sorters as more than throughput devices: they are nodes where data, controls, and physical flow converge, enabling new operating models such as distributed cross-docking and micro-fulfillment.
-
Strategic optionality: Investment in modular linear sortation architectures preserves optionality for future SKU proliferation and parcel-size heterogeneity — a key consideration as e-commerce continues to drive parcel mix complexity.
Market dynamics: growth drivers and risk vectors
-
Demand-side drivers — E-commerce and parcelization: Continued growth in e-commerce and changing consumer expectations for same-day and next-day delivery remain the primary growth engine. Sorting systems that can reliably handle mixed parcel dimensions and high SKU variability command strategic value.
-
Supply-side constraints — materials and lead times: Linear sorters are steel-intensive systems. The underlying integrated-steel production chain consumes substantial iron ore, metallurgical coal, limestone, and recycled steel per ton of crude steel produced — a reality that links sorter lead times, capex inflation, and sustainability goals to global steel market dynamics.
-
Regulatory and labor dynamics: Recent craft determinations in major postal operators (e.g., assignments tied to next-generation induction sorters) demonstrate that automation rollouts can intersect with labor agreements and regulatory rulings. Strategic planners must model installation timelines, labor negotiations, and potential work-rule impacts when scoping projects.
-
Technology trajectories: Advances in modular shoe, cross-belt, and narrow-belt designs — along with smarter controls and tighter WMS/WCS integration — are improving throughput without linear increases in footprint or energy use. The technology frontier is now about systems-of-systems integration rather than single-component performance.
Competitive landscape — what procurement teams should know
The market is moderately concentrated: the top three global players account for a meaningful share of revenue, and the top five consolidate over half the market — a structure that shapes vendor selection, procurement leverage, and aftermarket service economics.
-
Global systems integrators and established OEMs: Firms with deep portfolios (e.g., high-throughput shoe sorters and end-to-end sortation ecosystems) remain prime partners for large-scale distribution centers and postal systems. These vendors differentiate on throughput guarantees, integration services, and long-tail spare-part availability.
-
Regional specialists and Chinese OEMs: Vendors offering compact, vertically circulating or narrow-belt solutions are increasingly competitive for space-constrained sites and mixed-parcel environments. Their strengths include aggressive lead times, compact layouts, and attractive CAPEX profiles for mid-market operators.
-
Technology-focused entrants: Companies emphasizing control software, modularity, and service analytics are changing aftermarket economics. Expect acquisition activity as software-first firms seek to bolt in physical sortation capabilities to offer full-stack solutions.
Recent industry signals underscore these trends. Leading vendors exhibited new product lines and received notable contracts at trade shows and procurement events over the last 18 months, highlighting investments in small-parcel throughput, compact system layouts, and induction technologies. These moves are consistent with our view that buyer demand is bifurcating: high-throughput, large-footprint sorters for mega-hubs and compact, high-density systems for urban and micro-fulfillment nodes.
Practical takeaways from the report (what’s in the toolkit)
PW Consulting’s report is structured as a practical playbook for executives, procurement leads, and operations heads. Key, actionable deliverables include:
-
Decision matrices for topology selection — guidance on when to prioritize sliding-shoe versus cross-belt or narrow-belt solutions based on throughput profiles, parcel mix, facility footprint, and TCO timelines.
-
Procurement templates and negotiation levers — model RFP elements, warranty/service clauses, spare-parts provisioning strategies, and benchmarking metrics to align supplier commitments with desired uptime and throughput.
-
Deployment and integration playbooks — stepwise timelines for civil works, electrical provisioning, WMS/WCS integration, safety certification, and phased commissioning to minimize disruption in live DCs.
-
Risk registers and mitigation guidance — scenarios tying raw-material shocks, labor rulings, and customs/regulatory actions to schedule and cost overruns, with mitigation playbooks and contingency buffers calibrated for different-sized programs.
-
Financial templates — capital budgeting models that account for depreciation, energy cost sensitivities, modularity premiums, and payback horizons under multiple parcel-growth scenarios.
How to turn market insight into a 2026 plan
-
Bring the procurement window forward: With market demand growing and supplier concentration favoring established integrators, organizations should finalize techno-commercial evaluations and move toward RFQ issuance in early-to-mid 2026 to avoid elongated lead times and fiscal-year procurement rushes.
-
Prioritize modularity and retrofitability: Select architectures that allow incremental capacity adds and provider-agnostic swaps — this preserves flexibility as parcel profiles continue to evolve.
-
Embed service & analytics in contracts: Given the importance of uptime and the cost of operational disruptions, tie payments and SLA credits to measurable performance metrics and invest in analytics-enabled service agreements.
-
Model labor and regulatory scenarios: Include conservative buffers for potential labor negotiations and craft rulings that could affect commissioning personnel or operating protocols, especially for mail and national postal deployments.
Where our analysis dives deeper (and what we intentionally withhold here)
The full PW Consulting report includes granular market build-ups by type, application, and region; vendor scorecards; deployment case studies; and interactive financial models. In keeping with our “trailer” approach, this preview purposefully omits the full, line-item segmentation tables and detailed regional/application revenue splits — these are reserved for verified report purchasers. Prospective buyers will find the detailed segment-level data essential for site-specific business cases and for supplier-selection shortlists.
Closing: the strategic inflection for 2026
Linear sorters sit at an operational inflection point: they are no longer “nice-to-have” automation components but strategic assets that shape network design, labor models, and service commitments. The aggregate market expansion and the predictable CAGR through 2032 create a clear runway for companies to commit to modernization — provided those commitments are structured with modularity, service integration, and regulatory/commodity-risk mitigation in mind.
PW Consulting’s Linear Sorter Market report is designed to be the decision-support backbone for those commitments: it translates macro trajectory into procurement timing, vendor differentiation, and deployment risk controls. For 2026, our recommendation is simple — plan with precision, procure with optionality, and partner with vendors who can guarantee operational outcomes, not just hardware delivery.
Next steps
-
Download the full report for the complete segmentation tables, vendor scorecards, and bespoke financial models required to finalize 2026 capex decisions.
-
Engage PW Consulting for a tailored executive briefing and a one-day procurement workshop that aligns your network strategy with supplier capabilities and 2026 delivery calendars.
For detailed analysis of this topic, please visit the official page: Linear Sorter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


