



PW Consulting Predicts Renewable Energy Consultancy Market to Expand Rapidly at a 10.41% CAGR Through 2032

Renewable Energy Consultancy Services 2026: Strategic Intelligence for Decision-Makers
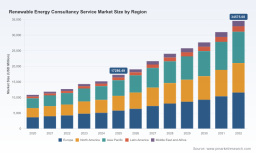
PW Consulting’s latest market research—Renewable Energy Consultancy Services: Market Research 2026—offers a pragmatic, forward-looking playbook for executives, investors, and public-sector planners who must make high-consequence decisions in the year ahead. Built on a base year of 2025 with a 2026–2032 forecast horizon, the study combines rigorous market-sizing, scenario-driven strategy guidance, and hands-on commercial tools. The headline: global demand for renewable energy consultancy services has accelerated materially, growing from roughly USD 10.8 billion in 2020 to about USD 17.3 billion in 2025, and is projected to approach USD 34.6 billion by 2032 (forecast CAGR 10.41% for the projection window). This creates both opportunity and complexity for market participants in 2026—our report is designed to convert that complexity into tactical advantage.
Renewable Energy Consultancy Service Market Research
Why this report matters for 2026 decisions
-
Timing of regulatory inflection points. With new compliance regimes and supply-chain constraints coming into force for projects starting construction in 2026, advisory teams need immediate, practicable guidance. The report maps regulatory levers, compliance pathways, and safe-harbor tactics that materially affect project eligibility for tax credits and financing.
Renewable Energy Consultancy Service Market Research -
Capital allocation under uncertainty. Investors, corporate strategists, and renewables platform owners must decide where to place capital across technologies (solar, wind, storage, hydrogen) and service lines (from due diligence to grid-integration advisory). Our scenario modules quantify upside and downside case outcomes and translate them into investment-stage decision checkpoints.
Renewable Energy Consultancy Service Market Research -
Operationalizing energy transition at scale. Hyperscaler-driven procurements, accelerating hybrid projects (solar-plus-storage, VPPs, and hybrid PPA structures) and large-scale green hydrogen pilots require integrated advisory models that combine technical, commercial, and regulatory expertise—exactly the cross-disciplinary playbooks embedded in the report.
-
M&A and capability buildouts. The market is consolidating selectively: platform acquisitions, targeted bolt-ons for technical capabilities, and strategic hires. Our deal playbook and acquisition prioritisation matrix are built to shorten diligence timelines and improve post-merger integration outcomes.
What’s inside—practical, operational content (executive summary)
-
Market sizing & forecast: a transparent methodology that reconciles historical vendor activity (2020–2025) with a seven-year forecast window (2026–2032), highlighting growth drivers and risk factors.
-
Scenario planning & stress tests: three discrete demand scenarios (policy-constrained, policy-accelerated, market-driven growth) with quantified implications for consultancy revenue pools, staffing needs, and capability investments.
-
Service-line playbooks: step-by-step frameworks for Project Development & Technical Advisory, Strategic & Policy Support, Environmental & Sustainability Consulting, and Grid Integration advisory—each with delivery templates, staffing models, and margin levers.
-
Commercial models & contracting templates: sample PPA structures, hybrid contracting approaches, and contractor/pass-through models for capex-heavy renewables projects.
-
Due diligence and underwriting toolkits: modular checklists for technical, commercial, and regulatory diligence; scenario-based cashflow sensitivity analyses; and an M&A valuation matrix tuned for renewable asset and services businesses.
-
Supply chain and compliance playbook: pragmatic guidance on safe-harbor strategies in light of FEOC-style restrictions and the 2025 U.S. policy shifts, designed to preserve access to tax credits and financing while mitigating supplier risks.
-
Talent & delivery economics: staffing blueprints and cost-driver analysis for specialised roles (grid-connection engineers, technical due diligence leads, regulatory compliance experts), and recommendations to manage labour cost inflation without sacrificing delivery quality.
-
Case studies & vendor scorecards: anonymised transaction case studies and vendor-performance benchmarks that help procurement teams select service providers against outcome-based KPIs.
Competitive landscape: what top consultancies are doing now
The consultancy field is both deepening and broadening. The three largest players collectively capture a modest share of the market—reflecting a fragmented competitive landscape where specialist engineering firms, boutique strategy houses, and large integrators coexist. Leading global firms have distinct positioning:
-
Strategy houses (e.g., McKinsey & Company, Boston Consulting Group, Bain & Company): focus on high-level decarbonisation roadmaps, portfolio optimisation, and scenario modelling. Their strengths are rapid strategic alignment and C-suite advisory, but projects requiring detailed engineering or on-the-ground permitting are typically delivered through alliances or local partners.
-
Technology and systems integrators (e.g., Accenture): combine digital platforms, AI/IoT applications, and full-stack implementation capability—critical for smart-grid, energy trading, and asset digitisation plays that hyperscalers and utilities demand.
-
Technical and assurance specialists (e.g., DNV, WSP, SLR, ERM): lead on technical due diligence, grid-connection engineering, permitting, and environmental execution. Their recent transactions and client engagements underscore the premium on engineering depth as projects scale in complexity.
-
Market intelligence and energy-focused consultancies (e.g., Wood Mackenzie, Guidehouse, Baringa Partners): provide high-fidelity market data, regulatory analysis, and operational forecasting—inputs that underpin investment underwriting and commercial structuring.
-
Big Four firms and advisory networks (e.g., PwC, EY): bring transaction advisory, tax optimisation, regulatory compliance and sustainability reporting at scale—services that are especially valuable amid shifting tax-credit rules and cross-border financing.
Recent strategic moves illustrate the field’s trajectory. Notable examples include DNV’s acquisition to establish a global centre of excellence for grid-connection engineering (February 2026), WSP’s completion of the TRC Companies acquisition to elevate Power & Energy capabilities (February 2026), and SLR’s integration of Powerhaus to strengthen renewables delivery (September 2025). These transactions, alongside targeted ecological and technical acquisitions elsewhere, reflect two concurrent trends: a race to consolidate complementary capabilities, and the continued value of specialised boutique expertise.
Key industry dynamics shaping 2026
-
Regulatory shockwaves and compliance complexity: FEOC-style foreign-entity rules coming into effect for projects starting construction in 2026, alongside policy changes enacted in 2025 that altered tax-credit landscapes, mean advisory teams must be fluent in jurisdictional nuance and creative in safe-harbor design.
-
Hyperscaler procurement and hybridisation: large cloud and data center operators have become outsized demand drivers, increasing appetite for bespoke PPAs, hybrid on-site/off-site models, and storage-enabled solutions.
-
Labour and delivery economics: specialised human capital—particularly for technical due diligence and grid-connection engineering—remains a primary cost driver. Firms will need flexible resourcing strategies, nearshore delivery hubs, and partnerships to control margins while meeting quality expectations.
-
M&A and platform play: policy uncertainty has delayed some capacity additions while accelerating consolidation in contracted assets and platform acquisitions; advisory demand is strong for transaction support, carve-outs, and operational integration.
Practical takeaways for 2026 leaders
-
Prioritise regulatory-readiness early. Projects and portfolios that do not clear 2026 compliance gates face materially higher financing risk. Use the report’s compliance matrix and safe-harbor templates to de-risk deal timelines.
-
Adopt modular advisory engagements. Split procurement into strategy, technical, and implementation tranches to preserve optionality and cap expertise costs—our delivery blueprints show where modularisation yields the highest near-term savings.
-
Embed market intelligence into capital allocation. Use scenario outputs to size upside exposure to green hydrogen and large-scale storage, and to calibrate acquisition premiums for platform assets.
-
Invest in capability bridges. For incumbents, targeted acquisitions or partnerships in grid engineering, environmental compliance, and energy-trading software will be decisive; the report’s acquisition prioritisation tool ranks capability gaps by expected ROI.
How this report should be used
Consider this publication a strategic operations manual and an intelligence digest combined. It is designed to be applied directly in board-level decision-making, investment-diligence processes, procurement RFPs, and program management offices. The appendices contain delivery templates, diligence checklists, commercial contract language examples, and a regulatory tracker tuned to the 2026 policy landscape.
To preserve competitive value and drive action, this press summary demonstrates the report’s analytics and frameworks but omits detailed regional and service-line revenue splits, granular market-share tables, and confidential client-case financials. The full report—available on PW Consulting’s research portal—contains the complete segmented datasets, interactive modelling files, and bespoke advisory supplements that teams need to execute with confidence in 2026.
Next steps
-
Download the full report to access complete segment-level forecasts, market-share analysis, and downloadable Excel models.
-
Schedule a PW Consulting briefing to translate the findings into a customised 90-day action plan—our advisory teams are set up to deliver rapid-deployment workshops for board and investment committees.
PW Consulting’s Renewable Energy Consultancy Services 2026 report is an operationally oriented intelligence product: engineered for leaders who must move decisively amidst regulatory headwinds, accelerated corporate demand, and evolving market structures. The growth runway is clear; the tactical choices you make in 2026 will define market position for the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Renewable Energy Consultancy Service Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


