



PW Consulting: Headphone Market to Hit USD 126,900 Million by 2032 at 10.5% CAGR

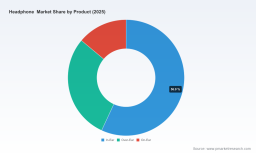
Headphone Market 2026: Strategic Imperatives for Market Leaders and Challengers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, decision-focused introduction to our full Headphone Market report. This overview synthesizes the macro dynamics that will shape corporate choices in 2026, explains why the dataset and analytical methods we used materially change risk/reward calculus, and outlines the must‑do strategic options executives should prioritize this year. Think of this as the trailer: it demonstrates the analytical depth and actionable framing you need to act — while the full, gated report contains the segmented models, scenario matrices and granular benchmarks required to execute with confidence.
Headphone Market
What the market looks like in one glance
After a sustained recovery and premiumization cycle during 2020–2025, the global headphone market stands at a new scale and trajectory. Using 2025 as our base year, the market had expanded markedly compared with the early pandemic period and — under our forecast framework — is projected to grow at a compound annual growth rate (CAGR) of approximately 10.5% through 2032. By 2026 the market is already materially larger than the 2020 baseline, and our long‑range model anticipates continued expansion into the early 2030s driven by a convergence of audio innovation, software ecosystems, and new form‑factor adoption.
Headphone Market
Two high‑level implications flow directly from this scale and growth profile. First, absolute opportunity is sizable enough that mid‑market players can profitably invest in premium niche plays without being squeezed out by incumbents. Second, the growth rate accelerates the value of first‑mover advantage for hardware platforms that can lock users into services, codecs, or device ecosystems.
Headphone Market
Why this research matters for 2026 corporate decision‑making
- Portfolio prioritization: The market’s scale and growth dynamics force tradeoffs between volume plays (price/feature) and margin plays (premium, services). Our report quantifies the elasticity drivers executives must model to choose which product lines to expand, pause, or sunset.
- M&A and partnership signaling: With a moderately concentrated supplier landscape (top‑three firms cumulatively controlling a meaningful share), acquirers need disciplined target screens. We provide screening criteria keyed to synergy capture thresholds and integration playbooks.
- Regulatory and supply‑chain risk management: Recent customs, export control, and air‑transport rules materially affect component sourcing and logistics. Our regulatory heatmap converts those developments into near‑term actions for procurement and compliance teams.
- Channel and monetization redesign: As device OEMs and platform owners monetize audio through subscriptions and spatial experiences, product teams must design hardware to enable services. The report includes an implementation checklist and go‑to‑market revenue scenarios.
Contents you will find in the full PW Consulting report
- Market size and forecast model (2020–2032) with transparent assumptions, sensitivity analysis and scenario variants.
- Go‑to‑market playbooks for premium, mid, and value segments — including SKU cadence templates, recommended feature sets, and suggested price architecture tied to margin simulations.
- Competitive landscaping and detailed profiles of incumbent and challenger players (product portfolios, R&D trajectories, channel mixes, and partnership maps).
- Supply chain and sourcing risk matrix, including battery & component concentration, tariff/regulatory exposure, and contingency sourcing strategies.
- M&A and partnership target shortlist methodology with valuation comparables, synergy break‑even analysis and integration checklists.
- Retail and e‑commerce benchmarks, return & warranty modeling, and aftermarket service economics.
- Primary research appendices: dealer interviews, carrier & OEM panels, consumer sentiment analytics, and proprietary usage surveys.
Note: Detailed segment tables (regional splits, product and application breakdowns, and micro‑price band volumes) are intentionally gated in the full report to preserve the commercial utility of the models and to ensure readers obtain the precise benchmarks needed for deal‑level decisions.
Competitive landscape — how to read incumbent moves
The competitive field includes global platform owners, legacy audio specialists, and diversified consumer electronics firms. Each plays a distinct role in shaping value chains and customer expectations:
- Platform OEMs (e.g., Apple): Focus on ecosystem integration and services monetization. Recent filings hint at expansion into over‑ear Bluetooth models, reinforcing platform owners’ strategy to maintain device stickiness through audio hardware.
- Japanese and European specialists (e.g., Sony, Sennheiser): Continue to push high‑fidelity and ANC innovation as differentiators; they are also active on licensing and professional channels to defend margin.
- Premium noise‑cancellation brands (e.g., Bose): Retain leadership in ANC user experience and are likely to double down on hybrid ANC tuning and long‑life battery claims.
- Mass and lifestyle brands (e.g., Beats under Apple, Samsung): Emphasize integration with consumer electronics ecosystems, fast product refreshes and co‑marketing with smartphone launches.
- Pro and niche players (e.g., Audio‑Technica, Shure): Target professional and enthusiast niches where studio fidelity and specialized fit matter — an area less vulnerable to low‑cost competition.
- Gaming and productivity incumbents (e.g., Logitech, Jabra): Are building low‑latency stacks and integrated communication features to capture non‑music use cases.
For executives, the lesson is clear: alignment with one or more ecosystem partners (OS/platform providers, gaming publishers, fitness platforms) is no longer optional if you plan to scale beyond a national market. Our report maps which partnership archetypes yield the strongest revenue uplift and the fastest path to profitability.
Regulatory and industry noise — a short primer and strategic implications
Over the past 18 months, a number of regulatory and classification actions have introduced new compliance and cost considerations:
- Customs reclassifications that could change tariff treatment for wireless headphones and earphones, potentially altering landed costs for certain import strategies.
- Public filings with communications authorities related to unreleased models, underscoring how product disclosure and certification timing can influence competitive response.
- Export control classifications that touch battery chemistries important to wireless devices, reinforcing the need for export‑compliant sourcing strategies.
- Air transport and safety rules affecting passenger carriage of lithium batteries — a factor in aftermarket logistics, warranty replacements and travel retailing.
Operationally, procurement and legal teams should run an immediate three‑tier checklist (short‑term certification readiness, medium‑term supply diversification, long‑term chemistry alternatives) that we document in the annex of the report. For product roadmaps, incorporate regulatory lead times into your development schedules to avoid delayed launches.
Five strategic moves to prioritize in 2026
- Lock in ecosystem integrations: Negotiate SDK and OS partnerships early to ensure spatial audio and low‑latency codecs are embedded before product launch.
- Adopt a modular battery & RF sourcing approach: Certify at least two independent suppliers for critical battery and radio components; evaluate alternative chemistries for medium‑term resilience.
- Design for services: Embed hooks for subscription and warranty extensions (e.g., device‑level identity, extended care upsells) to extract recurring revenue.
- Defend premium positioning with measurable UX metrics: Move beyond feature lists to standardized experience KPIs (noise‑cancellation dB equivalence, latency ms, battery cycle retention) to make competitive claims defensible.
- Prepare for regulatory shifts: Update import/tariff models, certify products against evolving customs classifications, and incorporate FAA/battery handling requirements into logistics playbooks.
How PW Consulting supports execution
Our full Headphone Market package is designed for rapid operationalization. Clients receive the forecast model in native spreadsheet form, slide decks tailored for executive and board briefings, and an implementation workshop that converts strategy into 90‑day and 18‑month roadmaps. We also provide an optional vendor‑due diligence bundle that includes supplier scorecards and compliance audits.
Closing — why act now
2026 is a pivot year. The combination of accelerating market growth, ecosystem consolidation, and regulatory realignments means that product timing, certification readiness and partner strategy will determine winners and losers. This introduction highlights the critical vectors; the full PW Consulting report contains the granular numbers, competitive scorecards, and executable playbooks that senior teams need to convert insights into market share and margin gains.
For executives ready to move from foresight to action, our gated research and advisory services provide the detailed segmentation, channel economics, and risk mitigations necessary to make 2026 the year your audio strategy scales profitably.
For detailed analysis of this topic, please visit the official page: Headphone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


