



PW Consulting: Calcium Hypochlorite Market to hit USD 1,074M by 2032 at 7.5% CAGR

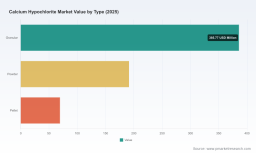
Calcium Hypochlorite Market — Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s latest industry primer positions calcium hypochlorite (Cal‑Hypo) as a strategically important specialty chemical for water sanitation, pool care, and a range of industrial disinfection applications. Using 2025 as the base year, our top‑line view shows the market expanding from roughly USD 456 million in 2020 to approximately USD 646.8 million in 2025, and projected to exceed USD 1.07 billion by 2032 — a compounded annual growth rate of 7.5% across the forecast window (2026–2032). For firms making capital, sourcing, pricing, or M&A choices in 2026, this trajectory is both an invitation and a challenge: growth is real, but it will be realized unevenly across geographies, product formats, and supply chains.
Calcium Hypochlorite Market
Why this study matters for 2026
- Translate headline growth into operational choices: which production formats and supply routes can deliver margin protection and volume capture in a higher‑cost input environment?
- Mitigate trade and regulatory risk: recent administrative reviews and duty continuations are changing import economics and supplier selection logic.
- Prioritize where to deploy scarce capex: brownfield expansions, product reformulation, or strategic acquisitions each require different timing and scale assumptions.
- Build defensible procurement and pricing strategies that incorporate energy and lime cost inflation while maintaining competitiveness in municipal and private channels.
Key market dynamics shaping 2026 decisions
Demand remains anchored in essential services — municipal drinking water, commercial and residential pool sanitation, and industrial disinfection — creating a resilient base even when broader industrial demand softens. That said, growth pockets are emerging for higher‑efficiency formulations, tablet and granular convenience formats, and blended products providing scale and fouling control for commercial pools and industrial loops.
Calcium Hypochlorite Market
On the supply side the market is meaningfully fragmented: the three largest producers account for roughly a quarter of the market and the top five just over thirty percent, indicating significant room for competitive moves by mid‑sized players and new entrants seeking regional strength or specialized formulations. Concentration metrics point to a market where supply shocks — whether weather events, plant outages, or policy shifts — can materially affect local availability and pricing.
Calcium Hypochlorite Market
Input costs are a live strategic variable. Over the period of interest, prices for both lime and industrial electricity rose by about 11% — a structural headwind for producers whose cost pass‑through is constrained by procurement cycles or contract structures. Concurrently, regulatory activity has intensified: a U.S. administrative review process led to continuation of antidumping and countervailing duties on certain imports effective February 10, 2026, altering the competitiveness calculus for imports from key origins. The EPA’s continued registration of hypochlorite‑based disinfectants signals regulatory acceptance of these chemistries when used per label, but firms must still manage labeling, safety, and transportation requirements rigorously.
Operationally, weather and event risk remain pertinent. Production interruptions tied to hurricanes and other extreme events have shown how plant downtime can cascade into supply tightness and price spikes. Capacity plays are already underway: several producers have announced expansions or new lines producing higher‑efficacy materials, a sign that incumbents expect sustained demand and are competing on product differentiation as well as scale.
Competitive landscape — strategic profiles you need on the radar
- Westlake Water Solutions (United States): legacy capabilities in granular and tablet forms; recent capacity expansion activity underscores a push to capture pool and municipal demand.
- Olin Corporation (United States): integrated chlor‑alkali footprint with product resumption following weather‑related disruption; important for buyers who prioritize supply continuity.
- Nippon Soda (Japan): focused on stabilized tablets and granules under an established brand; a reference point for quality and consistency in high‑value markets.
- Sree Rayalaseema Hi‑Strength Hypo Ltd. (India): regionally important manufacturer — relevant for strategies targeting South Asian demand or cost‑competitive sourcing.
- Innovative Water Care and other specialty players: offering blended and additive‑led products that illustrate productization as a route to higher margins.
- Major chemical integrators and regional specialists (PPG, Tosoh, Aditya Birla, Foshan Huiren, Barchemicals, ECSA, CORECHEM): a mix of global scale, regional distribution reach, and product specialization that buyers must map against supply risk and service offerings.
Recent corporate moves — capacity additions announced in early 2025, production resumptions post‑weather events, and new high‑efficiency production lines launched in 2024 — highlight three trends: (1) incumbents reinforcing footprint and reliability, (2) technology providers pushing higher‑strength products, and (3) regional players seizing local demand growth.
What the full PW Consulting report delivers (practical, operational outputs)
- Detailed market sizing and a flexible financial model (2020–2032) that lets you stress test price, volume, and input cost scenarios relevant to 2026 board deliberations.
- Segmented forecasts by region, product format (granular, powder, pellet/tablet), and end‑use, coupled with demand‑driver narratives and sensitivity analyses. (Note: this introduction intentionally omits the granular segmentation tables that are included in the full report.)
- Supplier and competitor playbooks: capacity maps, recent investments, production risks, and procurement scorecards for short‑listing vendors.
- Regulatory and trade tracker with actionable implications for import strategies, duty planning, and compliance roadmaps.
- Price index and input‑cost passthrough framework that translates lime and energy movements into EBITDA impact by product type.
- M&A screening matrix and playbook: targets by capability (capacity, geography, product innovation), integration risks, and expected synergies.
- Commercial playbook: product positioning, channel strategies (municipal vs. retail vs. industrial), and go‑to‑market options to capture premium segments.
Priority recommendations for 2026 (what to do in the next 12 months)
- Re‑baseline procurement contracts immediately. Lock in multi‑source supply for at least two critical feedstocks and build pricing collars that reflect recent 11%+ input inflation to avoid margin erosion.
- Stress‑test your logistics and inventory policy. Convert event‑driven outages into quantified scenarios and size safety inventory or alternate sourcing nodes to maintain service levels to municipal customers.
- Accelerate product differentiation where feasible. Small investments in stabilized formulations, tablet convenience, or anti‑scale blends can unlock price premiums in service‑sensitive channels.
- Review trade exposure and legal posture. Administrative reviews and duty continuations change landed cost dynamics; companies should coordinate commercial teams with trade counsel to quantify impact and adjust sourcing accordingly.
- Prioritize brownfield capacity over greenfield when timelines must be compressed — expansions ramp faster and carry less permitting risk in most jurisdictions.
- Targeted M&A and JV plays: look for regional producers with strong local distribution and compliance records, or technology vendors that enhance product efficacy or handling safety.
How to use this report in boardroom and investor discussions
Boards and C‑suites need two things in 2026: defensible numbers and prioritized options. The PW Consulting deliverable supplies both. Use the forecast model to translate volume growth into revenue and EBIT scenarios under conservative, base, and upside cases; map procurement choices to cash flow outcomes; and use the supplier scorecard to justify source consolidation or diversification to auditors and investors. The regulatory tracker and scenario appendices provide language for risk disclosures and contingency budgeting. Finally, the M&A screen converts qualitative strategic imperatives into a short list of targets with estimated valuation bands and integration checklists.
Conclusion — strategic value in one line
For companies that must decide on capex, sourcing, pricing, or acquisition in 2026, the Cal‑Hypo market offers growth and margin recovery opportunities — but success will require disciplined scenario planning, informed trade strategy, and a clear product differentiation agenda. PW Consulting’s full study provides the granular datasets, supplier analytics, and executable playbooks necessary to turn the market’s 7.5% CAGR and billion‑dollar potential into measurable, board‑ready actions. For firms ready to move from high‑level conviction to executable plans, the detailed segment tables, price forecasts, supplier scorecards, and transaction playbooks in the full report are essential next steps.
For detailed analysis of this topic, please visit the official page: Calcium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


