



PW Consulting: Welding Helmets Market to Reach USD 2,166M by 2032 at 5.3% CAGR

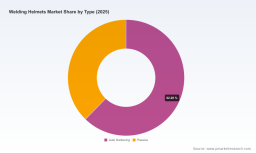
Welding Helmets Market: Strategic Outlook for 2026 Decision‑Makers
As organizations finalize budgets and product roadmaps for 2026, the welding helmets market presents a measured and actionable growth narrative that demands strategic attention. Our assessment—anchored on a 2025 base year and a forecast window running 2026–2032—shows a steady expansion at a 5.3% CAGR. The market scaled from roughly USD 1.2 billion in 2020 to approximately USD 1.515 billion in 2025 and is projected to approach the USD 2.17 billion range by 2032. Those headline numbers mask important inflection points driven by product innovation, regulatory dynamics, and shifting industrial demand that will determine winners and losers in the coming 18–36 months.
Welding Helmets Market
Why this research matters for 2026 decisions
-
Investment prioritization: The market’s mid-single-digit CAGR creates predictable baseline returns, but incremental value will accrue to firms that time tech adoption, certification investments, and channel expansion correctly.
Welding Helmets Market -
Product roadmaps: Advances in optics, larger fields of view, integrated respiratory systems, and purpose‑built laser protection are reshaping specification sheets. R&D allocations made in 2026 will be reflected in differentiated product introductions by 2027–2028.
Welding Helmets Market -
M&A and partnerships: A concentrated vendor landscape provides both opportunity and risk — consolidation dynamics favor strategic bolt‑on acquisitions and exclusive distribution agreements as rapid ways to scale capability and market access.
Market trajectory and structural read
The welding helmets market exhibits a classic technology-upgrade cycle layered on a stable industrial base. The macro picture is one of recurring replacement demand (driven by safety cycles and wear-and-tear) plus incremental unit growth as auto-darkening and integrated-protection products displace legacy passive designs in many commercial and industrial settings. The 5.3% CAGR reflects a blend of volume growth and upward product-mix migration toward higher‑value items.
Structural features worth noting for 2026 strategy:
-
Consolidation tendency: Top-tier players command a substantial share of the market, underlining economies of scale in optics development, headgear ergonomics, and after‑sales networks. This creates a two-speed market in which global incumbents set tech benchmarks and regional players compete on price, service, or niche specifications.
-
Product premiumization: Enhanced optics (multi‑color/clear‑light technologies), expanded viewing areas, and integrated respiratory protection are converting basic protective gear into differentiated safety systems. These product attributes are correlated with higher ASPs and lower price elasticity in professional segments.
-
Safety and compliance as demand drivers: Certification regimes and interpretation of import classifications influence procurement cycles. Compliance investments—both for product certification and workplace implementation—are non-trivial for manufacturers and industrial buyers alike.
Regulatory and standards dynamics — implications for suppliers and buyers
Regulatory touchpoints are actively shaping product specification and procurement risk: ANSI Z87.1 eye/face protection criteria, classifications related to auto-darkening models under the HTS framework, and the interplay between NIOSH approvals and OSHA equivalency for supplied‑air systems all matter. In addition, head protection standards related to impact and electrical shock influence accessory and headgear design choices. For suppliers, certification timelines and testing investments are gating factors; for large buyers, a compliant vendor list reduces liability and total cost of ownership.
Competitive landscape — what incumbents are betting on
The market is populated by a mix of global incumbents and specialized niche brands. The competitive moves observed through late‑2025 and early‑2026 indicate a focus on optics, comfort, and system integration. Notable strategic postures include:
-
Lincoln Electric (Cleveland, Ohio) : Reinforces optics and modularity with products emphasizing large viewing areas and replaceability. Their approach is durability plus serviceability—appealing to heavy industrial customers who prioritize uptime and parts availability.
-
Miller Electric (Appleton, Wisconsin) : Prioritizes operator comfort and productivity with next‑generation headgear and ClearLight lens advancements. Latest catalog updates signal a push to win continuous‑weld environments where operator fatigue materially affects throughput.
-
Optrel AG (Wattwil, Switzerland) : Competes on premium optics and field of view expansion. Recent product-line extensions underline a tech‑led differentiation strategy aimed at high‑visibility, precision welding applications.
-
3M (Speedglas series, Saint Paul) : Advances integration—curved filters for TIG, variable color tech, and respiratory coupling—targeting specialist segments where safety systems must act as one cohesive product.
-
ESAB (Torrington, Connecticut) : Focuses on ergonomic, lightweight designs for heavy-duty settings, aiming to reduce operator fatigue while maintaining ruggedness.
-
Kemppi (Lahti, Finland) : Leverages extended head protection and respiratory compatibility for markets demanding elevated protection levels.
-
Jackson Safety and Fibre Metal : Deliver targeted niche propositions—laser protection and robust lift‑front thermoplastic designs, respectively—serving specialized industrial applications where compliance and form‑factor trump broader feature sets.
Recent product launches and catalog refreshes across multiple vendors—spanning improved headgear, expanded fields of view, laser‑rated models, and curved ADF filters—signal that 2026 procurement cycles will favor products demonstrating measured safety and productivity gains validated by third‑party certifications.
Strategic imperatives for 2026 (playbook for executives)
-
Prioritize certification pipelines: If you are a manufacturer, allocate budgets to obtain and publicize relevant ANSI/NIOSH approvals now—lead times and lab availability will elongate as demand for certified integrated systems grows.
-
Segment-by-value, not just by application: Treat auto‑darkening, integrated respiratory, and laser‑protection as distinct product tiers with tailored commercialization plans rather than incremental SKUs.
-
Double down on ergonomics and operator productivity: For OEMs and channel partners, prove value through field trials that quantify productivity improvements and fatigue reduction—these metrics accelerate purchasing decisions in professional buyers.
-
Consider targeted M&A: Given the market’s concentration dynamics, bolt‑on acquisitions that add optics IP, certification pipelines, or regional distribution can yield rapid scale advantages.
-
Supply chain resilience: Security of optical components, specialized electronics for ADFs, and headgear polymers should be prioritized; dual‑sourcing critical components mitigates both lead‑time and tariff exposure.
-
Channel and aftermarket monetization: Warranty, replacement lenses, and certified maintenance programs represent a durable revenue stream. Plan go‑to‑market models that capture aftermarket share through subscription or service bundles.
What PW Consulting’s full report delivers (practical, actionable content)
Our comprehensive study is structured to support decision‑making across commercial functions. Highlights include:
-
Top-down and bottoms-up market sizing with scenario paths for conservative, base, and aggressive adoption through 2032 (base year 2025).
-
Demand drivers and adoption curves for key product technologies, including ADFs, expanded‑field lenses, respiratory‑integrated systems, and laser‑rated helmets.
-
Competitive benchmarking: product feature matrices, pricing buckets, distribution footprints, and patent/IP intelligence.
-
Regulatory and compliance matrix mapping standards to product design choices and procurement checklists for industrial buyers.
-
Channel strategy playbooks for OEMs, distributors, and after‑sales providers, including commercial models and margin analysis.
-
M&A target screening and valuation frameworks tailored to buyers seeking scale in optics, electronics, or regional reach.
-
Supply‑chain risk heatmaps and mitigation plans for critical components and tariff/regulatory exposure.
-
Customizable slide decks and an executive briefing template to accelerate internal alignment with commercial plans.
How to use this intelligence in Q1–Q2 2026
-
Board and investor briefings: Use the market trajectory and concentration metrics as the foundation for capital allocation and M&A deliberations.
-
R&D prioritization: Recalibrate product roadmaps to emphasize certifications and ergonomic improvements that demonstrably reduce total cost of ownership.
-
Procurement and operations: Build compliant vendor lists and stagger replacement cycles to smooth CAPEX requirements while ensuring certified protection levels across sites.
-
Commercial planning: Adopt differentiated pricing by product tier; pilot subscription or retrofit programs for higher‑value ADFs and respiratory‑enabled helmets.
Final synthesis — positioning for the next cycle
The welding helmets market is not a winner‑takes‑all arena, but it rewards clarity of focus. The prevailing market structure favors players who can combine credible certification, demonstrable operator productivity gains, and resilient supply chains. For buyer organizations, 2026 is the year to codify safety standards into procurement specifications while selectively investing in higher‑value PPE that reduces downstream risk and improves operator efficiency. For vendors, the path to above‑market growth runs through technology differentiation, certification leadership, and targeted channel plays—backed by a disciplined M&A or partnership strategy where native scale is insufficient.
PW Consulting’s full report provides the proprietary segmentation, regional and application splits, and granular vendor benchmarking required to convert these strategic imperatives into executable plans. Detailed numeric breakdowns and the comprehensive dataset are intentionally reserved for the complete study to support confidential decision workflows—contact our team to access the full intelligence package and schedule a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Welding Helmets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


