



PW Consulting: Roughness & Contour Measuring Machines to Reach USD 344.8M by 2032 (CAGR 6.98%)

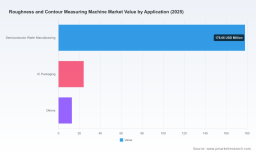
Roughness and Contour Measuring Machine Market — Strategic Preview for 2026 Decision‑Makers
As capital allocation committees and engineering leadership set priorities for 2026, the choices they make about metrology platforms will have multi‑year implications for product quality, throughput and cost of ownership. PW Consulting’s new market study provides a decision‑grade lens on the Roughness and Contour Measuring Machine market using a 2025 base year and a 2026–2032 forecast horizon. The global market — measured in USD Million — recovered steadily through the early 2020s and is projected to expand at a compound annual growth rate (CAGR) of 6.98% over the forecast period, reflecting accelerating demand across high‑precision manufacturing segments. Our briefing below highlights the strategic value of the full report for 2026 planning while deliberately withholding granular regional and application splits so readers must consult the source for complete proprietary tables and models.
Roughness and Contour Measuring Machine Market
Why this study matters to leaders in 2026
-
Timing of investment: With market momentum established by 2025, selecting the right measurement technology in 2026 impacts line yield and product qualification cycles for several years. The study quantifies capital intensity and payback timing under multiple adoption scenarios so CXOs can prioritize upgrades vs. incremental replacements.
Roughness and Contour Measuring Machine Market -
Technology roadmap alignment: The market is being shaped by a proliferation of tactile, optical and hybrid systems. Strategic sourcing decisions — whether to standardize on stylus‑based profilometers, deploy focus‑variation optical systems, or pursue hybrid platforms — require an independent assessment of accuracy tradeoffs, cycle times and shop‑floor robustness. Our analysis benchmarks incumbent and emerging approaches against specific manufacturing needs.
Roughness and Contour Measuring Machine Market -
M&A and partnership screening: 2026 will remain an active year for tuck‑ins and distribution partnerships. The report provides a vendor scorecard tied to revenue resilience, channel reach and IP depth to help corporate development teams screen targets and craft integration assumptions.
-
Regulatory and compliance planning: New or updated quality standards influence acceptance criteria and supplier contracts. The full report maps how DIN and ISO measurement standards interplay with qualification protocols and service obligations — essential context for quality and procurement teams drafting 2026 contracts.
Macro trajectory and what it implies
From the pandemic recovery through 2025 the market showed consistent expansion in measured revenues (reported in USD Million). The growth outlook into 2032 is robust — the implied CAGR of 6.98% reflects structural drivers rather than a short cyclical uptick. For planning purposes, procurement officers should assume a multi‑year technology refresh cycle influenced by: tighter surface specification tolerances from advanced componentry, rising automation of inspection tasks, and the need to integrate metrology data into manufacturing execution and quality IT stacks. These pressures create both capex demand for measurement hardware and recurring revenue opportunities for service and software vendors.
Demand drivers, constraints and near‑term uncertainties
-
End‑market intensity: High‑precision sectors — notably semiconductor wafer processing, advanced packaging and certain precision components — are the primary engines of demand. These applications increase requirements for sub‑micron repeatability and combined roughness/contour analysis, favoring suppliers that can demonstrate validated performance across temperature and vibration regimes.
-
Technology substitution and hybridization: Optical focus‑variation systems offer non‑contact, fast 3D surface mapping while stylus‑based devices retain advantages in traceability and tactile verification under established standards. Hybrid offerings that combine both families are gaining traction where throughput and traceable metrology are simultaneously required.
-
Raw material and input cost pressures: Manufacturing cost structures are influenced by upstream commodity moves. For example, the U.S. steel mill products producer price index rose materially from 2025 into 2026, adding cost pressure on frame and fixture manufacturing as well as service part inventories. Vendors and buyers must factor these cost trends into total cost of ownership (TCO) models.
-
Standards and traceability: Instruments in the market comply with established measurement standards (notably DIN EN ISO 21920 and DIN EN ISO 25178, which align with ISO 25178 and related surface descriptors). These standards drive acceptance criteria, supplier selection and calibration workflows — a non‑negotiable factor for regulated industries.
Competitive landscape: positioning of leading vendors
The competitive map is characterized by specialist metrology firms and diversified measurement corporations. Market concentration remains modest — no single vendor commands a dominant share — which sustains healthy competition on technology differentiation, service propositions and software integration. Below we summarize strategic positions of notable vendors covered in the full research.
-
Mahr GmbH (Göttingen, Germany) — Mahr’s MarSurf LD series (LD 280 and LD 140) exemplifies a mature stylus‑based approach optimized for simultaneous roughness and contour measurement. The company has extended both manual and motorized options, and a 2026 launch expanded automated station capabilities for integrated roughness, contour and waviness inspection. Mahr’s strengths lie in traceable tactile metrology, established calibration ecosystems and deep standards alignment.
-
Alicona Imaging GmbH (Raaba, Austria) — Alicona’s InfiniteFocus G6 and SL systems are representative of optical focus‑variation 3D measurement platforms that combine shape, surface roughness and contour assessment in one optical workflow. Alicona’s value proposition centers on non‑contact scanning for delicate surfaces and rapid 3D data capture suitable for inline or near‑line inspection strategies.
-
Taylor Hobson (Leicester, UK) — Taylor Hobson’s product span — from Surtronic handheld roughness testers to the Intra PRO portable profiler — targets shop‑floor flexibility. Their portable instruments position them as a practical choice for manufacturers prioritizing field diagnostics, rapid troubleshooting and reduced inspection footprint.
-
Mitutoyo Corporation (Kawasaki, Japan) — Mitutoyo’s FORMTRACER Avant series sits within a hybrid systems strategy, offering simultaneous contour and surface roughness measurement with an emphasis on automated workflows and integration into coordinate metrology environments. Mitutoyo’s global service network supports large installed bases.
-
HOMMEL ETAMIC (Jenoptik Industrial Metrology Germany GmbH) — HOMMEL ETAMIC’s Waveline and Formline families cover portable and stationary tactile measurement needs. The company used Control 2025 to preview the Formline F900, a tactile device that broadens combined shape, position, roughness and twist measurement capabilities — illustrating a product roadmap that balances shop‑floor usability with expanded functional scope.
Collectively, these vendors illustrate three strategic playbooks: (1) deep tactile specialization with traceability and calibration services; (2) optical and non‑contact innovation focused on speed and surface mapping; and (3) hybrid or modular platforms designed to capture both markets. The full report contains a vendor benchmarking framework that evaluates offerings across 12 parameters including accuracy, throughput, integration readiness, lifecycle cost and services coverage.
What the full PW Consulting report contains (practical deliverables)
-
Market sizing and forecasting model (2020–2032) with scenario analysis and sensitivity to capex and commodity inputs.
-
Methodology appendix detailing data sources, triangulation approach and model assumptions (useful for internal audit and board review).
-
Vendor profiles and competitive scorecards with feature comparisons, go‑to‑market maps and suggested partner/competitor watch lists.
-
Technology adoption playbooks showing when to standardize, when to pilot hybrids, and how to phase integration with MES/automation stacks.
-
Procurement‑grade RFP checklist and installation acceptance test (IAT) templates tailored to tactile, optical and hybrid systems.
-
Service and spare parts TCO models, including calibration frequency sensitivity and recommended service‑level agreements.
-
Regulatory alignment matrix illustrating how DIN/ISO standards translate to inspection protocols and supplier contractual clauses.
-
Risk heatmap covering commodity cost exposure, single‑source risks, and supplier concentration scenarios, plus contingency options.
Actionable recommendations for 2026
-
Run a three‑year pilot of hybrid measurement platforms where product complexity justifies the premium — this hedges between optical speed and tactile traceability and accelerates time‑to‑qualification for complex surfaces.
-
Revise procurement TCO models to account for rising input costs and potential calibration cycle increases; include spare‑parts indexation clauses to mitigate margin erosion from commodity swings.
-
Mandate standards compliance (DIN/ISO family) as a contractual precondition for capital purchases and calibration services to preserve auditability across regulated product lines.
-
Prioritize vendors that provide open API and data integration capabilities to avoid siloed inspection data — metrology must feed into your quality analytics and digital twin initiatives.
-
For potential acquirers, focus diligence on recurring service revenue and software‑enabled analytics rather than hardware resale alone; these elements drive higher multiples and durable margins.
How to use this preview
This article is a strategic preview that highlights the decision‑relevant findings and vendor landscape that PW Consulting uncovered. It is designed to help senior executives and functional leaders orient their 2026 plans without divulging the proprietary segment tables, regional breakouts and application shares that underpin our models. Those detailed splits — and an interactive model you can adapt to your company’s specific volumes and cost structure — are only available in the complete study.
Contact PW Consulting to request the full Roughness and Contour Measuring Machine Market report and the editable forecast model if you are evaluating capex commitments, scouting M&A targets, or updating inspection strategies for 2026. Our team can also deliver an executive workshop to translate the insights into a one‑page go‑forward plan aligned with your product roadmap and financial targets.
For detailed analysis of this topic, please visit the official page: Roughness and Contour Measuring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


