



PW Consulting: LCP Films & Laminates Market to reach USD 246.8 Million by 2032 (5.24% CAGR)

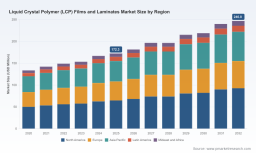
Liquid Crystal Polymer (LCP) Films and Laminates Market: Strategic Implications for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic primer on the Liquid Crystal Polymer (LCP) films and laminates market — a sector that is transitioning from a niche high‑performance polymer family to a broadly deployed enabling material across high‑frequency electronics, advanced packaging and select medical and industrial applications. This briefing distills the research foundations, the near‑term market trajectory, competitive dynamics, and the concrete strategic choices executives should be making in 2026. The narrative is intentionally high‑signal: it demonstrates the depth of our analysis while reserving detailed subsegment metrics for the full report.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Executive snapshot
LCP markets have shown steady expansion through the early 2020s and enter 2026 with positive momentum. Our base year analysis (2025) indicates a mature but still-growing market that has expanded materially since 2020 and is projected to continue expanding through the 2026–2032 forecast window at a mid‑single‑digit compound annual growth rate (CAGR). Market concentration remains moderate: the combined revenue share of the top three and top five suppliers confirms a fragmented supplier base with leading specialists and many regional players — a structure that creates M&A and partnership opportunities for scale seekers.
Liquid Crystal Polymer (LCP) Films and Laminates Market
- Clear growth pathway: a predictable CAGR across the forecast horizon provides a reliable demand foundation for capex decisions and product portfolio prioritization.
- Fragmented supply side: the CR3 and CR5 metrics indicate room for consolidation and for fast followers to build scale through selective vertical integration.
- Technology differentiation: recent product launches and patents are reshaping the value proposition from simple film supply to integrated high‑frequency substrate solutions.
Market trajectory — what the numbers tell us
From 2020 through 2025 the LCP films and laminates market moved from early recovery into steady adoption, driven by high‑frequency telecom applications, PCB innovations and semiconductor packaging needs. Our base‑year assessment captures that momentum and projects a continued expansion across the next six years under a set of practical assumptions: sustained roll‑out of 5G and next‑wave RF front‑end architectures, persistent demand for thinner and higher‑reliability substrates in advanced packaging, and growing, selective adoption in medical and flexible electronics niches.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Two numeric anchors define the investment context for 2026 planners: a clear multi‑year growth rate that validates multi‑year capital programs, and a forecast path that highlights cyclical inflection points where demand, capacity and pricing will intersect. Executives should treat these anchors as directional guides for inventory policy, capacity timing and strategic partnerships rather than precise targets to be hit in isolation.
Report contents — practical, transaction‑ready analysis
The underlying study is built for decision implementation. For executives considering investments, procurement shifts or technology roadmaps, the report provides:
- Demand modelling with scenario overlays: baseline, upside (accelerated telecom and packaging adoption), and downside (feedstock or energy shocks), enabling stress‑tested capacity planning.
- Cost‑to‑serve diagnostics: energy sensitivity, feedstock exposure, and processing cost differentials that inform location, automation and supplier selection choices.
- Commercial playbooks: go‑to‑market pathways for product extensions (films → adhesive‑free FCCLs → integrated substrates), recommended partner archetypes, and early customer engagement templates.
- M&A and partnering scorecards: valuation multipliers, capability gaps, and integration risk checklists calibrated to both strategic and financial acquirers.
- Regulatory and circularity pathways: compliance impacts and near‑term forward plans for end‑of‑life management and recycling trials suitable for European and global contexts.
Note: this briefing deliberately omits granular subsegment tables and precise regional/application splits; the full dataset and model are available through the complete report package.
Competitive landscape — who matters and why
The competitive topology is a mix of global polymer manufacturers, specialized substrate firms, and regional laminate producers. The most active players combine materials science, manufacturing scale and application‑level system relationships.
- Material incumbents with resin and film expertise (examples include firms producing LCP resins and grades): they remain advantaged where upstream monomer control and formulation IP create performance and margin differentiation. These players also accelerate commercialization when they expand into films and laminates.
- Integrated electronics suppliers and substrate specialists: companies that can pair LCP film capabilities with multilayer laminate production and advanced inner‑cavity or adhesiveless constructions are redefining the product set for RF and high‑frequency markets.
- Regional challengers: a number of Asia‑based manufacturers are focused on cost‑competitive film and laminate supply, often coupled with close proximity to key electronics manufacturing clusters.
Recent corporate actions signal the strategic priorities driving competitive moves:
- Product innovation and market timing: a major producer announced the mass production of an inner‑cavity LCP flexible substrate for ultra‑low‑loss high‑frequency applications late in 2025 — a development that moves LCPs from material to system‑level enabler for certain telecom and radar use cases.
- Capability pooling via M&A: an acquisition in early 2025 by a leading chemical firm expanded its neat resin franchise, reinforcing follow‑through into ICT and mobility end markets.
- Channel and portfolio reinforcement: distribution partnerships renewed in 2025 improved market access for global LCP families and accelerated adoption by contract manufacturers and PCB fabs.
- IP fencing and defensive positioning: patent grants for multilayer compositions underscore the R&D race to own differentiated laminate stacks tailored to RF and high‑speed applications.
Dynamics and headwinds that will shape 2026 decisions
Four structural dynamics merit executive attention when setting 2026 priorities:
- Feedstock concentration risk: specialty monomer supply chains remain concentrated with single‑source exposure in certain geographies. Procurement teams should model multi‑sourcing strategies and strategic inventory coverage to blunt potential interruptions.
- Energy and processing cost pressure: in some regions LCP processing consumes substantially more electricity than alternate high‑performance polymers, creating location‑specific cost disadvantages as tariffs rise. Energy intensity should therefore be a core input to any new capacity siting analysis.
- Geopolitical disruption to hydrocarbon logistics: recent regional conflicts have demonstrated how shifts in naphtha/LPG flows and LNG rerouting can propagate into feedstock and utility price volatility. Scenario planning that combines supply interruptions with price shocks is now standard practice for resilient capex and contract strategies.
- Regulatory and circularity requirements: EU circular‑economy initiatives and institute‑led recycling investigations are increasing the cost of non‑compliance while opening the door to early‑mover differentiation through end‑of‑life solutions and recycled content offerings.
Concrete strategic moves for 2026
Based on the combination of market growth, technology shifts and supply‑side dynamics, we recommend a focused set of actions for corporate leaders:
- Prioritize dual‑track capacity planning: pursue modular, debottleneckable investments that can be accelerated if high‑frequency substrate demand materializes faster than the baseline scenario.
- Lock in feedstock resilience: establish layered contracts (short‑term indexed + strategic long‑term) with geographic diversity and optionality clauses; consider upstream partnerships or minority stakes in monomer suppliers where technically and financially viable.
- Invest in high‑value differentiation: move beyond commodity films toward integrated substrates (inner‑cavity, adhesiveless FCCLs) and validated laminate stacks for RF and semiconductor packaging where margins and customer stickiness are higher.
- Embed energy strategy into location decisions: select sites based on a blended metric of energy cost, grid reliability, and access to low‑carbon electricity to avoid utility‑driven margin erosion.
- Lead on recyclability and compliance: develop pilot programs for LCP end‑of‑life processing and recycled feedstock trials to preempt regulatory headwinds and capture sustainability premiums with blue‑chip customers.
- Use M&A and partnerships smartly: target bolt‑on buys to fill capability gaps (e.g., laminates, FCCL manufacturing, IP portfolios) rather than chasing scale in low‑margin commodity film production.
Why this briefing matters for 2026 decisions
By 2026, commercial outcomes in the LCP space will be determined less by raw market growth and more by the timing of technology transitions, the resilience of feedstock chains, and the ability of firms to offer system‑level solutions that reduce customer integration risk. The market’s mid‑single‑digit growth profile provides a steady revenue backdrop, but strategy will be won by those who combine supply‑chain foresight, targeted product differentiation, and regulatory alignment.
Accessing the full intelligence
This article showcases the analytical orientation and strategic framing contained in PW Consulting’s full LCP films and laminates study. To preserve the report’s commercial integrity and to follow the “preview” principle, we have withheld detailed subsegment tables, regional/applications splits, and the full financial model in this primer. Executives and project teams who need the transaction‑ready datasets, supplier scorecards and the scenario models should consult the complete report package.
Contact PW Consulting to obtain the full dataset and a tailored briefing that maps this sector analysis to your portfolio, supply chain and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Liquid Crystal Polymer (LCP) Films and Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


