



PW Consulting: PEKK Market Set for 6.98% CAGR (2026-2032)

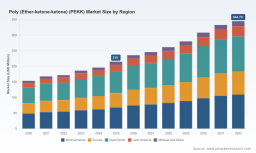
PEKK Market 2026: A Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high-level, actionable preview of our forthcoming Poly (Ether-ketone-ketone) (PEKK) Market study. This piece is designed as a strategic “trailer”: it demonstrates the report’s analytical depth, frames the critical choices facing leadership in 2026, and highlights why immediate access to the full study is mission-critical — while intentionally withholding granular segment-level figures to preserve premium value for subscribers.
Poly (Ether-ketone-ketone) (PEKK) Market
Why PEKK matters in 2026
PEKK has moved from a niche engineering polymer to an industrial lever in high-value sectors — notably aerospace, advanced electronics, and electrified powertrains. Between 2020 and our base year (2025), the PEKK market expanded materially, and our modeling projects robust, steady growth through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 6.98%. Measured in USD (Million), cumulative market momentum across 2020–2025 establishes a clear inflection point entering 2026: the market that was modest in scale at the start of the decade is now large enough to influence supplier strategies, capital allocation, and product roadmaps.
Poly (Ether-ketone-ketone) (PEKK) Market
Two macro dynamics drive this transition. First, performance requirements in target applications (high-temperature stability, dielectric performance, chemical resistance, and suitability for additive manufacturing) are increasingly non-negotiable. Second, supply-side shifts — new grades, capacity additions, and targeted product launches — are lowering barriers to industrial adoption. Collectively, these forces create a strategic window in 2026: companies that act with calibrated speed can capture preferential positioning as specifications harden and qualification cycles compress.
Poly (Ether-ketone-ketone) (PEKK) Market
What 2026 decisions must solve
- Supply security vs cost optimization: PEKK’s supply base remains technologically concentrated but commercially fragmented. Market concentration metrics indicate a low-to-moderate level of dominance by the largest suppliers (CR3 and CR5 remain in the mid-20s percent range), which means buyers must balance multi-sourcing for resilience against the price and logistics trade-offs of diversifying vendors.
- Qualification cadence and commercialization risk: Lead times for materials qualification in aerospace and semiconductor segments remain long. Firms must decide in 2026 whether to accelerate co-development with suppliers (bearing near-term R&D or qualification costs) or to wait for broader market adoption and potentially face higher entry barriers.
- Technology pathway selection: Additive manufacturing (AM) compatibility, high-voltage insulation grades for EVs, and thin-film processability are three divergent development tracks. Allocating investment across these requires reframing product roadmaps into scenario-based portfolios that capture upside without over-committing scarce CAPEX.
- Regulatory and trade exposure: New EU regulations on pellet loss and active trade measures (notably tariffs applied to PEEK/PAEK imports in certain markets) meaningfully alter total landed cost and compliance overheads. Firms must integrate regulatory risk into procurement and site-selection decisions immediately.
Industry dynamics shaping 2026 strategy
- Product innovation and targeted launches: Through 2025, several suppliers introduced application-specific PEKK grades — from aerospace collaborations that focus on lightweighting to formulations optimized for additive manufacturing and high-voltage EV insulation. Expect the pace of niche grade introductions to accelerate in 2026 as suppliers compete on differentiated performance rather than bulk pricing.
- Capacity response: Primary producers have reacted to demand signals with selective capacity expansions. These moves reduce the probability of acute shortages but create a transitional price dynamic: near-term upward pressure from feedstock and labor cost increases can coexist with medium-term price moderation as new volumes ramp up.
- Regulatory pressure and compliance cost: The EU’s Regulation (EU) 2025/2365 on plastic pellet loss raises operational compliance costs for polymer processors and suppliers. The regulation’s requirements — containment, incident tracking, formal training and documented pellet management — will shift cost structures and favor players with advanced containment and traceability systems.
- Trade friction and tariffs: Elevated tariffs applied to certain PAEK/PEEK imports into North America alter supply-chain calculus and favor regionalized sourcing or nearshoring strategies. For companies selling into tariff-exposed markets, tariff mitigation must be a discrete line item in sourcing models for 2026 decisions.
- Input cost environment: Announcements from leading polymer producers of price adjustments reflect an environment where labor, energy, and feedstock volatility are real constraints. Buyers should assume higher base costs in 2026 than in recent historical norms and model sensitivity scenarios accordingly.
Competitive landscape — how leading firms are positioning
The competitive set combines incumbent chemical majors, specialty polymer houses, and application-focused manufacturers. Each archetype brings different advantages for customers and partners; understanding these different operating models is essential for effective partner selection and M&A screening.
- Arkema S.A. (France): Arkema’s strategy emphasizes advanced resin formulations and integrated customer support for high-performance applications. Their R&D-led approach targets collaboration with OEMs that require customized resin properties and processability guidance. For buyers, Arkema represents a partner capable of co-development at scale and with rigorous quality systems.
- Evonik Industries AG (Germany): Evonik is leveraging its materials science platform to expand PEKK offerings, including grades aimed at additive manufacturing and specialty engineering uses. Recent catalog updates and price adjustments indicate a dual strategy: capture premium AM and electrification segments while recalibrating pricing to reflect increased input costs. Evonik’s global footprint and application engineering capabilities make them a preferred collaborator for process-intensive conversions.
- Solvay S.A. (Belgium): Solvay combines polymer expertise with deep application knowledge in aerospace and automotive. Their differentiation is in systems-level thinking — packaging resin properties with processing recommendations and long-term qualification support. For strategic buyers, Solvay is attractive where integrated material-performance validation is needed.
- Victrex plc (United Kingdom): Victrex is a specialty PAEK player with a heritage in high-performance thermoplastics. Their strength lies in established supply relationships with critical industries and a proven track record for qualifying materials in regulated environments. Victrex’s role is often as a preferred supplier for customers prioritizing qualification history and long-term lifecycle support.
- Oxford Performance Materials, Inc. (United States): Oxford brings a strong focus on application platforms where PEKK’s performance unlocks system-level advantages — particularly in additive manufacturing for medical and aerospace applications. Their vertical orientation on specific use cases makes them a strategic partner for OEMs seeking rapid application development and end-to-end validation.
Recent market moves amplify these strategic choices: BASF’s partnership with an aerospace manufacturer (Sept 2025) signals increased OEM engagement; Evonik’s product catalog expansion (Aug 2025) shows a push into AM; SABIC’s capacity additions (July 2025) reflect supplier willingness to scale; and new grades optimized for 800V EV battery insulation suggest representational demand from electrification programs. Together, these developments compress the window for decisive action in 2026.
What our report delivers — practical and executable
The full PW Consulting PEKK Market study is built for enterprise decision-making. It combines quantitative rigor with deployment-level guidance across procurement, product, and corporate strategy. Key deliverables include:
- Market sizing and validated demand curves (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario-based outlooks under different adoption and regulatory assumptions.
- Supply-chain heatmaps and a supplier scorecard that benchmarks technical capability, geographic footprint, qualification track-record, and commercial flexibility.
- Competitive intelligence dossiers on incumbent and emergent suppliers, including capability gap analysis and partnership suitability matrices.
- Price and cost-stack models that incorporate feedstock, labor, regulatory compliance, and tariff impacts — enabling total landed cost modeling for 2026 procurement strategies.
- Technology roadmaps and go-to-market playbooks for three priority tracks: additive manufacturing, high-voltage EV insulation, and aerospace-grade structural components.
- M&A and JV target screening with financial stress-testing under alternate tariff and regulatory scenarios.
- Operational checklists for compliance with pellet-loss and containment regulations, including training and incident-tracking templates.
- Actionable near-term recommendations for CAPEX allocation, supplier lock-in timing, and co-development contracting terms that preserve optionality.
How leaders should act in 2026 — a short playbook
- Immediate (0–6 months): Run a rapid supplier resilience audit, stress-testing current agreements against tariff exposure and the new EU containment requirements. Fast-track one co-development pilot for a high-priority application where lead-time arbitrage will create market advantage.
- Medium-term (6–18 months): Invest selectively in qualification programs (shared-risk contracts) for PEKK grades that map to strategic product lines. Lock in partial supply through capacity reservation clauses while preserving flexibility via formula-based pricing mechanisms that account for validated feedstock indices.
- Strategic (18–36 months): Evaluate targeted M&A or JVs to secure upstream integration or unique grade access, especially where supplier R&D capabilities provide differentiation. Reassess global footprint choices to mitigate tariff and logistics drag.
Closing — why the full report is indispensable
Our analysis shows the PEKK market entering a phase where technical differentiation, supply security, and regulatory compliance define winners and losers. The headline metrics — market sizing from 2020 through 2025, the base-year calibration at 2025, and our forecast through 2032 at a 6.98% CAGR — frame an opportunity set that is large enough to require strategic choices in 2026. Yet the tactical levers (which suppliers to prioritize, which grades to co-develop, and how to structure commercial terms) demand granular, validated inputs that we have assembled in the full study.
For executives preparing budgets, procurement leaders recalibrating supplier panels, and technology heads prioritizing R&D spend, the full PW Consulting PEKK Market report delivers the practical intelligence you need to convert market momentum into competitive advantage. Contact PW Consulting to access the complete report, supplier scorecards, and proprietary models that translate these insights into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Poly (Ether-ketone-ketone) (PEKK) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


