



PW Consulting: Phenolic Foam Board Market to Reach USD 234.5 Million by 2032 at 5.6% CAGR

Phenolic Foam Board Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
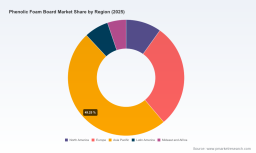
Between 2020 and 2025 the global phenolic foam board market expanded from a base of approximately USD 122.0 Million to USD 160.5 Million (base year 2025). Our forward-looking analysis projects continued expansion into the forecast window (2026–2032), with the market expected to reach roughly USD 173.8 Million in 2026 and to approach USD 234.5 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 5.6%. Market concentration is moderate: the top three firms account for roughly 52% of the market, and the top five account for about 58%, creating a structure of several large, global incumbents and a competitive field of regional manufacturers and specialists.
Phenolic Foam Board Market
Why this report matters for 2026 strategy
- Actionable timing: 2026 is a pivotal year—policy resets (notably across the EU and China) intersect with capital expansion programs announced in 2024–2025 and new product launches that will start to influence supply, pricing and specification dynamics. This study isolates near-term inflection points and maps decision levers to calendar year 2026 priorities.
- Investment triage: Whether you are allocating capital to capacity, retrofitting production lines for low-emission chemistries, or evaluating M&A targets, our forward curves and sensitivity scenarios show where returns are concentrated and which variables drive downside risk.
- Regulatory readiness: With aggressive building-performance standards (including the EU’s EPBD recast and updated Chinese residential efficiency codes), specifying phenolic foam for ultra-high-performance thermal and fire-safe envelopes is becoming a compliance and value play. The report translates these regulatory changes into volumetric and specification impacts—essential for product roadmap and certification planning.
- Supply-chain and input-cost planning: Raw-material volatility (e.g., phenolic resin benchmark prices observed in China) is already influencing margin profiles. Our analysis provides procurement strategies and hedging alternatives that are calibrated to likely price pathways and capacity additions through 2032.
What the report delivers (practical contents)
- Proprietary market-sizing and validated forecast models (historical 2020–2025; forecast 2026–2032) with scenario stress tests around demand, price and regulatory adoption trajectories.
- Competitive positioning maps that combine capacity, technology differentiation (thermal conductivity, fire performance, formaldehyde footprint), and route-to-market strength for global leaders and regional players.
- Go-to-market playbooks for OEMs, distributors and prominent construction contractors—covering specification economics, cost-competitive bundling, and retrofit opportunities.
- Supply-chain diagnostics and tactical procurement playbooks: raw-material sourcing options, inventory strategies under different price regimes, and contingency planning for feedstock shocks.
- M&A and partnership decision support: a transaction-screening tool that scores targets against integration risk, technology lift and regulatory-compliance upside.
- Regulatory impact matrices that translate codes and standards (new-build and renovation drivers) into demand curves for high-performance insulation products through 2032.
- Data annex: time-series market values, methodology notes, assumptions and sensitivity bounds (note: detailed segment tables and regional breakout data are available in the full report).
Competitive landscape—who matters and why
The sector is anchored by a mixture of multinational manufacturers with advanced product portfolios and a swathe of regional specialists. Our analysis focuses on technology differentiation, channel strength and strategic intent rather than headline market shares alone.
Phenolic Foam Board Market
- Kingspan Insulation (Dublin, Ireland) — commercial leader in building applications with the Kooltherm family; strong specification traction in premium construction markets and an accelerating push into adjacent thermal management applications (e.g., automotive composites).
- Asahi Kasei (Tokyo, Japan) — notable for technical-grade phenolic products marketed for high thermal and fire performance; strong R&D orientation and deep relationships with industrial OEMs where fire-rating is critical.
- Unilin / Xtratherm (Bruges, Belgium) — positions phenolic boards as part of integrated building-envelope systems; competitive on thermal performance and supply-chain reach in Europe.
- LG Hausys (Seoul, South Korea) — combines technological know-how with large-scale manufacturing capability; focus on low-conductivity and fire-resistant grades for both building and industrial segments.
- Sekisui Chemical (Tokyo, Japan) — emphasis on energy-efficiency and safety credentials; investment in product lines tailored to regulatory-driven markets.
- Chinese producers (Jinan Shengquan Group, Tenlead, Guibao, Green Foam Insulation, Clear Company) — a dynamic cluster supplying both domestic renovation demand and export markets; competitive on cost and rapidly evolving on quality and certification standards.
- Insultherm Middle East L.L.C. (Dubai, UAE) — regional specialist focused on DCD-certified products for HVAC and building use in GCC climates.
- Autex Industries Limited (Auckland, NZ) — niche player with branded low-environmental-impact products and targeted green-building positioning.
Recent strategic moves illustrate the competitive dynamic: a major chemical player launched a next-generation low-formaldehyde phenolic board in early 2025 aimed at green buildings; a North American incumbent commissioned new capacity in 2025; and a leading insulation group introduced a composite phenolic solution for automotive thermal management in mid-2025. Each development alters supplier bargaining power, specification adoption rates, and the premium available for differentiated chemistry or composite architectures.
Phenolic Foam Board Market
Market dynamics and risk vectors
- Regulatory tailwinds: The EU’s EPBD recast mandates zero-emission new buildings from 2028 and aggressive renovation targets; China’s updated residential design standards require meaningful thermal-resistance improvements in many northern zones. These requirements favor ultra-high-performance insulation systems.
- Input-cost volatility: Phenolic resin pricing is a key margin driver—benchmarks in China observed in April 2026 average around USD 1,687.91 per metric ton (FOB). Firms with integrated resin supply or advanced formulation efficiencies enjoy a measurable competitive edge.
- Product differentiation: Thermal conductivity, thickness efficiency, fire performance, formaldehyde and VOC characteristics, and composite integrations (e.g., foil facings, adhesives) determine specification economics more than basic price per square meter.
- Capacity and lead times: Recently announced capacity additions will rebalance supply in certain regions by 2026–2027; however, certification and installation channel readiness determine whether supply translates to share gains.
- ESG and end-of-life considerations: Investors and large contractors increasingly require low-emission profiles and circularity plans. Successful players combine product-level emissions reductions with take-back or recycling pathways.
Strategic playbook for 2026
- Prioritize certification and specs: Start 2026 with a focused program to secure EPBD/EU and major-market certifications. Being first-to-spec in a tightening regulatory window confers a commercial premium and accelerates uptake in renovation programs.
- Protect margins through feedstock strategy: Evaluate resin integration, long-term offtake contracts, and formulation R&D to reduce resin intensity per unit of thermal performance.
- Segmented go-to-market: Distinguish between high-margin, specification-led channels (premium new-build and automotive thermal management) and volume-driven retrofit channels; tailor pricing and service bundles accordingly.
- Capex and M&A discipline: Use our scenario model to stress-test projects under slow-adoption and fast-adoption regulatory scenarios. Pursue bolt-on acquisitions that deliver certification capability, distribution reach or formulation IP rather than low-value capacity.
- Supply-chain resilience: Build dual-sourcing for key feedstocks, regional buffer stocks, and modular production options to pivot between grades as market demand shifts.
- Commercial partnerships: Engage early with large contractors and OEMs to co-develop specification-ready systems—this reduces sales cycles and improves incumbent defensibility.
- ESG and product stewardship: Define a clear emissions metric (e.g., cradle-to-gate GWP and formaldehyde intensity) and incorporate it into procurement and marketing to meet buyer expectations and regulatory disclosure requirements.
Methodology and decision confidence
The study combines bottom-up capacity and shipment analysis, primary interviews with producers, distributors and large buyers, plus an econometric demand model calibrated to building-stock, renovation programs and industrial end-use trends. We provide alternative scenarios and sensitivity matrices (price, adoption rate, policy stringency) so executives can translate strategic choices into probabilistic outcomes. The reported CAGR of 5.6% reflects median-case assumptions; the annex contains upside and downside trajectories driven by faster regulatory adoption or delayed certification cycles.
Next steps: how to use this intelligence in 2026
- Download the full dataset and segmentation tables to run your internal P&L and capital prioritization exercises.
- Request the supplier-scorecard appendix if you are evaluating acquisition or supplier-partnership targets; it contains detailed operational and compliance scoring that is not published in the public summary.
- Engage with our consulting practice for a tailored 90-day “go-to-2026” strategy sprint—covering procurement contracts, product certification roadmaps and transaction screening.
For full segmented datasets, complete company profiles and model access (including regional, type and application breakdowns), please consult the complete Phenolic Foam Board Market report on our website. The preview above outlines the strategic signals you need to prioritize decisions in 2026; the full study supplies the granular inputs and executable templates to act on those signals.
For detailed analysis of this topic, please visit the official page: Phenolic Foam Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


