



PW Consulting: Flexographic Printing Machine Market to Expand at 9.85% CAGR (2026–2032)

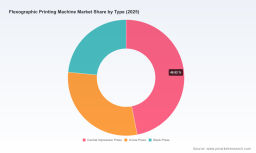
Flexographic Printing Machine Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking briefing designed to sharpen executive decision-making in 2026. This overview synthesizes our full market research for the flexographic printing machine sector (base year 2025; historical 2020–2025; forecast 2026–2032) and highlights the strategic choices that will determine competitive positioning over the next planning cycle. The full report contains the granular build‑up and proprietary models that underpin the conclusions below; this executive “trailer” reveals the implications and methodologies while withholding core segmented datapoints to preserve premium value and drive targeted inquiries.
Flexographic Printing Machine Market
Market Snapshot: Growth trajectory and structural dynamics
The flexographic printing machine market emerges from a robust growth phase in the 2020–2025 window and transitions into an accelerated investment cycle for 2026–2032. Our consolidated market model—anchored on industry-sourced revenues and field validation—indicates a compound annual growth rate (CAGR) of approximately 9.85% over the forecast horizon. From the 2025 base year, the market is projected to nearly double in aggregate value by the end of the forecast period, reflecting persistent demand for flexible packaging, labels and corrugated solutions, coupled with rising equipment replacement and digital-hybrid uptake.
Flexographic Printing Machine Market
Two structural features deserve particular attention:
Flexographic Printing Machine Market
- Consolidation of manufacturing economics: market concentration metrics show a moderate-to-high incumbent presence among top suppliers (the three‑player and five‑player concentration bands account for a meaningful share of global revenues), indicating continued strategic importance of OEM scale and integrated service networks for new orders.
- Capital intensity vs. short-run flexibility: buyer demand bifurcates between high-throughput central impression and wide-web platforms on one hand, and modular, automation-rich narrow-web/label systems on the other. This duality shapes vendor go‑to‑market plays and service revenue potential.
What the full PW Consulting report contains (practical, actionable deliverables)
We designed the study as an operator’s toolkit rather than an academic exercise. Key deliverables included in the purchase-ready report are:
- Market model and forecast dashboard (historical 2020–2025; forecast 2026–2032) with sensitivity scenarios tied to raw-material price swings and energy/regulatory pivots.
- CapEx and ROI framework for three buyer archetypes (high-volume converters, regional label houses, and startup packagers), showing payback windows under different automation and ink-technology assumptions.
- Vendor assessment matrix and scorecards: comparative profiles, product roadmaps, aftermarket capabilities, and channel footprints—scored on technology leadership, service density, and sustainability alignment.
- Supply-chain risk register with mitigations: raw-material sourcing options, strategic inventory levels, and preferred contract structures to insulate margins from resin and plate volatility.
- M&A and partnership playbook: threshold screens for targets, integration pitfalls, and value-capture levers focused on digitalization and service monetization.
- Implementation roadmaps for energy reduction, automation retrofits, and transition plans to low-VOC inks—each with estimated CapEx and operational benefits for the 24–36 month horizon.
To preserve commercial value, the downloadable report contains the full regional and application segmentation tables, price elasticities by market, and customer-level demand curves. These granular datasets remain gated in our subscription products.
Strategic implications for 2026 decisions
Executives preparing 2026 budgets must treat the following considerations as high-priority decision nodes:
- CapEx sequencing: Prioritise investments in automation and LED-UV curing where throughput and energy intensity justify transformation. Energy efficiency is no longer optional—LED-UV systems can reduce curing energy by 70–85% relative to traditional hot-air dryers, materially improving operating margins in energy-intensive jurisdictions.
- Input-cost hedging: Raw-material volatility—particularly for acrylic monomers, photopolymer plates and specialty pigments—contributes a distinct band of production cost variability. Our analysis shows supply-chain disruption can account for single-digit to low‑teens percentage swings in unit cost; hedging and multi-source strategies should be baked into procurement KPIs.
- Service-first business models: With market concentration favoring established OEMs, aftermarket services (spare parts, remote diagnostics, consumable programs) are an increasingly important margin pool. Firms that industrialize predictive maintenance and consumables RE‑ordering win recurring revenue and deeper client intimacy.
- Regulatory and sustainability compliance as competitive advantage: Transitioning to water‑based and UV-curable inks reduces VOC emissions and improves workplace safety—an important procurement filter for global CPG buyers. Companies that can demonstrate validated environmental improvements will enjoy preferable tender outcomes and easier market access in regulated regions.
- Talent and automation trade-offs: Automation reduces reliance on scarce skilled operators, but success depends on retraining and digital governance. Our case scenarios demonstrate that automation investments can reduce labor headcount needs materially while improving first‑pass yields—if accompanied by robust change management.
Competitive landscape: positioning and plays
The competitive map is heterogeneous and merits differentiated strategic responses by incumbent type.
- Large integrated OEMs (technology-first): Firms specializing in high-end central impression platforms and vertically integrated flexible-packaging lines maintain a lead for high-volume converters. These players leverage bundled offerings (press + extrusion + laminating) to lock-in long-term OEM service contracts.
- Hybrid and narrow-web innovators: Suppliers offering full‑servo narrow-web and digital-hybrid systems target conversion printers and label specialists who require quick changeovers, short runs and ink flexibility. Their value proposition centers on speed-to-market and SKU economics rather than absolute throughput.
- Modular and regional specialists: Vendors focusing on modular presses for labels and light flexible packaging capture tender opportunities in regional markets through lower capital thresholds and faster installation cycles.
Selected examples (non-exhaustive):
- OEMs with central impression and integrated flexible lines continue to win large packaging bids where output scale and consistency matter most.
- Manufacturers of narrow-web and modular presses are capitalizing on demand for short runs and personalization in labels and small-format packaging.
- Emerging suppliers from Asia and regional OEMs are increasingly competitive on price and lead times, but face differentiation challenges on service depth and sustainability credentials.
The full report includes vendor scorecards with objective metrics on R&D intensity, service network density, aftermarket revenue share, and digital capabilities—information intended to support supplier negotiations and OEM selection. To preserve the commercial value of these scorecards, we do not reproduce them here.
Recent industry signals and what they mean
Our ongoing intelligence gathering across trade shows, installations, and certifications points to three immediate takeaways:
- Market validation for automation and short-run capability: Recent installations of advanced central‑impression and Optima-class presses confirm demand for flexibility combined with automation—buyers expect fast job changeovers without sacrificing quality.
- Sustained trade-show activity: Global trade fairs remain an important channel for product launches and order capture. Vendors showcasing triple‑servo systems and live high‑speed demos are signaling confidence in near-term order flows and are investing in demonstrable operational performance.
- Geographic diversification of demand: While mature markets continue to drive premium equipment sales, there is meaningful buyer interest in tailored, cost‑effective inline and stack presses for emerging converters, supporting a layered go‑to‑market approach.
Risk matrix and mitigation playbook
Key risks identified in the study—and PW Consulting’s recommended mitigations—are:
- Input-price volatility: Use multi-sourcing, strategic inventory and indexed supplier contracts; consider price‑pass mechanisms in new supply agreements.
- Energy and regulation shocks: Accelerate transitions to LED‑UV curing and quantify TCO with energy stress tests; prioritize retrofit pathways that minimize production disruption.
- Technology obsolescence: Adopt modular architectures and upgradeable control systems; insist on open‑platform standards in procurement to preserve optionality.
- Skilled labor constraints: Invest in operator training, remote troubleshooting, and augmented‑reality onboarding to reduce dependency on local expertise.
How to use this research in your 2026 planning cycle
For boardrooms and executive teams, the research delivers three executable actions for 2026:
- Recalibrate CapEx portfolios to prioritize automation and energy-efficient curing technologies—validate with our ROI and payback scenarios for each buyer archetype.
- Rebalance supplier risk: adopt a dual-track procurement approach that protects against raw-material shocks while maintaining competitive pricing.
- Monetize services: design bundled maintenance and consumable programs to convert one‑time equipment sales into recurring annuity streams, using our aftermarket playbook templates.
Next steps and access
This briefing highlights the strategic contours we believe will shape competitive outcomes across the flexographic printing machine market through 2032. For transaction-grade strat plans, detailed vendor scorecards, and the full segmented datasets that underpin our 9.85% CAGR projection and revenue pathway from 2025 to 2032, please consult the full PW Consulting report and interactive forecast dashboard available on our publication page. The complete study contains the granular regional and application splits, price curves, and customer‑level demand maps that serious investors and strategic buyers require—information intentionally gated to ensure actionable advantage.
PW Consulting remains available to support bespoke scenario modeling, due diligence for M&A, and operational implementation planning derived from this research.
For detailed analysis of this topic, please visit the official page: Flexographic Printing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


