



PW Consulting: Mining Explosives Market to Expand at 3.2% CAGR

Mining Explosives Market: Strategic Outlook for 2026 Decision-Makers
Executive synopsis
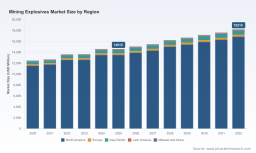
As capital allocation windows tighten and miners re-price long-life projects under new geopolitical and regulatory realities, 2026 will be a pivotal year for strategic decisions across the mining explosives value chain. Our latest market synthesis—anchored on a base year of 2025 and a forecast horizon through 2032—finds the global mining explosives market growing at a steady compound annual growth rate of 3.2%. The market expanded to roughly USD 14.6 billion in 2025 and is projected to approach USD 18.2 billion by 2032 under our central scenario. For C-suite leaders, procurement chiefs, and PE sponsors, the question is no longer whether the market will grow, but which structural forces will determine winners and losers as that growth materializes.
Mining Explosives Market
Why this report matters for 2026 strategic choices
-
Decision timing: 2026 is the inflection point for several trends—feedstock regulation, digital initiation platforms, and capital consolidation—that will shape sourcing, safety, and margin dynamics through the next CAPEX cycle.
Mining Explosives Market -
Budget prioritization: With moderating top-line growth (mid-single digits annually), profitability gains will increasingly come from supply-chain engineering, product mix optimization and technology-led productivity rather than volume alone.
Mining Explosives Market -
Risk management: The market structure is moderately concentrated—top three players control roughly half of market volumes and the top five approach two-thirds—meaning competitive moves by incumbents (M&A, plant expansions, vertical integration) can materially shift regional supply balances and price dynamics.
Macro dynamics and structural drivers
Three categories of forces will dominate 2026 planning: supply-chain resilience, regulatory tightening, and technological diffusion.
-
Supply-chain resilience: Ammonium nitrate remains the primary upstream feedstock for the dominant ANFO and emulsion products. Recent export restrictions on ammonium nitrate have created episodic volatility in feedstock availability and pricing, exposing companies that rely on single-source procurement or long-haul supply chains.
-
Regulatory tightening: National and supranational regulations—ranging from tightened precursor controls and transaction-reporting thresholds to enhanced background checks—are increasing compliance burdens. These regulations are pushing manufacturers toward more controlled production footprints and have elevated the value of compliance-ready plants and certified logistics partners.
-
Technology and safety: Electronic initiation systems, programmable detonators and innovations in delivery platforms are moving from marquee pilot projects to mine-wide deployments. These technologies improve blast precision and safety, but require integration with digital mine systems and new service models (e.g., remote delivery, predictive maintenance for initiation hardware).
Competitive landscape: capabilities that matter in 2026
The competitive battleground is bifurcating into two pathways: scale + system integration versus regional specialization with tailored service models. Both archetypes are well-represented among incumbent and emerging players.
-
Global systems integrators: Established multinationals differentiate through integrated blasting solutions, logistics networks and technology suites that bundle explosives with initiation systems and analytics. These firms leverage scale to amortize investments in R&D, compliance infrastructure and emergency response capabilities. Recent strategic moves—such as acquisitions that expand footholds in strategic markets—underscore the consolidation imperative for system integrators seeking faster access to customers and contract pipelines.
-
Regional specialists: Companies with deep local market knowledge and service-oriented business models retain advantages in jurisdictions with complex permitting, challenging logistics or preference for local content. Investments in programmable detonator production capacity and region-specific formulations have translated into defensible niches that limit direct competition from larger players.
-
Innovation focus: A discrete group has prioritized product safety and performance—developing insensitive formulations, emulsion chemistries and electric delivery mechanisms that reduce onsite handling risk and improve environmental performance. These innovations create premium product tiers and offer pathways to participate in higher-margin service contracts.
Recent strategic moves and what they signal
Market behavior in late 2025 and early 2026 offers a preview of strategic momentum we expect to accelerate:
-
Acquisitions targeted at capability and footprint expansion signal an acceleration of consolidation in priority markets.
-
Greenfield and brownfield capacity investments in programmable detonator manufacturing indicate an industry-wide shift toward electronic initiation as a mainstream offering.
-
Product launches that enable safer, automated delivery of explosives reflect a push to reduce onsite labor exposure and to link explosives delivery with broader automation agendas on mine sites.
Operational and procurement levers for 2026
Operational leaders should treat explosives not as a commodity alone but as a bundled service where application expertise, initiation systems and logistics materially affect total cost of blast. Key levers include:
-
Supply diversification and nearshoring: Reconfigure sourcing to shorten lead times and create optionality against feedstock export restrictions.
-
Supplier segmentation and contract redesign: Move from spot-buying to layered contracting—framework agreements for core supply, call-off contracts during surges, and contingency stock arrangements tied to objective performance metrics.
-
Adoption roadmaps for electronic initiation: Build phased integration plans that couple pilot deployments with operator training, safety certifications and digital interoperability testing.
-
Capex alignment: Prioritize investments that reduce lifecycle costs (blasting efficiency, reduced rework, lower environmental remediation) over simple unit-price reductions.
What the full report delivers (practical, decision-ready content)
Our report was designed to be operationally actionable for procurement, operations and corporate development teams. Highlights include:
-
Top-line and scenario-based forecasts through 2032 with sensitivity to feedstock shocks, regulatory tightening and technology adoption rates.
-
Supplier benchmarking across capability, compliance readiness, service model and technology stack—useful for shortlisting strategic suppliers and structuring RFPs.
-
Supply-chain stress tests and contingency playbooks that quantify the cost and lead-time impact of feedstock disruptions under multiple severity scenarios.
-
Regulatory matrix and compliance checklist mapped to major operating jurisdictions and precursor controls—designed for legal and HSE teams preparing 2026 licensing and audit cycles.
-
Technology adoption roadmap and integration checklist for programmable detonators and remote delivery systems, including training and change-management templates.
-
M&A and partnership opportunity scans with criteria-based ranks for bolt-on acquisitions, joint ventures and manufacturing partnerships.
Strategic implications and recommended next steps
For 2026 planning, executives should prioritize four actions:
-
Re-assess supply-chain footprints against regulatory and geopolitical scenarios and fund contingency stock and alternative-supplier trials where ROI supports reduced business interruption risk.
-
Accelerate pilots of electronic initiation and remote delivery where safety and operational continuity gains are tangible within 12–24 months.
-
Embed regulatory compliance and precursor tracking into commercial contracts and invest in traceability systems to reduce licensing friction and transactional risk.
-
Use M&A selectively to acquire specific capabilities (e.g., detonator production, specialized emulsion formulation, or regional logistics hubs) rather than broad revenue consolidation alone.
How PW Consulting can support execution
We partner with mining companies, explosives manufacturers and private investors to translate market intelligence into executable plans: supplier selection and negotiation, plant-level cost modeling, technology pilots and M&A diligence. Our deliverables combine bottom-up plant capacity and cost models with scenario analyses and implementation roadmaps designed to be used directly in board-level decision packages and procurement RFPs.
Final note — what you won’t find in this preview
This introduction sketches the strategic contours but intentionally omits the granular segmentation tables, detailed regional/application breakdowns, supplier-by-supplier financial benchmarking and full scenario-model datasets that underpin contract-level decisions. Those proprietary tables and model files are included in the full Mining Explosives Market report and are essential if you are preparing a 2026 procurement strategy, CAPEX allocation plan, or an acquisition bid evaluation.
To access the complete analysis, model files and supplier playbooks, contact PW Consulting or visit our report page for licensing options and tailored advisory engagements.
For detailed analysis of this topic, please visit the official page: Mining Explosives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


