



PW Consulting: Vitamin B12 Market to Reach USD 353.9M by 2032 at 7.4% CAGR

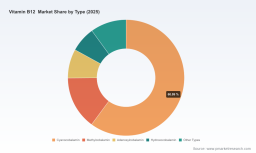
Vitamin B12 Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s senior industry analyst, I present an executive introduction to our comprehensive Vitamin B12 Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing synthesizes the study’s highest-value strategic insights for executives making sourcing, R&D, regulatory, and M&A decisions in 2026 — while deliberately withholding the granular segment tables and proprietary model outputs that drive tactical implementation. The full report contains those data-rich appendices and decision tools.
Vitamin B12 Market
Market trajectory at a glance
The global Vitamin B12 market has demonstrated steady expansion through 2020–2025, moving from USD 163.15 Million in 2020 to USD 216.80 Million in 2025. Our forecast, driven by structural demand in pharmaceuticals, nutraceuticals and animal feed, projects continued growth across 2026–2032 at a compound annual growth rate (CAGR) of 7.4%, taking the market from an estimated USD 225.25 Million in 2026 to approximately USD 353.86 Million by 2032. These aggregate figures are the foundation for scenario planning: even moderate demand-side or supply-side shocks will be amplified by the expected growth path, increasing the commercial and strategic stakes for supply security, product differentiation, and regulatory readiness.
Vitamin B12 Market
Why this study matters for 2026 corporate strategy
- Sourcing & supply resilience: The market’s concentration metrics indicate a high level of supplier dominance among a few players (CR3 ≈ 72%, CR5 ≈ 85%). For procurement and operations leaders, this concentration implies material exposure to provider outages, regulatory events, or geopolitical friction. Our study maps supplier footprints, certification status, and capacity-expansion timing so teams can build prioritized dual-sourcing strategies and near-term inventory playbooks.
- Regulatory risk & compounding practice: Recent regulatory clarifications (notably an FDA statement in April 2026 addressing compounders and specific APIs) reframe how pharmaceutical compounding and supply-demand interactions will play out. The study translates these policy shifts into practical compliance checklists and pathway maps for firms seeking to leverage compounded formulations without incurring downstream regulatory or commercial risk.
- Product & formulation strategy: Nutritional and cognitive performance claims are driving interest in active-form cobalamins. Our research provides a market-value lens on which Vitamin B12 chemotypes and finished-form strategies are likely to deliver premium pricing and lower substitution risk — critical for R&D prioritization and marketing positioning.
- Sustainability & manufacturing economics: Investments in low-carbon utilities (illustrated by recent biomass boiler deployment at an EU API site) are beginning to differentiate suppliers on total-cost and ESG credentials. For manufacturers and branded buyers, the study quantifies how such investments can alter margin dynamics and procurement risk over the forecast window.
What the report delivers (practical, operational outputs)
- Consolidated historical market sizing (2020–2025) and a fully modeled forecast (2026–2032) with scenario toggles for demand shock, regulatory tightening, and supply disruption.
- Risk heatmaps for procurement and production, including supplier concentration analysis, certification status, and time-to-contract estimates for alternative sources.
- Commercial playbooks for manufacturers and brand owners: launch sequencing, pricing ladders, premium formulation blueprints, and contract manufacturing decision templates.
- Regulatory navigator and compliance checklists keyed to the latest public guidance and common pathway fallacies for compounding, feed, and human nutrition markets.
- Investment due diligence toolkit for M&A and JV activity: valuation stress-tests, integration risk matrices, and quick-reference KPIs tied to production footprint and certification profile.
- Executive one-page strategy briefs for C-suite alignment and Board-level decision support on sourcing, CAPEX, and market entry.
Note: This summary intentionally omits the detailed regional, type, and application split tables that underpin the above deliverables. Those segmented datasets and vendor-level cost models are available exclusively in the full report.
Vitamin B12 Market
Competitive landscape — what to watch in 2026
The market structure is dominated by a handful of vertically integrated producers and specialized active-form innovators. Our competitive analysis focuses on companies that shape pricing, certification trends, and technical innovation.
- EUROAPI (Saint-Aubin-lès-Elbeuf, France) — The company operates as the only Western manufacturer producing pharmaceutical-grade Vitamin B12 (cyanocobalamin) via bio-fermentation for global pharma and feed markets. Its recent investments in on-site emissions reduction demonstrate a strategic preference for combining supply security with ESG differentiation. For buyers prioritizing regulatory transparency and low-carbon supply chains, EUROAPI represents a strategic anchor supplier.
- HealthTech BioActives (HTBA, Barcelona) — A focused supplier of active-form Vitamin B12 (notably methylcobalamin variants) targeting performance nutrition and cognitive segments. HTBA’s presence at major trade shows in 2025 and their clinical positioning for active forms underline a value-chain move towards premiumization and science-backed product claims.
- Major Chinese producers (e.g., NCPC, CSPC, Basic Nutrition, Rochem International, Freemen Nutra) — Several large-scale producers based in China continue to supply significant volumes to feed, food, and pharmaceutical customers worldwide. Their GMP certifications and export capacity make them essential partners for volume-driven buyers, though the market remains sensitive to input-cost inflation and non-tariff trade risks. One legacy data point — combined production across dominant Chinese producers exceeded 30 tons in 2020 — remains instructive today as a proxy for the scale of China’s role in global supply.
Collectively, the top three and top five suppliers capture roughly 72% and 85% of the market respectively — a concentration profile that should inform procurement strategies, long-term contracting, and contingency inventory sizing.
Recent developments and signals
- HealthTech BioActives highlighted active methylcobalamin formats and clinical research at major trade shows in 2025, signaling a push for premium nutraceutical positioning.
- North China Pharmaceutical Group’s certification upgrades for feed applications broaden market access into Europe and reduce some non-tariff barriers for feed customers.
- Regulatory clarity in early 2026 from the FDA regarding compoundable APIs adjusts how manufacturers and compounding pharmacies will source and manage inventory for certain finished products.
- Strategic manufacturing upgrades (e.g., biomass boiler installation at a major European API site) show capital allocation towards decarbonization — an emergent procurement qualifier for many multinational buyers.
Dynamics shaping the 2026 decision window
- Supply dependency and cost volatility: Heavy reliance on a small number of large-volume producers makes the market sensitive to feedstock costs, environmental controls, and export policy. Buyers should assess elasticity of demand in their product lines and model buffer strategies accordingly.
- Formulation premiumization: Active cobalamin formats are moving beyond simple nutritional replacement into performance and cognition claims. R&D and regulatory teams must coordinate early to translate clinical endpoints into permissible claims and label language.
- Regulatory & compounding interplay: The evolving regulatory landscape around compounded drug products can create short-term arbitrage opportunities but also raises compliance demands. Firms must balance speed-to-market against enforceable standards to avoid recall or enforcement risk.
- Sustainability as a commercial lever: Carbon-efficient manufacturing investments are starting to be priced into supplier selection by global brands and institutional buyers; this will reshape long-term sourcing economics and potentially justify price premiums for low-carbon supply.
Practical next steps for executives
- Run a 90-day sourcing stress-test using our supplier concentration dashboard: identify single points of failure, re-price total landed cost with alternative suppliers, and execute at least one contingency supply agreement.
- Prioritize product pipelines where active-form B12 delivers demonstrable margin uplift and regulatory defensibility; allocate small-scale clinical budgets to secure credible claims within 12–18 months.
- Complete an ESG-adjusted supplier scorecard: include emissions, certifications, and long-term capital plans as pass/fail gating criteria for preferred-supplier lists.
- Engage legal and regulatory counsel to interpret the FDA clarifications against planned compounded product strategies and ensure batch-release controls are aligned with the latest compliance expectations.
- For M&A teams: screen targets against the report’s acquisition scorecard; prioritize bolt-on assets that either expand secure API footprint or add active-form formulation IP with validated claims.
Conclusion & how to access the full intelligence
The Vitamin B12 market is entering a phase where growth amplifies both opportunity and vulnerability. Aggregate demand is on an expanding path (CAGR 7.4% across 2026–2032) and supplier concentration materially impacts risk profiles. The PW Consulting study translates these realities into executable strategies across procurement, R&D, regulatory, and corporate development.
To implement the recommendations above — including access to the segmented demand model, supplier-by-supplier cost curves, and the full regulatory playbook — please consult the full Vitamin B12 Market report. The appendices contain the granular regional, type and application splits, vendor-level assumptions, and the interactive scenario model necessary for operational execution.
For detailed analysis of this topic, please visit the official page: Vitamin B12 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


