



PW Consulting: Surgical Gloves Market to Reach USD 3,337.05M by 2032 at 7.3% CAGR

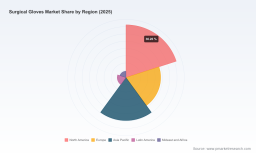
Surgical Gloves Market: Strategic Imperatives for 2026
As healthcare systems stabilize after successive waves of supply shocks and regulatory tightening, surgical gloves have re-emerged as a strategic category for procurement, manufacturing investment, and clinical risk management. PW Consulting’s latest Surgical Gloves Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro demand trends, manufacturing economics, regulatory vectors, and competitive positioning to inform boardroom decisions in 2026. This introduction highlights the strategic value of the full report while intentionally preserving core segmentation data to motivate direct access to the primary intelligence package.
Surgical Gloves Market
Market trajectory: a resilient, higher-value growth market
The surgical gloves market has demonstrated steady expansion through the 2020–2025 period and is set for sustained growth in the coming decade. On a consolidated basis, the category expanded from the low‑billion USD range at the start of the decade into a noticeably larger market by 2025. Our modeling indicates continued compound annual growth through the forecast window, underpinned by procedure volumes, higher-value nitrile adoption, and premium sterile formats. Specifically, the forecast period is characterized by a compound annual growth rate (CAGR) of 7.3%, reflecting a transition from volume-driven demand to value-driven procurement and differentiated product offerings.
Surgical Gloves Market
For executive teams, the implication is clear: the next strategic inflection point is not simply about scaling production capacity, but about upgrading capabilities that capture higher-margin segments—sterile certification, validated sterilization processes, and materials that command a premium in procurement frameworks.
Surgical Gloves Market
Why this analysis matters for 2026 decision-makers
- Investment prioritization: Capital allocation toward sterilization suites, automated donning inspection, and high-yield nitrile lines offers a faster path to margin expansion than undifferentiated capacity increases.
- Procurement optimization: Hospital systems and distributors can use the market intelligence to reframe supplier scorecards—rewarding products that demonstrably reduce staff dermatitis risk or that lower perioperative infection indicators through superior fit and tactile performance.
- Regulatory resilience: With surgical gloves regulated as medical devices in many jurisdictions (including FDA Class II expectations), companies that embed compliance into design and supply-chain validation will avoid costly market access delays.
- M&A and partnership targeting: The market’s moderate concentration creates windows for bolt-on acquisitions and capacity partnerships; targeted M&A can close capability gaps (e.g., validated sterile manufacturing, gamma/e-beam sterilization competence) faster than greenfield projects.
Core dynamics shaping the market
- Sterilization and quality assurance: Surgical gloves destined for operative settings must adhere to validated sterilization protocols and device quality systems. The interplay between ISO 13485-aligned processes and 21 CFR Part 820 requirements is a gating factor for market access in regulated markets. Firms that can demonstrate routine validation, traceability, and sterility assurance gain preferential access to institutional contracts.
- Material mix and pricing power: Hospitals have shown willingness to pay a premium for powder-free nitrile surgical gloves driven by skin-safety and durability considerations. Our market interviews and procurement analytics indicate premium acceptance in tendering behavior—creating a favorable margin environment for producers who can maintain consistent nitrile supply and quality.
- Labor and production economics: Sterile surgical glove production is inherently more labor- and capital-intensive than non-sterile formats due to cleanroom requirements, specialized sterilization equipment, and higher quality inspection demands. This structural cost base raises the stakes on process automation, workforce training, and localized sterilization partnerships to control total landed cost.
- Regulatory and reimbursement interfaces: Surgical gloves are indirectly influenced by surgical reimbursement norms; consistent billing and coding (including procedural modifiers that affect operative reimbursement) help stabilize demand forecasts for institutional buyers. Moreover, tightening biocompatibility and sterility expectations increase the bar for new entrants.
Competitive landscape — capabilities, not just capacity
The competitive field blends long-established multinational medical-device firms, large-volume commodity producers, and emerging regional players. Market concentration metrics point to a mid-level consolidation: the top few players capture meaningful share, but there remains room for agile challengers that can differentiate on quality, service, or niche product attributes.
- Established medical-device incumbents: Firms with deep clinical relationships and sterile product portfolios bring advantages in bundled purchasing and integrated supply contracts. Their surgical glove lines are typically paired with clinical training, technical support, and warranty structures that institutional buyers value.
- High-volume specialists: Large-scale glove manufacturers can leverage scale to enter tenders aggressively, but their strategic success depends on moving up the value chain into sterile, validated formats rather than relying solely on commodity volumes.
- Regional and niche innovators: Smaller manufacturers and niche brands are winning footholds by launching differentiated formulations (for example, accelerator-free nitrile options) and by offering rapid responsiveness to local procurement cycles.
Noteworthy company developments illustrate the strategic vectors in play. Product and safety recognition for differentiated surgical formulations has become a visible market signal—recent awards for hybrid micro designs underscore how performance and worker safety can translate into commercial advantage. At the same time, the launch of accelerator-free nitrile lines in large regional markets demonstrates how material innovation can create immediate adoption opportunities in skin-sensitive workforces.
For executives assessing counterparties or targets, the practical questions are: Does the company hold validated sterilization partnerships? Can it meet FDA/ISO device documentation expectations? Does it have traceable production lot control and supply-chain visibility? The full report profiles leading vendors against these criteria to support partner selection and diligence.
Risk vectors and mitigation levers
- Supply-chain volatility: Raw material swings (e.g., nitrile feedstock) and logistics disruptions remain threats. Mitigation levers include multi-sourcing, strategic feedstock hedging, and regional inventory buffering.
- Regulatory non-compliance: Entry failures or product holds due to inadequate biocompatibility or sterility documentation can be existential. Early investment in clinical and regulatory affairs capabilities pays off in accelerated approvals and reduced post-market surveillance exposure.
- Procurement shifts: Bundled contracting by large hospital systems can compress margins for vendors who lack service differentiation. Vendors should pursue clinical outcomes evidence and service-level guarantees to avoid commodity pricing traps.
- Labor and automation risk: Rising labor costs for sterile production can erode competitiveness. Automation of inspection and packaging, combined with continuous training programs, reduces per‑unit labor exposure.
What PW Consulting’s full report delivers (actionable, not academic)
The full Surgical Gloves Market report is designed for executives who must convert insight into action. Highlights include:
- Proprietary market sizing and validated forecast model covering 2020–2032 with scenario toggles for adoption mix and price elasticity.
- Regulatory and quality roadmap detailing ISO/FDA expectations, typical timelines for clearance, and a checklist for manufacturing readiness.
- Procurement playbooks for hospital systems and distributors—tender templates, scorecards weighting clinical outcomes and lifecycle cost, and negotiation levers for premium formats.
- Competitive benchmarking across manufacturing footprint, sterility validation, product portfolio breadth, and distribution reach—designed to support M&A screening and commercial partnerships.
- Operational levers for manufacturers—capex prioritization, automation targets for inspection and packaging, and guidance on mastering sterilization modalities (gamma, e-beam, EO) to reduce time-to-market.
- Price and margin sensitivity analyses that quantify the impact of material premiums (including observed premium acceptance for powder-free nitrile) and labor cost inflation on profitability.
- Risk register and mitigation playbook covering supply-chain, regulatory, and reputational risks with recommended monitoring KPIs.
How to use the study to shape 2026 strategy
For leadership teams, the study should be used to sharpen three discrete 2026 initiatives:
- Capability roadmap: Define a 24–36 month investment plan that maps sterilization and validation milestones to product-launch timelines, protecting access to high-margin sterile tenders.
- Commercial repositioning: Reprice and repackage surgical glove offerings to reflect demonstrated clinical benefits—use outcomes evidence to break free from commodity price competition.
- M&A and partnerships: Target bolt-on acquisitions that fill sterilization or regulatory capability gaps, or form strategic partnerships with regional producers to accelerate market entry with minimized capex.
Final thought: execute beyond scale
Scale remains a competitive advantage in the surgical gloves market, but our analysis shows that the most durable sources of value are capability- and evidence-based: validated sterility, material differentiation with demonstrable clinical benefits, and procurement-facing services that reduce institutional risk. The category’s forecasted growth and mid-level concentration create meaningful opportunity for companies that can align operations, regulatory rigor, and commercial proof in a coherent, capital-efficient plan.
PW Consulting’s full Surgical Gloves Market study provides the models, vendor diagnostics, and executable playbooks needed to convert opportunity into durable competitive advantage in 2026 and beyond. For access to complete segmentation, vendor scorecards, and the forecasting model, please consult the full report.
For detailed analysis of this topic, please visit the official page: Surgical Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


