



PW Consulting: MLCCs Market to Hit USD 18.91 Billion by 2032 at 5.95% CAGR

MLCCs Market 2026: Strategic Imperatives from PW Consulting’s Multilayer Ceramic Capacitors Market Preview
As companies set budgets, capex plans, and product roadmaps for 2026, Multilayer Ceramic Capacitors (MLCCs) remain at the intersection of accelerating end-market demand, supply-chain stress, and fast-evolving materials and regulatory regimes. PW Consulting’s new market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—distills the commercial and operational choices facing OEMs, component manufacturers, and investors. The objective of this preview is to communicate the study’s strategic value: to show you where competitive advantage is forming, why it will matter in 2026, and how our practical toolset converts insights into decisions. For full datasets, segmented tables, and interactive scenario models, please consult the full PW report.
Multilayer Ceramic Capacitors (MLCCs) Market
Market trajectory at a glance
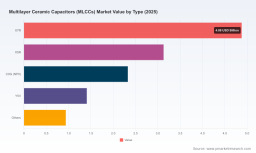
The global MLCC market has expanded steadily from the early 2020s and remains on a multi-year growth path. By the 2025 base year, the market reached an estimated USD 12.69 Billion and—under our base forecast—continues to grow at a compound annual growth rate (CAGR) of approximately 5.95% through 2032, reaching just under USD 19 Billion by the end of the forecast window. That trajectory masks meaningful variability across types, end uses, and geographies, and it underpins three practical implications for decision makers in 2026:
Multilayer Ceramic Capacitors (MLCCs) Market
- Scale matters: incumbents with deep layer-count, material-engineering, and process control capabilities will disproportionately capture high-value, high-reliability demand.
- Premiumization opportunities are expanding as electrification, power-dense computing (AI servers), and automotive safety systems drive demand for higher-voltage and tighter-tolerance MLCCs.
- Supply-side fragility and regulatory headwinds imply that stable supply and compliance will become as valuable as unit cost in procurement negotiations.
What the PW report delivers (practical, execution-focused)
This study is intentionally built to be actionable. Beyond market sizing and qualitative narrative, the report contains:
Multilayer Ceramic Capacitors (MLCCs) Market
- Scenario-based demand models that stress-test revenue and margin under alternative EV adoption, AI compute buildout, and consumer-electronics cycles;
- Supply-chain risk maps and a supplier criticality matrix that identify single-source exposures and potential choke points (including ceramic-powder and electrode-metal dependencies);
- Capex and utilization playbooks with IRR sensitivity and payback profiles for greenfield expansion, brownfield conversion, and capacity-sharing partnerships;
- Pricing playbooks tied to raw-material pass-through mechanics—enabling procurement teams to quantify the financial impact of metal-price swings, tariff regimes, and anti-dumping measures;
- M&A and JV reference playbooks that match buyer profiles (technology acquirer, capacity buyer, or regional consolidator) to prioritized targets and integration risks;
- Go-to-market frameworks for segment-focused product launches (e.g., automotive-grade high-voltage MLCCs, RF/AI-server modules) including channel and certification roadmaps.
These modules are built with downloadable Excel models and board-ready slide decks so leadership can accelerate decision cycles rather than build bespoke analyses from scratch.
Competitive dynamics: who sets the standard
The MLCC industry remains concentrated at the top: market concentration metrics indicate that the largest three suppliers control a material majority of market share, and the top five extend that dominance further—an environment that favors scale, proprietary materials know-how, and capital intensity. From a strategic perspective, the industry is bifurcating into two commercial plays:
- High-value specialization: firms investing in advanced dielectric formulations, high layer-count architectures, and tightly controlled C0G/X7R processes to capture premium automotive, high-voltage, and server-grade demand.
- Scale and breadth: manufacturers that secure wide product portfolios, cost-efficient high-volume lines, and regional manufacturing footprints to serve large consumer and industrial customers.
Representative firm strategies illuminate the direction:
- Murata Manufacturing (Japan) is extending its leadership via advanced layer-count and C0G technologies and has recently commercialized a breakthrough high-capacitance, high-voltage C0G MLCC for EV onboard chargers—an innovation that signals both technical leadership and strategic positioning in electrification powertrains.
- Samsung Electro-Mechanics (Korea) leverages in-house materials development to pursue high-capacitance automotive and AI-server segments, emphasizing vertical integration that shortens development cycles and secures material supply.
- Taiyo Yuden and TDK (Japan) prioritize high-reliability and high-voltage offerings—critical where safety certifications and thermal stability determine supplier qualification.
- Taiwanese leaders (e.g., Yageo, Walsin) have pursued portfolio breadth and selective M&A to close gaps in high-end grades, while Chinese producers (e.g., Fenghua, Chaozhou Three-Circle, Shenzhen Yuyang) continue to expand capability across the size spectrum, moving up-market into automotive and server grades.
- Component and materials specialists (e.g., Kyocera AVX, KEMET, and ceramic-powder suppliers such as Sinocera) round out the ecosystem that buyers must navigate when qualifying supply chains for mission-critical systems.
We analyze each of these players in the report with supplier scorecards covering technology roadmap, capacity cadence, geographic risk, certification breadth, and likely competitive moves through 2028.
Raw materials, regulation, and why 2026 will feel different
Recent events have elevated raw-material and regulatory dynamics from operational nuisance to strategic risk:
- Barium-titanate feedstock and electrode-metal volatility have materially increased MLCC bill-of-materials sensitivity. Notably, nickel-electrode price shocks in 2024 produced rapid BOM inflation—an effect still visible in 2025–2026 margins.
- Regulatory actions have tightened the trade environment: anti-dumping duties on select barium carbonate imports in the EU and substantial tariffs on semiconductors-related products in the United States have created new cross-border cost asymmetries and compliance burdens.
- Stricter EU safety and handling standards for barium compounds have raised operating and certification costs for producers handling these materials in-region, reinforcing the economic case for localized material processing or long-term supplier agreements with compliant producers.
Operationally, these dynamics produce three near-term responses that are visible in the market: temporary capacity adjustments for system upgrades or product-mix recalibration; accelerated investment in material-substitution R&D; and increased onshoring or nearshoring of critical upstream supply. The report unpacks the financial impact of each response and the playbook for implementing them without undermining market share.
Strategic playbook for decision-makers in 2026
Executives should align resource allocation to three parallel tracks in 2026:
- Protect supply and margin: deploy dual sourcing for critical ceramic powders and establish metal-price hedging policies tied to contract escalators. Negotiate supplier take-or-pay terms only after stress-testing against tariff and anti-dumping scenarios.
- Capture premiumization: prioritize product development and qualification for high-voltage and C0G/X7R automotive/AI-server grades where value per part and barrier to entry are growing. Consider long-lead qualification partnerships with tier-1 OEMs to lock design wins.
- Right-size capital moves: favor flexible, modular capacity investments and co-investment or toll-manufacturing arrangements where feasible. Use our capex-sensitivity templates to model utilization thresholds needed for acceptable returns under the study’s three scenario paths.
For procurement and supply-chain leaders, the report provides contract templates, a supplier-risk heat map, and step-by-step guidance to convert volatile raw-material markets into predictable sourcing outcomes. For R&D and product teams, we provide a prioritized list of dielectric and electrode development projects ranked by technical difficulty, time-to-market, and commercial upside. For corporate development teams, we identify acquisition targets and partnership archetypes aligned to each strategic track.
Signals to watch in 2026
During the coming year, management teams should watch for a handful of high-value signals that the market is re-rating vendor positioning:
- Commercial adoption timelines for recently launched high-voltage C0G parts in EV power electronics;
- Announcements of localized ceramic-powder capacity or long-term supply contracts that materially change cost curves; and
- Regulatory updates to EU import duties or US tariff enforcement that shift landed cost dynamics for imports.
These indicators will determine whether to accelerate product-specific investment or to fortify supply-chain defenses.
Why PW Consulting’s study matters for your 2026 decisions
Our report is designed to be decision-ready. It combines transparent market modeling (anchored to public and proprietary data), supplier and materials intelligence, and executable playbooks—so that teams can move from insight to executable programs within 60–120 days. If your 2026 agenda includes optimizing MLCC sourcing, accelerating product qualification for electrification or high-performance compute, or evaluating capacity investments or M&A, the PW study provides the quantified scenarios, supplier rankings, and financial models you need to justify and operationalize those choices.
Next steps
This preview outlines the directional forces and practical options. The full publication contains the segmented datasets, interactive scenario workbooks, supplier scorecards, and NPV/IRR capex templates that executives and boards use to finalize 2026 plans. For teams that require rapid activation, PW Consulting offers a short engagement to translate the report into a tailored 90‑day implementation roadmap and board package.
For detailed analysis of this topic, please visit the official page: Multilayer Ceramic Capacitors (MLCCs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


