



PW Consulting: CLT Market Set for 8.7% CAGR Through 2032

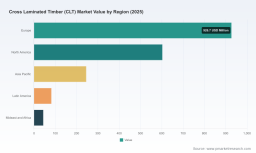
Cross Laminated Timber (CLT) Market: A Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior strategy team, we present a focused industry preview that translates rigorous market modeling into boardroom-ready guidance for 2026. Built on a 2025 base and a forward view through 2032, our research shows a market that has materially accelerated over the past five years and is projected to sustain an annualized expansion—a compound annual growth rate (CAGR) of approximately 8.7%—into the next planning cycle. Total market value rose from the low billions in 2020 to roughly USD 1.9 billion (USD Million basis) by 2025, and the model projects material expansion toward the low‑single‑digit billions by 2032. This preview outlines why those topline dynamics matter, what is changing at the industry front line, and how our full report converts those trends into executable choices for 2026.
Cross Laminated Timber (CLT) Market
Why this research matters in 2026
-
Capital allocation: Investors and industrial players face a key inflection—deciding whether to scale greenfield capacity, expand existing lines, or acquire strategic assets. With robust CAGR and clear demand momentum, timing and location of capital are the differentiators for returns.
Cross Laminated Timber (CLT) Market -
Supply-chain resilience: Lead times, feedstock availability, and labor constraints are driving re‑thinking of inventory and vertical integration strategies. Short-term disruptions can materially change operating margins in a sector where fixed costs and capital intensity are significant.
Cross Laminated Timber (CLT) Market -
Regulatory and market access: Compliance, tariffs and classification rulings are already reshaping market access and unit economics. Integrating regulatory scenarios into commercial and procurement planning is now a routine board-level requirement.
-
Go-to-market and product strategy: As architects, developers and public buyers increasingly prefer low‑carbon structural systems, CLT producers with validated performance, certifications and design partnerships capture outsized share of early high‑value projects.
Market dynamics and near-term shocks
-
Standards and certification: Performance and production conformity to ANSI/APA PRG 320 and ISO 16696‑1:2019 are non‑negotiable for mainstream adoption. Buyers increasingly demand traceable supply chains and documented compliance as preconditions for procurement.
-
Trade and policy risk: Recent policy moves—such as a proposed tariff action and customs rulings on CLT import classification—illustrate how rapid regulatory changes can re-route trade flows and re-price imports. These dynamics necessitate contingency planning for tariff scenarios and rapid reconfiguration of supply chains.
-
Feedstock and pricing pressure: Raw-material price uplifts observed since early 2025 have already altered project cost curves. The supply base is under pressure as producers face both higher input costs and competition for sustainably certified logs.
-
Capacity and labor: Several regional production nodes are operating near technical maximums, with some facilities running intensified shift patterns. That operational reality compresses lead times and fosters premiums for near-term deliveries.
What the full report delivers—practical, decision-ready content
-
Robust market-sizing and scenario engine: Bottom‑up modelling of demand drivers and a scenario matrix that stress‑tests outcomes across macro, regulatory and feedstock pathways.
-
Commercial playbooks: Developer and architect segmentation, procurement tender templates, price negotiation levers, and standardized performance clauses for buyer contracts.
-
Capex and factory optimization tools: Site selection matrices, throughput optimization, CAPEX/OPEX build‑ups, and a financial model with IRR and payback sensitivity for new lines and expansions.
-
Supply-chain blueprints: Supplier scorecards, inbound logistics playbooks, inventory hedging strategies and a short‑list of supplier mitigations for tariff and customs scenarios.
-
Regulatory compliance matrix: Actionable maps linking standards, certification pathways, permitting timelines and recommended compliance owners inside the organisation.
-
M&A and partnership screening: Criteria‑based target screening, integration checklists, and synergy estimates for bolt‑on acquisitions or strategic JV opportunities.
-
Risk heat maps and mitigation plans: Near‑term and mid‑term risk prioritization with specific mitigations that are operationally executable within 90–180 days.
-
Case studies and pilots: Annotated project examples demonstrating design-to-delivery timelines, cost delta analyses versus competing materials, and lessons learned from early mass‑timber adopters.
Competitive landscape—who to watch (and why)
The CLT market combines global forest‑products groups, specialist mass‑timber manufacturers, and regionally focused players. Scale, feedstock access and technical capability drive competitive advantage, but service, certification and architectural partnerships create defendable niches.
-
Stora Enso (Finland) — A major integrated forest products group that leverages global distribution and sustainability credentials to push CLT into urban projects across multiple geographies. Recent product launches emphasize low‑carbon performance and urban suitability.
-
KLH Massivholz (Austria) — A technology‑led European specialist with strong architectural partnerships; actively promoting CLT in taller timber structures via design collaborations.
-
Binderholz (Austria) — A vertically integrated manufacturer expanding capacity to capture incremental European demand; its recent facility openings are intended to shorten lead times and protect margin.
-
Mayr‑Melnhof Holz & HASSLACHER Group — Established regional producers that combine engineered wood portfolios with CLT offerings, focusing on integrated product suites for builders.
-
Structurlam & Element 5 (Canada) — North American leaders that benefit from early market development and a strong project pipeline in modular and mid‑rise construction.
-
SmartLam, Mercer Mass Timber, Sterling Structural, Timberlab, Freres Engineered Wood, Timberlab (US) — A cohort of US players accelerating factory investments, expanding glulam/CLT co‑production, and pursuing local demand where import exposure is sensitive to tariffs and customs rulings.
-
XLam (Australia) — Serving Oceania and export markets with a product focus adapted to regional timber species and contractor practices.
Notable recent moves underscore the competitive shifts: new greenfield facilities and expansions are being brought online to increase output capacity; product innovation is being marketed to urban developers; and strategic partnerships with architectural firms are being deployed to secure high‑visibility projects. These actions are narrowing the yardstick between scale benefits and specialist, design‑led advantages.
Market structure implications
-
Consolidation and scale: The market shows measurable concentration at the top end—enough to reward scale economies while leaving room for regional and capability‑focused challengers. Buyers will find competitive provider options but should expect price and lead‑time differentiation by supplier.
-
Service and specification as battlegrounds: As base technical requirements converge around shared standards, differentiation moves to speed-to-site, design support, warranty constructs, and lifecycle carbon reporting.
Strategic playbook for executives in 2026
-
Adopt a dual‑track capacity plan: Combine incremental capacity to meet contracted near‑term demand with modular expansion options triggered by clear market signals to avoid stranded investment.
-
De‑risk feedstock: Pursue backward integration or long‑term offtake agreements with forest owners and sawmills; prioritize certified sources to preserve access to sustainability‑sensitive buyers.
-
Hedge regulatory risk: Build tariff‑scenario playbooks and flexible procurement routes (local production vs. imports) so commercial bids remain viable across policy outcomes.
-
Embed standards early: Allocate product and engineering resources to meet ANSI/ISO performance standards and incorporate compliance into customer proposals as a selling point.
-
Win through partnerships: Invest in architectural partnerships and developer alliances to lock design pipelines and obtain reference projects that accelerate adoption.
-
Prioritize operational excellence: Optimize factory layouts, invest in automation where marginal cost savings exceed implementation risk, and design staffing models that mitigate regional labor intensity.
-
Use M&A selectively: Target regional facilities or technical capabilities that close gaps in distribution, certification, or project delivery rather than chasing headline capacity numbers alone.
Next steps & where to get the full intelligence
This preview intentionally surfaces the principal strategic inflection points without publishing the granular sub‑segment datasets, regional share tables or the detailed supplier scorecards that are central to execution. For procurement templates, facility optimization models, the full scenario engine, and a complete list of company benchmarking metrics that support executable 90‑ to 180‑day plans, access the comprehensive PW Consulting CLT Market report and our advisory engagement options. The full deliverable contains the primary datasets, financial models, and bespoke workshops designed to de‑risk capital allocation and sharpen competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Cross Laminated Timber (CLT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


