



PW Consulting: Hyperspectral Imaging Market to Hit USD 344.8M by 2032; 15.62% CAGR

Hyperspectral Imaging Market: Strategic Imperatives for 2026 Decision-Makers
As hyperspectral imaging (HSI) moves from niche research labs into mainstream industrial, defense, and clinical workflows, executives face a pivotal strategic choice: lead integration and capture disproportionate value, or remain a downstream consumer of commoditized capabilities. PW Consulting’s latest market study—anchored to a 2025 base year and a seven-year forecast horizon (2026–2032)—translates the technical complexity of HSI into decision-ready frameworks for 2026 planning cycles.
Hyperspectral Imaging Market
Why 2026 Is a Strategic Inflection Point
The HSI market has demonstrated sustained momentum over the past half-decade, growing from the low hundreds of USD Million in 2020 to an estimated USD 215.0 Million in 2025. Looking forward, our model forecasts continued acceleration underpinned by integration across food & agriculture, healthcare, defense and industrial inspection, yielding a 2026–2032 compound annual growth rate (CAGR) of approximately 15.62% and an expected market size approaching USD 345 Million by 2032.
Hyperspectral Imaging Market
That trajectory reflects several converging forces: maturing sensor technology (including on-chip and snapshot architectures), increasing computational capability at the edge, higher regulatory acceptance in clinical contexts, and expanding operational use-cases where spectral discrimination materially improves yield, safety, or detection performance. For corporate strategy teams, those dynamics translate into three practical imperatives for 2026: prioritize platform selection, future-proof data architectures, and align go-to-market models with procurement cycles that are shortening in fast-adopting verticals.
Hyperspectral Imaging Market
What the Numbers Mean — Without Giving Everything Away
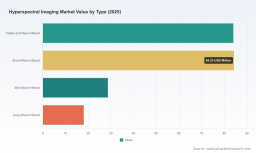
High-level market sizing and growth rates tell a clear story: HSI is scaling beyond specialist deployments. Yet, consistent with our “trailer” approach, this overview intentionally refrains from granular regional, type, or application revenue splits that are reserved for the full report. This is purposeful: the headline figures should inform your strategic posture, while the detailed segmentation and interactive dashboards in the full study are what teams will use to build investment cases, procurement scopes, and M&A models.
-
Decide by platform, not by vendor feature lists: the next 18 months will be won by firms that evaluate imaging platforms in the context of their end-to-end operational stack—sensors, optics, on-device preprocessing, connectivity, and analytics.
-
Budget for data-centric engineering: HSI systems generate very large, high-dimensional datasets that demand on-the-fly compression, intelligent frame selection, and domain-aware models to avoid prohibitive cloud and operational costs.
-
Monitor standards and regulatory windows: 2024–2026 saw decisive standardization activity that will influence procurement specifications and qualification timelines.
Technology and Deployment Dynamics
HSI is not a single technology; it is an architectural decision-space where spectral range, temporal resolution, spatial scale, and platform (bench, UAV, airborne, handheld, or on-line industrial) must be traded off against cost and operational constraints. Recent industry observations reinforce two pragmatic constraints:
-
Data volume and compute: hyperspectral captures create orders of magnitude more data than RGB imaging. Practical industrial adoption requires efficient on-the-fly compression, smart region-of-interest selection, and edge inferencing to keep latency and operating costs manageable.
-
Temporal resolution vs. scanning mechanisms: mechanical scanning approaches provide high spectral fidelity but can struggle with dynamic scenes. Snapshot/snapshot-hybrid architectures are improving, but buyers must evaluate whether a system’s temporal profile aligns with their process speeds.
On the standards and regulatory front, recent developments materially change the procurement landscape. Noteworthy items include IEEE’s 4001-2025 performance characteristics for HSI cameras and the U.S. FDA’s de novo guidance for HSI-based tissue assessment, both of which reduce uncertainty for healthcare adopters. ISO guidance on imaging safety (e.g., ISO 15004-2) further clarifies device risk profiles. These moves accelerate the time-to-deploy for regulated applications while raising the bar for documentation and traceable performance testing.
Competitive Landscape — Strategic Profiles You Need to Watch
The HSI industry is characterized by a mix of specialized sensor OEMs, system integrators, component suppliers, and research-driven platform providers. Market concentration indicates a moderately fragmented field with the top three firms controlling roughly 40% of identifiable market share and the top five around 52%—a structure that encourages both partnerships and opportunistic consolidation.
-
Headwall Photonics (Bolton, MA): A North American systems leader focused on industrial inspection and remote sensing workflows. Strengths include integrated optics and application-focused turnkey solutions, positioning Headwall well for customers seeking rapid integration and vendor accountability.
-
Specim (Spectral Imaging Ltd.) (Oulu, Finland): A long-standing player across visible-to-thermal ranges, Specim’s catalog spans cameras to full systems, giving it reach into research and high-end industrial markets where spectral fidelity is mission-critical.
-
Resonon (Nashua, NH): Known for accessible benchtop to airborne platforms, Resonon competes on ease-of-deployment and vertical-tailored solutions—attractive to organizations moving from pilots to scaled rollouts.
-
Cubert GmbH (Ulm, Germany): Focused on snapshot cameras enabling video-rate capture, Cubert is winning early adoption in UAV and defense use-cases where motion capture and real-time decisioning are essential. Recent product integrations targeting common drone platforms signal a push into operational rapid-response markets.
-
BaySpec (San Jose, CA) and Photon Etc (Montreal): Both offer VIS-NIR-SWIR capabilities with emphasis on industrial sorting and life-sciences respectively; strategic differentiation rests on optics, wavelength coverage, and software toolchains.
-
Norsk Elektro Optikk (HySpex) and Telops : Specialists in high-performance airborne and infrared systems—positions that align with defense, environmental monitoring, and mineral exploration clients who require high spectral and radiometric fidelity. Telops’ recent product rollouts and anniversary product strategies reinforce its R&D-led posture.
-
Innovators and component enablers such as XIMEA, Corning, IMEC, Surface Optics, and startups like Hinalea and HyperMed provide critical enablers—compact sensors, optics, on-chip approaches, and clinical AI stacks. Their roles are increasingly pivotal as integrators seek validated sub-systems to speed time-to-market.
Competitive dynamics are transactional in some segments (commoditized imaging modules, OEM components) and relationship-driven in others (defense contracts, clinical approvals). For 2026, expect alliances that bundle optics, sensors, and analytics into application-specific deliveries, as well as M&A activity focused on consolidating analytics IP and edge-compute capabilities.
What Our Full Report Delivers (Practical, Actionable)
The PW Consulting full Hyperspectral Imaging Market study is structured as a decision toolkit for executives, product leaders, and M&A teams. Key deliverables include:
-
Robust market model and interactive scenarios (2020–2032) with sensitivity controls for adoption rate, price erosion, and platform mix assumptions;
-
Vendor evaluation matrix and procurement playbook that translate technical specs into TCO, MTTR, and deployment risk scores;
-
Use-case ROI templates and data-architecture blueprints to estimate storage, compute, and labelling costs for pilot vs. scale phases;
-
Regulatory and standards impact assessment with recommended compliance roadmaps for clinical and defense procurements;
-
Go-to-market and partnership frameworks tailored to five distinct buyer personas (R&D labs, plant operations, UAV service providers, clinical procurement, defense integrators);
-
A curated list of due-diligence questions for potential investments or acquisitions, and four anonymized case studies showcasing scaled deployments and lessons learned.
To protect the commercial value of our segment-level intelligence and granular vendor benchmarking, the full breakdowns (including regional, type, and application splits) are accessible only in the paid study and interactive portal. This article provides the strategic map; the report supplies the navigational instruments.
Six Tactical Recommendations for 2026 Planning
-
Prioritize pilot projects that pair a narrow operational KPI with a clearly isolated ROI path—e.g., a single production line or a defined clinical indication.
-
Budget for edge compute and data ops up front. Plan for incremental cost curves driven by data retention and model retraining.
-
Use standards as a competitive advantage—obtain verifiable performance claims aligned to IEEE 4001-2025 or equivalent to accelerate procurement qualification.
-
Pursue strategic OEM relationships for optics and sensor modules to shorten integration timelines and control supply risk.
-
Structure commercial offers around outcomes (defect reduction, diagnostic accuracy, false alarm reduction) rather than purely hardware specifications.
-
Monitor consolidation signals—target acquisitions that add edge analytics or domain-specific labelled datasets to leapfrog incumbents.
Next Steps
If your 2026 planning cycle includes HSI initiatives—whether to pilot, scale, or make strategic acquisitions—PW Consulting can accelerate decision-making with tailored briefings using the full dataset and vendor benchmarking tools. Our report converts the market’s rapid growth (15.62% forecast CAGR through 2032) into operational roadmaps and investment theses designed for board-level scrutiny.
For access to the full market model, interactive segmentation dashboards, and vendor scorecards, request PW Consulting’s Hyperspectral Imaging Market study and schedule a strategic briefing. The roadmap you build now will define whether your organization is a leader in next‑generation spectral sensing or a late adopter of a now-mature technology domain.
For detailed analysis of this topic, please visit the official page: Hyperspectral Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


