



PW Consulting: Peptide Therapeutics to Reach $342.3M by 2032 at 8.73% CAGR

Peptide Therapeutics Market 2026: Strategic Preview for Decision-Makers
As peptide therapeutics transition from niche specialty drugs into a mainstream therapeutic class, 2026 will be a pivotal year for corporate strategy. This preview summarizes the strategic value of PW Consulting’s full Peptide Therapeutics Market study for executives, investors, and operational leaders preparing decisions that will shape portfolios, supply chains, and manufacturing footprints over the next business cycle.
Peptide Therapeutics Market
Why this research matters for 2026 decisions
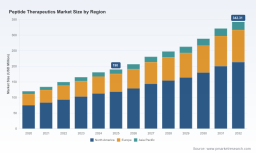
Peptide therapeutics now sit at the intersection of rapid clinical innovation and acute manufacturing constraints. The market has expanded materially over the past half-decade — rising from approximately USD 120 million in 2020 to about USD 190 million in 2025 — and is forecast to continue growing at a compound annual growth rate of 8.73% through our 2026–2032 forecast window. By 2032, our baseline projection places the market substantially higher than today’s base, underscoring durable demand drivers and recurring commercial opportunities.
Peptide Therapeutics Market
That growth trajectory creates both opportunity and complexity. Strategic choices made in 2026 — about capacity, partnerships, pricing, and regulatory exposure — will determine whether organizations capture disproportionate upside or become vulnerable to supply-side shocks and payer pressure. PW Consulting’s study synthesizes market sizing, trend analysis, and operational playbooks into an actionable framework for those choices.
Peptide Therapeutics Market
Core takeaways: what we found and what it implies
- Growth is broad-based but manufacturing-constrained. Strong clinical momentum (including multiple GLP‑1 approvals through 2025) is expanding demand for complex peptides. Our topline forecast shows sustained double-digit expansion relative to prior decades when normalized to the current base, yet availability of cGMP capacity remains the primary limiter on commercialization timelines.
- Consolidation and selective vertical integration are accelerating. Market concentration metrics indicate a mid-to-high level of concentration among leading suppliers, and recent M&A and capacity moves reflect a strategic push to secure API throughput and integrated supply chains.
- Payer dynamics and pricing tension are real for generics. Branded GLP‑1 therapies have reset pricing expectations; this is creating unusual reimbursement dynamics where generic entrants face constrained access despite potentially lower unit costs.
- Regulatory and inspection dynamics are reshaping localization strategies. Intensified FDA/EMA inspections of foreign facilities are contributing to reshuffles in sourcing strategies and renewed incentives for domestic or near-shore capacity expansion.
Competitive landscape — who matters and why
The competitive topology includes global CDMOs, regional specialists, equipment vendors, and vertically integrated manufacturers. PW Consulting’s research profiles the leading players shaping supply availability and the economics of peptide production.
- Bachem AG (Bubendorf, Switzerland) — A leading CDMO offering cGMP peptide synthesis and API manufacturing. Recent investments include a state-of-the-art synthesis facility launched in North America in 2025, signaling a strategic bet on near‑market capacity for U.S.-based clients. For buyers, Bachem is a go-to option for scaling clinical candidates to commercial supply with established regulatory track records.
- PolyPeptide Group AG (Baar, Switzerland) — Specializes in SPPS and large-scale GMP manufacturing. Its global footprint and SPPS expertise make it a likely partner for clients seeking robust scale-up pathways.
- CordenPharma (Stein, Switzerland) — A full-service CDMO with integrated SPPS/LPPS capability and sterile injectable competence. Strategic activity has intensified: a 2025 multi-year partnership to support integrated GLP‑1/GIP manufacturing and a 2026 acquisition expanded its peptide API capacity and market reach. These moves illustrate a deliberate consolidation strategy to capture end-to-end value.
- Equipment and niche manufacturers — CSBio and other technology-focused firms supply the automated synthesizers and process equipment that underpin high-throughput peptide production. Their innovations materially impact unit economics and scalability.
- Regionally influential producers — A cluster of Asia‑based manufacturers has scaled rapidly, securing large-volume GLP‑1 manufacturing agreements in recent years. These suppliers are central to global supply balancing but are also subject to the inspection and localization pressures noted above.
Overall, the top three suppliers account for a significant portion of market share, and the top five increase that share materially, a fact that should shape competitive assessment, sourcing risk, and M&A strategies.
Recent developments that change the 2026 playbook
- CordenPharma’s acquisition of AmbioPharm (May 2026) — accelerates capacity consolidation and highlights acquisitive routes to immediate scale.
- Bachem’s Pennsylvania facility (Aug 2025) — an example of how leading CDMOs are de‑risking supply by investing in regional capacity.
- Commercial GLP‑1 manufacturing agreements in 2025 — including large-scale commitments by Asian manufacturers — show where production volume is being concentrated and where supply-side risk is clustering.
- CapEx boom in 2024–2025 — multiple CDMOs announced investments exceeding USD 100 million to expand SPPS and hybrid capacities, reflecting the capital-intensity required to meaningfully expand throughput.
- Regulatory inspections and payer pushback — combined, these forces are driving re-evaluation of sourcing strategies and pricing expectations for both branded and generic peptides.
What the full PW Consulting report contains (actionable, not academic)
Our full study is structured to be directly operational for 2026 decision cycles. Key deliverables include:
- Top‑down and bottom‑up market sizing with a transparent methodology and scenario variants for conservative, base, and upside cases.
- Demand-driver analysis by therapeutic class and pipeline mapping, including clinical-stage peptide candidates likely to enter commercialization by 2032.
- Supply-side mapping: validated CDMO capability maps, equipment vendor assessments, raw‑material supply chains, and lead-time benchmarks.
- Competitive benchmarking: financial profiles, capacity footprints, strategic initiatives, and M&A valuation precedents for active players.
- Commercial playbooks: contracting templates, inventory and buffer strategies, and price/ reimbursement levers tailored for peptide categories (innovative vs. generic).
- Regulatory risk matrices and inspection impact scenarios with recommended remediation and sourcing hedges.
- CapEx decision support: investment sizing, payback models, and greenfield vs. brownfield tradeoffs for new manufacturing nodes.
- Rapid-response scenario planning and a one-page “2026 decision checklist” for executive use.
To preserve competitive value for subscribers and clients — and consistent with the “trailer” principle — the report intentionally reserves granular regional, application, and type-level splits behind the full analysis. If your 2026 decisions depend on those segment-level assumptions, the full dataset and model are available through PW Consulting.
Strategic recommendations for 2026
- Secure long‑dated capacity contracts now. With GMP capacity still the gating constraint, companies with commercial or late-stage assets should prioritize long-term offtake agreements or equity/capacity partnerships with established CDMOs.
- Validate dual‑sourcing and near‑shoring roadmaps. Regulatory inspection volatility and geopolitical risk mean contingency sourcing and near‑market capacity will be differentiators in speed-to-market for 2026 launches.
- Consider targeted M&A or JV to shortcut capacity gaps. The recent wave of acquisitions indicates buying capacity and capabilities is now often faster than greenfield buildouts — especially for firms prioritizing time to market.
- Reassess pricing and market access playbooks for generics. The reimbursement environment is not a simple arbitrage between branded and generic cost. Payer resistance to lower‑value generics requires nuanced access strategies, including indication-based contracting and outcome-linked pricing where possible.
- Invest in process innovation and automation. Capital deployed into improved SPPS/LPPS process efficiency and automation reduces unit costs and insulates margins against raw‑material swings.
- Adopt supply‑chain stress tests as a routine KPI. Model scenarios for raw material shortages, inspection shutdowns, and demand surges; incorporate those outcomes into inventory, insurance, and commercial continuity plans.
How PW Consulting’s analysis supports board‑level decisions
Board and C-suite agendas in 2026 will center on three questions: (1) can we bring our peptide asset to market on acceptable timelines; (2) how do we secure reliable, quality supply at predictable economics; and (3) should we build, buy, or partner for manufacturing? Our research translates market projections, competitive behavior, regulatory trends, and operational levers into a short set of measurable choices — e.g., contract lengths to target, inventory cover to carry, capex thresholds to approve, and M&A value bands — enabling boards to make defensible, time-bound decisions.
Next steps and how to use this preview
This preview is designed to map the strategic landscape and provokes the targeted strategic questions you must answer in 2026. To operationalize decisions — secure suppliers, commit capex, or pursue M&A — you will need the full PW Consulting model, supplier scorecards, and the scenario stress-tests we reserve for subscribers.
Contact PW Consulting for a briefing tailored to your role (commercial, manufacturing, regulatory, or investment) and for access to the downloadable dataset and proprietary segmentation tables. The full report provides the granular inputs and downloadable forecast model required to substantiate board approvals and investment memoranda.
Conclusion
The peptide therapeutics market presents a clear growth trajectory supported by strong clinical momentum and structural demand. However, the path to commercial scale is governed by manufacturing capacity, regulatory scrutiny, and complex reimbursement dynamics. Organizations that align strategic choices in 2026 — around capacity, partnerships, and pricing strategy — will convert today’s structural tailwinds into durable competitive advantage. PW Consulting’s full Peptide Therapeutics Market study provides the data, diagnostics, and decision tools to do exactly that.
For detailed analysis of this topic, please visit the official page: Peptide Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


