



Smart Door Lock Market: 19.7% CAGR to USD 12.32B by 2032 | PW Consulting

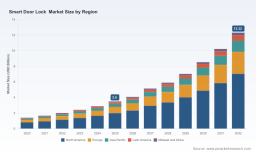
Smart Door Lock Market — Strategic Preview for 2026 Decision-Makers
As organizations plan product roadmaps, channel strategies, and M&A agendas for 2026, the smart door lock market has matured from niche connected hardware into a cross‑disciplinary platform business — combining access control, identity, networking stacks, firmware security, and recurring services. PW Consulting’s latest market study models this transition quantitatively and prescriptively: a USD 3.5 Billion market in 2025 and a steep multi‑year trajectory driven by hardware replacement, retrofit upgrades, and platform consolidation. Our baseline forecasts show the market expanding at a compound annual growth rate of 19.7% through 2032, reaching a projected market size north of USD 12 Billion by the end of the forecast horizon.
Smart Door Lock Market
Why this research matters for 2026 decision cycles
-
High‑velocity growth: With near‑20% CAGR from 2026, investment timing matters. Product launches, standards compliance, and channel commitments made in 2026 will compound into outsized revenue and share positions across the 2026–2032 window.
Smart Door Lock Market -
Standards and interoperability are reshaping value capture: The Matter ecosystem has reached broad verification status and new credential standards (e.g., the Aliro smartphone/wearable credential framework) are being introduced in early 2026. These shape platform lock‑in and provide a migration path for incumbents and new entrants alike.
Smart Door Lock Market -
Regulatory and localization pressure is intensifying: Certification (FCC, UL) and jurisdictional digital product rules (notably the EU’s digital compliance requirements and India’s localization policies) are now gating studies in product roadmaps and go‑to‑market execution.
-
Monetization is moving beyond one‑time device sales to recurring services: Firmware updates, credential lifecycle management, multi‑dwelling access, and integrated security subscriptions materially change unit economics and buyer lifecycle value.
What the PW Consulting report delivers — practical outputs for executives
-
Robust market sizing and forward scenarios: audited historicals (2020–2025), a 2026 base, and three scenario pathways to 2032 that stress test adoption, pricing, and channel shifts.
-
Actionable go‑to‑market blueprints by channel archetype: DIY retail, pro‑installer distribution, property‑level (multifamily and commercial) procurement, and critical‑infrastructure procurement approaches.
-
Technology adoption roadmap: timelines and decision criteria for Matter, Thread, UWB, Bluetooth, Wi‑Fi, biometric modalities, and embedded video — with recommended product‑feature prioritization across buyer personas.
-
Regulatory and certification playbook: compliance checklists, firmware/data‑handling obligations across major jurisdictions, and a costed certification timeline for 2026 launches.
-
Vendor landscape and competitive fit analyses: strategic profiles, capability matrices, go‑to‑market comparisons, and M&A candidate shortlists with integration risk scoring.
-
Commercial models and price decks: sell‑in / sell‑through margins by route to market, subscription packaging prototypes, and lifetime value (LTV) vs. customer acquisition cost (CAC) simulations.
-
Operational diagnostics: supply chain resilience assessment, localization cost curves, and a recommended three‑year sourcing roadmap to mitigate tariff and logistics shocks.
-
Management dashboards: executive KPIs, adoption triggers, and investor‑grade slide packs for Board and fundraising use.
Market dynamics to factor into 2026 strategy
-
Standards convergence and credentialing: Matter’s verified status materially reduces integration friction between ecosystems; simultaneously, the Connectivity Standards Alliance’s Aliro initiative (launched Q1 2026) establishes a unified smartphone and wearable credential model. Product teams must choose whether to be early adopters (first‑mover interoperability benefits) or rapid integrators (minimizing technical debt).
-
Certification and compliance as go‑to‑market gatekeepers: FCC wireless certification and UL safety standards remain mandatory; EU digital product and privacy obligations impose firmware/data governance costs; India’s Make‑in‑India push pressures localization and sourcing decisions for vendors targeting that market.
-
Shift from hardware differentiation to platform value: As core connectivity and biometric pipelines become table stakes, differentiation increasingly comes from software ecosystems, partner marketplaces, and service bundles (e.g., guest management, rental integrations, analytics, and warranty subscriptions).
-
Channel volatility and customer acquisition dynamics: Retail and e‑commerce remain important for consumer awareness, but property and enterprise procurement channels are consolidating purchasing volumes. That affects pricing strategies and distribution economics.
Competitive landscape — strategic positioning of core vendors
The vendor map is populated by large access incumbents that combine scale and distribution, insurgent product specialists focused on retrofit and rental markets, and a cohort of platform players bringing video, biometrics, and identity services together. The market is not yet concentrated: the largest firms collectively occupy a minority share of global revenue, leaving substantive room for tactical share gains through product differentiation, channel execution, or M&A.
-
ASSA ABLOY (Yale, Kwikset, August): An integrated incumbent with a multi‑brand strategy. Strengths include channel breadth, proven retrofit propositions, and a rapid path to Matter and Wi‑Fi support across product lines. Strategic choices center on harmonizing firmware and services across brands without diluting channel incentives.
-
Allegion (Schlage): Strong North American pro and retrofit positioning. Recent products emphasize easy Wi‑Fi connectivity and installer‑friendly features. The key vector is translating installer relationships into managed services contracts.
-
Specialist challengers (August, Kwikset Halo/Aura, igloohome, Ultraloq, Nuki, Level, Lockly, DOOR): These players are advancing niche differentiators — renter‑friendly retrofits, algorithmic PIN systems, biometric innovation, invisible‑design locks, or integrated door‑to‑cloud video. They are prime targets for partnership or acquisition, depending on strategic ambition.
-
Consumer electronics entrants (Eufy, Aqara): These firms bring aggressive cost and featuresets (video, palm‑vein, UWB) and tight ecosystem integration. They alter pricing dynamics in markets where brand and SI integration matter less.
Recent market moves to watch: Kwikset launched its Aura Reach Matter/Bluetooth enabled deadbolt in January 2026, the Connectivity Standards Alliance released the Aliro credentialing standard in January 2026, and Nuki announced an expanded Smart Module for late‑2026 connectivity expansion. These are immediate strategic signals — incumbents are racing to lock in interoperability while challengers push product modularity.
Strategic implications — recommendations for executives planning in 2026
-
Prioritize standards alignment early: Allocate roadmap capacity and certification budget to Matter and emerging credential standards now. Being fully interoperable reduces friction for enterprise procurement and accelerates channel acceptance.
-
Design for layered monetization: Combine device ASP optimization with recurring revenue models (cloud services, guest credentials, maintenance). Run live pricing experiments in pilot geographies to refine LTV/CAC assumptions before large rollouts.
-
Channel and route‑to‑market optimization: Map your product SKUs to channel archetypes (DIY, pro, property), and tailor packaging, warranty, and installation services accordingly. Consider exclusive SKUs or co‑branded solutions with key retail or property management partners.
-
M&A and partnership playbook: Target acquisitions that fill platform gaps — credentialing, biometric IP, cloud backends, or property management integrations. Prioritize targets with sticky revenue and minimal integration risk.
-
Localization and supply chain resilience: For markets with localization pressure, start dual‑sourcing and on‑shoring plans in 2026 to avoid regulatory bottlenecks and tariff exposure.
-
Security and privacy as competitive advantage: Build and certify robust OTA update processes, secure key provisioning, and transparent data‑handling practices to reassure enterprise and consumer buyers under tightening regulation.
How to use this study in your 2026 planning rhythm
-
Board and investment committees: Use the scenario suite to stress test revenue plans, valuation multiples, and M&A timing across the 2026–2032 period.
-
Product leadership: Leverage feature prioritization matrices and tech roadmaps to set development sprints and certification milestones through 2026.
-
Commercial teams: Adopt the channel playbooks and pricing decks to negotiate distribution agreements and pilot programs with property managers and retailers.
-
Corporate development: Use our vendor heat‑maps and integration risk scores to build a shortlist of acquisition and partnership targets aligned to your strategic gaps.
Final note — why PW Consulting’s study is a 2026 strategic lever
Our research blends audited market histories, a rigorous forecast model (anchored on a 2025 base), and scenario‑driven strategic prescriptions. The market’s structural shift — from point‑hardware sales to connected platform economics — creates distinct windows of opportunity. What separates successful movers in 2026 will be timely interoperability decisions, defensible recurring‑revenue models, and jurisdictional compliance strategies that remove friction from international scale‑up.
To preserve the executive summary as a “trailer,” we have intentionally withheld granular regional and application segment tables, detailed vendor market shares, and the full set of financial models from this preview. The complete report contains the raw datasets, downloadable model workbooks, regional and application revenue splits, and vendor share tables that support the recommendations above — essential inputs for board briefing packs, M&A diligence, and GTM execution plans.
Contact PW Consulting to obtain full access to the Smart Door Lock Market report, model files, and a tailored workshop that maps these insights into your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Smart Door Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


