



PW Consulting: Nylon String Trimmer Line Market to Reach USD 251.4 Million by 2032 at 5.8% CAGR

Nylon String Trimmer Line Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As agricultural operators, outdoor equipment OEMs, and aftermarket suppliers plan 2026 budgets and product roadmaps, understanding the macro trajectory of the nylon string trimmer line market is now a tactical necessity. PW Consulting’s latest study (base year 2025; forecast 2026–2032) synthesizes primary supplier intelligence, material-cost modelling, regulatory scanning, and channel economics to deliver decision-grade insights. In short: the market has demonstrated steady expansion from the early 2020s and is forecast to continue growing at a mid-single-digit compound annual growth rate (CAGR) — 5.8% over the 2026–2032 forecast window — with total market value rising from approximately USD 170.0 Million in 2025 to roughly USD 251.4 Million by 2032. This trajectory creates both structural opportunities and timing-specific risks for producers, distributors, and equipment OEMs.
Nylon String Trimmer Line Market
Why this matters for 2026 planning
-
Budget allocation and capex prioritization: A predictable, positive growth profile allows procurement and manufacturing planners to justify incremental capacity investments — but only if those investments are targeted at the right product architectures and geographies.
Nylon String Trimmer Line Market -
Product strategy and portfolio optimization: The market’s growth supports continuing product diversification (e.g., noise-reducing formulations, multi-sided profiles, abrasion‑resistant compounds), but margins will hinge on material sourcing and cost control.
Nylon String Trimmer Line Market -
M&A and partnership windows: Market concentration metrics indicate significant scale advantages among leading producers; 2026 presents a favorable environment for bolt-on acquisitions or supply alliances that can accelerate market access without building greenfield capacity.
Market trajectory and structural drivers
From an empirical standpoint, the market rose steadily through the early 2020s and reached an estimated USD 170.0 Million in 2025. Our scenarios project continued expansion to just over USD 250 Million by 2032 at a 5.8% CAGR, reflecting a combination of steady replacement demand, incremental professionalization of grounds and turf services, and broader adoption of battery-powered trimming equipment which sustains aftermarket line sales. Key structural drivers include raw material pricing dynamics (nylon polymer constitutes the primary material input), equipment replacement cycles supported by government machinery reimbursement programs in several jurisdictions, and the steady enforcement—or absence—of new chemical or water-use restrictions relevant to trimmer line use.
Regulatory and operating context — what’s stable, what to watch
-
No immediate regulatory shocks: As of 2026 there are no targeted water-usage regulations or specific chemical bans directly affecting nylon trimmer line materials. ISO standards for monofilament quality remain unchanged, meaning no new certification barriers for market participation in the near term.
-
Material cost sensitivity: Nylon polymer pricing is the primary cost lever for manufacturers. Volatility in polymer markets will directly affect gross margins unless mitigated with forward purchasing, hedging, or material-substitution strategies.
-
Labor and field application realities: Deployment and maintenance in commercial agricultural settings require specialized labor skills for optimal efficiency, an operational factor that influences aftermarket product design (ease-of-feed, reduced maintenance) and service contracts.
-
Policy tailwinds: Certain government reimbursement schemes for agricultural machinery reduce total cost of ownership for commercial fleets and can accelerate replacement cycles for trimmer line-compatible heads and accessories.
Competitive landscape — where market power sits
The market shows meaningful concentration: the top three suppliers account for a material majority of industry shipments, and the top five further consolidate share. This creates a strategic environment where scale, channel access, and brand relationships with OEMs and large distributers deliver clear advantages. Leading global players — spanning European scale manufacturers to North American and Asian innovators — adopt differentiated strategies:
-
SPEED Group (France) — global production scale and OEM integration. Their capacity breadth positions them as a partner of choice for high-volume OEM programs and white-label distribution across multiple geographies.
-
Proulx Manufacturing (U.S.) — formulation-led differentiation. Product variants like ultra-quiet and tri-blend lines target professional users and OEM approvals, translating into premium positioning in noise-sensitive and commercial channels.
-
Judin Group / Judin-line (China) and Zhejiang Hausys (China) — vertical extrusion expertise and cost-competitive OEM supply, often servicing high-volume aftermarket and regionally focused professional channels.
-
Husqvarna, STIHL, ECHO, Oregon/Blount, Arnold, DEWALT — equipment OEMs and branded line strategies. These companies integrate trimmer line into broader equipment ecosystems, using proprietary line/head combinations (and latch/feed technologies) to reinforce brand lock-in and serviceable replacement demand.
Strategic takeaways: scale and channel control matter. Smaller specialists can still win via formulation patents, service models, and route-to-market agility, but any growth plan should explicitly address distribution access to both professional landscapers and consumer retail channels.
What our report delivers — practical, transaction-ready intelligence
PW Consulting’s full study blends strategic analysis with operational tools designed to support 2026 commercial decisions. Key deliverables include:
-
Market-sizing and growth scenarios: rigorous base-year quantification (2025) and scenario-driven forecasts to 2032, including sensitivity to polymer price, equipment adoption, and reimbursement program assumptions.
-
Go-to-market playbooks: channel segmentation and prioritized GTM approaches for OEM, professional distributor, and retail channels — including SKU rationalization guidance and promotional cadence recommendations.
-
Cost and margin model: a configurable cost build-up for extrusion, compounding, and finishing that isolates polymer price, energy, labor, and logistics impacts — enabling rapid margin stress-testing under alternative input-price scenarios.
-
Competitive benchmarking and supplier scorecards: objective assessments across capacity, quality certifications, OEM relationships, and R&D pipelines to support supplier selection and M&A targeting.
-
Innovation and portfolio roadmap: prioritized product concepts (noise reduction, wear-resistant geometries, recyclable formulations) with estimated time-to-market and investment thresholds.
-
Risk register and mitigation playbook: from raw-material shocks to channel disintermediation and labor shortages, with tactical mitigants such as dual sourcing, hedging, and aftermarket service bundling.
How to use the study for 2026 decision-making
-
Procurement and sourcing: use the cost model to lock in polymer supply terms for 12–36 month windows and evaluate local versus global sourcing trade-offs given logistics and labor differentials.
-
Portfolio and pricing: align new SKUs to the specific needs of commercial users where premiums may be captured (durability, feed ease, noise), and maintain a value offering for consumer channels to preserve volume.
-
Manufacturing investments: prioritize incremental capacity in extrusion and finishing lines that can switch across profile geometries and compound recipes to maximize utilization and reduce product obsolescence risk.
-
M&A and partnerships: target suppliers with complementary channel reach or proprietary formulations, and consider JV arrangements in regions where distribution friction is high.
-
Regulatory and procurement readiness: while ISO requirements are stable, embed compliance checks in supplier contracts and maintain a watchlist for any emerging material-focused policies.
Analyst note — what we are intentionally withholding here
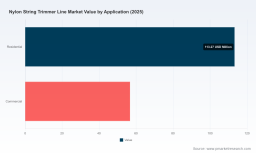
In keeping with our “trailer” approach, this briefing highlights the strategic implications and broad market contours but intentionally omits granular regional and application-level share tables, specific pricing curves, and confidential supplier-level volume figures. Those detailed tables, granular segmentation matrices, and downloadable financial models are included in the full PW Consulting report and associated data pack — essential inputs for transaction diligence and detailed commercial planning.
Closing — the strategic window in 2026
With a healthy growth runway and a market structure that rewards scale, product differentiation, and channel control, 2026 is a pivotal year for participants to convert strategy into measurable advantage. Whether you are prioritizing cost containment, expanding into new distribution channels, or evaluating M&A, a decision framework anchored in the market sizing, cost sensitivity, and competitor benchmarking provided by our study will materially improve execution odds. For teams preparing budgets, negotiations, or product launches in 2026, PW Consulting’s full Nylon String Trimmer Line Market report supplies the operational detail and decision-ready scenarios required to act with confidence.
To access the detailed segment tables, supplier scorecards, and the complete forecast model, consult the full PW Consulting report and data pack — the granular intelligence your 2026 playbook needs.
For detailed analysis of this topic, please visit the official page: Nylon String Trimmer Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


