



PW Consulting: Digital Isolators Market to grow at 7.5% CAGR through 2032

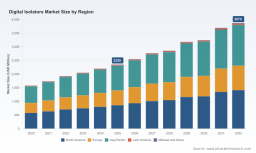
Digital Isolators Market — Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present an executive preview of our flagship market study on Digital Isolators. This briefing is designed to translate the report’s strategic value directly into the near‑term decisions that will define winners and laggards in 2026. The analysis draws on a multi‑year primary research program and market modeling anchored in a 2025 base year; it projects market behavior across 2026–2032 and quantifies trajectory using a 7.5% CAGR over the forecast window (revenue unit: USD Million).
Digital Isolators Market
Quick market snapshot (context, not a substitute for the full study)
- Market scale: The global digital isolators market has expanded from roughly 1.58 billion USD in 2020 to approximately 2.35 billion USD by our 2025 base year, reflecting broad adoption across industrial, automotive and power‑electronics applications.
- Near‑term trajectory: Our model projects continued expansion in 2026 and beyond, with the market approaching the 4 billion USD threshold by the end of the 2026–2032 forecast period under a 7.5% CAGR scenario. This trajectory reflects both volume growth and gradual ASP stabilization driven by increasingly diversified product portfolios.
- Market structure: Concentration is meaningful — the top three players account for a majority share and the top five consolidate roughly three quarters of the market value — a dynamic that influences pricing power, channel relationships and innovation rhythms.
Why this research matters for 2026 decisions
- Actionable risk–reward mapping for portfolio strategy: The study translates macro demand into sub‑market scenarios (high‑voltage gate drivers, power conversion nodes, high‑data‑rate industrial links), enabling product leaders to prioritize R&D and SKU rationalization for 2026 roadmaps.
- M&A and JV playbooks: With mid‑market consolidation clear, the report provides layered diligence material — valuation benchmarks, capability maps and top acquisition targets — to accelerate deal flow or defensive responses in 2026.
- Supply‑chain resiliency and cost planning: We identify component concentration points, alternate sourcing strategies, and near‑term procurement levers to lock in margins when demand surges or when lead‑time volatility spikes.
- Commercial strategy and GTM optimization: Sales leaders receive segmented buyer personas, channel performance indicators and value‑pricing frameworks tailored to industrial, automotive and consumer subsegments to improve win rates in 2026 tender cycles.
- Regulatory and safety compliance roadmaps: As more applications demand reinforced isolation and medical/automotive safety certifications, the study maps certification timelines and cost implications so compliance roadmaps can be aligned with product launches.
Key demand drivers and technology vectors
- Electrification and power‑density pressures: Rising deployment of power electronics — from traction inverters and renewable inverters to high‑efficiency power supplies — is the single largest structural demand driver. Designers require isolation solutions that balance high voltage capability, low propagation delay and thermal resilience.
- Automation and edge connectivity: Higher channel counts and diversity of industrial field buses push demand for multi‑channel, high‑noise‑immunity isolators that maintain signal fidelity at elevated data rates while meeting industrial temperature and EMC requirements.
- Safety and system integration: Reinforced insulation ratings and combined power/data isolation are becoming design prerequisites for medical and automotive segments. Integration with gate drivers or power management circuits is an emerging differentiator.
- Technology differentiation: Competing isolation technologies — capacitive SiO2 barrier devices, iCoupler‑style magnetic approaches, coreless transformer implementations — each present tradeoffs in speed, voltage withstand, power and cost. Design wins will hinge on matching the technology profile to the end‑system constraint rather than defaulting to lowest cost.
What’s inside the full report — practical, executable deliverables
Our report is designed to be immediately operational for 2026 planning cycles. Highlights of the deliverables include:
Digital Isolators Market
- Quarterly‑granularity demand model (2020–2032) with scenario toggles for adoption rates, ASP trends and regulatory shifts — delivered in an interactive Excel workbook.
- Segmentation frameworks mapped to design‑in triggers: by application, data‑rate class, and isolation voltage band — with gating questions for product managers to assess opportunity attractiveness.
- Vendor benchmarking and capability matrix that goes beyond catalog specs to include go‑to‑market reach, manufacturing footprint, supply chain risk scores and patent strength.
- Price and margin intelligence: historic ASP movements, component cost pass‑through sensitivity, and recommended pricing playbooks for new product introductions in 2026.
- Regulatory impact assessment and certification timelines for automotive ISO standards, medical IEC standards and regional safety endorsements, plus the incremental validation costs to budget into 2026 product programs.
- Deal and partnership playbooks: target shortlists for bolt‑on acquisitions, technology partnerships, and contract manufacturing arrangements, each with an estimated time‑to‑value and execution risk score.
- Implementation tools: CIO‑ready supply‑chain heatmaps, R&D prioritization matrices, and 100‑day commercial launch plans to accelerate scale‑up post design‑win.
Competitive landscape — strategic read on the majors
The digital isolator space is dominated by a mix of generalist semiconductor titans and focused analog specialists. Core incumbent profiles and strategic implications follow.
Digital Isolators Market
- Texas Instruments (Dallas, TX) — TI’s strength is breadth: a comprehensive portfolio of reinforced, high‑speed, low‑power capacitive isolators using robust barrier technologies and a family‑based product strategy that supports system designers. Competitive advantage: scale, channel depth and a broad ecosystem that simplifies design‑in. Strategic implication: TI is a natural partner for companies prioritizing design‑win velocity and global distribution, but its breadth can be a barrier for niche players seeking adjacent white space.
- Analog Devices (Norwood, MA) — ADI brings differentiated mixed‑signal know‑how with iCoupler‑based magnetic and capacitive implementations, and strength in low‑latency, high‑voltage and power‑integrated solutions. Competitive advantage: deep analog IP and system‑level integration. Strategic implication: ADI is best matched with applications where integration of isolation with sensing or conversion functions yields system performance gains.
- STMicroelectronics (Geneva) — ST’s offerings emphasize high‑voltage thick‑oxide galvanic isolation designed for harsh industrial environments. Competitive advantage: robustness in temperature/noise extremes and industrial certification pedigree. Strategic implication: For industrial OEMs, ST is a go‑to where environmental ruggedness and lifetime reliability are decisive.
- ON Semiconductor (Phoenix, AZ) — ON’s portfolio is focused on capacitive, high‑frequency modulation across the barrier to combine speed and immunity. Competitive advantage: targeted, mixed‑signal isolation optimized for mixed systems and power‑aware designs. Strategic implication: ON is competitive where mid‑market industrial and consumer designs require a balance of cost, speed and noise robustness.
- Infineon Technologies (Neubiberg, Germany) — Infineon’s ISOFACE™ family, based on coreless transformer technology, differentiates on low power and robust noise immunity with multi‑channel form factors. Competitive advantage: strong traction in automotive and power conversion applications. Strategic implication: Infineon’s positioning favors companies focused on automotive safety and high‑reliability power systems.
Across these players, several strategic patterns emerge: (1) technology choice is increasingly a system‑level decision; (2) scale and certification footprint matter as much as device performance; and (3) mid‑tier players can capture niche value by combining targeted innovation with specialized channel strategies.
Top strategic actions for 2026 (prioritized)
- Fast‑follow modularization: For manufacturers, moving from single‑channel to configurable multi‑channel offerings shortens design cycles and increases wallet share per system. Prioritize modular packaging and reference designs in 2026.
- Certification lead time management: Start automotive and medical certification paths early in 2026 product timelines; certification gating often adds 9–18 months to commercialization in complex systems.
- Supply diversification with strategic inventory: Secure critical die and assembly capacity with second‑source agreements and safety stock to reduce time‑to‑market risk in the event of capacity tightness.
- Value‑based pricing for system‑integrated solutions: Where devices are bundled with gate drivers or power management, employ value‑based pricing rather than cost‑plus to capture systems‑level upside.
- Partnerships over point acquisitions: For companies lacking analogue IP, pursue co‑development or licensing to accelerate feature parity while managing capital deployment.
How PW Consulting can support your 2026 plan
- Custom due diligence and target screening aligned to your strategic thesis, with integrated financial models and integration playbooks.
- Go‑to‑market acceleration sprints: Product positioning, reference design templates, and channel enablement workstreams for rapid design‑win conversion.
- Supply‑chain resilience program: scenario stress‑testing, dual‑sourcing strategies and near‑term inventory optimization tailored to your BOM exposure.
- Regulatory and certification advisory: step‑by‑step timelines, lab partner matchmaking, and pre‑validation audits to de‑risk time to revenue.
Note on scope and access: This executive preview intentionally focuses on high‑level dynamics and strategic implications while withholding granular segmentation outputs and proprietary cell‑level forecasts that constitute the core of the published study. For the detailed segment‑by‑segment forecasts, interactive models, vendor scorecards and a downloadable Excel workbook that operationalizes the study’s inputs for budgetary and product planning in 2026, please consult the full report available through our publication portal.
In an environment where isolation choices influence system safety, cost and time‑to‑market, 2026 will reward organizations that pair rigorous market insight with decisive execution. PW Consulting’s Digital Isolators Market study arms executives with the market intelligence and practical tools required to turn that insight into commercial advantage.
For detailed analysis of this topic, please visit the official page: Digital Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


