



PW Consulting: Maritime Fenders Market—USD 460 Million in 2025, 3.7% CAGR to 2032

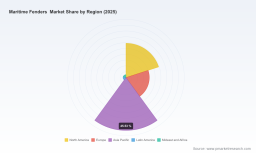
Maritime Fenders Market — Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
As global trade volumes stabilize and port infrastructure investments re-enter multi‑year pipelines, the maritime fenders market is showing steady, predictable expansion. Our latest PW Consulting study (base year 2025; historical series 2020–2025; forecast period 2026–2032) positions the overall market at roughly USD 460 Million in 2025 and projects compound annual growth of 3.7% across the forecast window. That trajectory points to a market that rewards disciplined portfolio and supply‑chain strategies rather than high‑risk, short‑term gambles.
Maritime Fenders Market
Why this research is essential for 2026 strategic planning
-
Regulatory inflection: Industry standards and type‑approval regimes are tightening. New PIANC guidance and subsequent global alignment are already reshaping product qualification timelines and proof‑of‑performance expectations — a material consideration for manufacturers, specifiers and port owners initiating procurement cycles in 2026.
Maritime Fenders Market -
Cost and supply volatility: Raw material pressures — notably constrained natural rubber output in key producing geographies and petrochemical feedstock spikes that have elevated styrene‑butadiene rubber costs — are compressing margins and changing procurement calculus.
Maritime Fenders Market -
Consolidation and scale: Market concentration is meaningful — the top three players do not fully dominate but command a substantial share, and the top five create a more concentrated competitive band. That mix increases the value of differentiated engineering, capacity agility and service capability.
-
Capital allocation inflection points: Recent greenfield capacity additions and plant modernizations demonstrate where incumbents and challengers are placing bets on product mix and lead times. These moves create windows for strategic partnerships, bolt‑on acquisitions and rationalization of legacy product lines.
What the study contains — practical, transaction‑grade intelligence
The report is designed as a toolkit for executives engaged in procurement decisions, product strategy, M&A evaluation and regulatory compliance planning. Key deliverables include:
-
Market sizing and trend analyses: A consistent historical series (2020–2025), a clearly stated base year (2025) and a granular forecast through 2032 (reported in USD Million), with sensitivity scenarios that stress test macro and raw‑material inputs.
-
Demand drivers and end‑use dynamics: Actionable insight on port upgrades, offshore project pipelines and repair/retrofit cycles — highlighting where near‑term demand will cluster and where long‑tail services will persist.
-
Supply‑side and cost buildup: Bill‑of‑materials modelling that isolates the impact of natural rubber availability, SBR feedstock price swings and logistics cost escalation on manufacturer margins and bid competitiveness.
-
Regulatory and standards playbook: Practical checklists for achieving PIANC alignment, suggested timelines for type‑approval testing, and vendor readiness assessments to de‑risk procurement schedules.
-
Company scorecards and competitive positioning: Profiles and strategic assessments of market leaders and notable challengers, focused on capability gaps, go‑to‑market strengths and recent capacity moves.
-
Commercial tools for buyers and sellers: Tender language templates, warranty and lifecycle cost models, and guidance on service‑level agreements to reduce total cost of ownership and unintended risk transfer.
Competitive landscape — who matters and why
The market is populated by a mix of global engineering leaders, regional specialists and vertically integrated rubber and marine‑equipment players. Leaders distinguish themselves through validated performance testing, global project references and integrated service offerings. Notable companies profiled in the study include global engineering groups with broad marine portfolios, specialist foam and pneumatic fender manufacturers, and longstanding regional producers with deep OEM and port relationships.
Our analysis evaluates each firm on certified product breadth, manufacturing footprint, compliance readiness, aftermarket services and exposure to raw‑material cost swings. Recent industry moves — including capacity expansions and the re‑framing of testing requirements — are shifting the basis of competition toward delivery reliability and documented performance under the new PIANC framework.
Regulation and standards: a 2026 breakpoint
PIANC’s recent workstream culminations and updates have crystallized expectations for system‑level design, instrumented testing and formal type approval. The transition to the newer guideline set has made certification a gating criterion for major tenders and has increased time and cost to market for non‑compliant product lines. Manufacturers who have front‑loaded testing, maintained transparent test records and realigned catalogs will be in a favored position to capture 2026 tenders; those slower to adapt face dual risks of specification exclusion and reactive margin pressure.
Raw materials and cost levers: managing margin pressure
Two interconnected dynamics are key inputs to strategic decisions in 2026:
-
Natural rubber supply constraints — driven by labor and climate factors in principal producing regions — continue to exert upward pressure on procurement lead‑times and spot prices.
-
Petrochemical feedstock volatility has translated to notable increases in synthetic elastomer costs, lifting bill‑of‑materials in measured but material ways.
Successful manufacturers are combining supplier diversification, price hedging and product design revisions (material substitution where acceptable) to defend gross margins while preserving performance warranties.
Strategic playbook for 2026
-
Procurement and inventory: Move from just‑in‑time to just‑in‑case for critical elastomers where price spikes and lead times are proven. Negotiate volume collars or index‑linked contracts to stabilize cost exposure.
-
Compliance and product roadmap: Prioritize investments in testing and documentation to meet PIANC expectations. For OEMs and suppliers, revalidate catalogues and labelling to expedite tender qualification.
-
Go‑to‑market and service: Differentiate on lifecycle value — offer bundled installation, inspection and refurbishment programs tied to performance warranties rather than competing on unit price alone.
-
M&A and partnerships: Target bolt‑ons that add certification capability, shorten lead times or secure preferred access to critical elastomers. Opportunistic consolidation is likely to continue where regional specialists have complementary service footprints.
-
R&D and product engineering: Invest in materials science to reduce dependence on constrained inputs and to develop lighter, longer‑life fender architectures that lower total lifecycle cost for port operators.
How to use PW Consulting’s deliverables in a boardroom context
Executives should treat the report as a decision‑support package: use the forecast scenarios to size capex and OPEX implications, apply supplier scorecards during procurement rounds, and reference the regulatory checklist when defining tender and acceptance criteria. For transaction teams, our valuation overlays and earnings‑at‑risk modelling help quantify price pass‑through limits and synergies in potential acquisitions.
Recent industry signals that demand attention
-
Targeted capacity increases by manufacturers underscore a strategic shift toward higher throughput for foam and steel‑integrated units; companies that have recently commissioned new production footprint now command better lead‑time resilience.
-
Standards updates and effective enforcement timelines are shortening procurement cycles for compliant solutions and increasing the cost of non‑conformance for suppliers. Early compliance is a competitive advantage.
Next steps for buyers, suppliers and investors
For port authorities and shipyards: embed the new standards into tender documents now and require documented type approvals to avoid schedule slippage. For manufacturers and distributors: prioritize certification, target operational improvements that reduce lead times and formalize long‑term elastomer procurement plans. For investors and M&A advisors: look for targets with certification‑ready product lines, defensible aftermarket service positions and modular production that can be scaled with limited capital intensity.
Engage PW Consulting for tailored execution
PW Consulting can convert the market intelligence in this report into executable plans — from procurement playbooks and supplier audits to acquisition diligence and regulatory remediation roadmaps. Our advisory engagements translate the macro forecast, cost‑pressure scenarios and competitive assessments into measurable actions and KPIs for 2026 and beyond.
To review the complete dataset, company scorecards and transaction models that underpin these insights, access the full Maritime Fenders Market report on the PW Consulting portal. The publicly visible executive summary highlights strategic findings; the full report contains the granular, audit‑grade detail needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Maritime Fenders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


