



Glass Mold Market to grow at 5.0% CAGR — Asia Pacific largest at USD 452.24M — PW Consulting

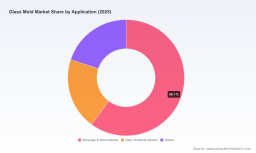
Glass Mold Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high‑level strategic preview of our Glass Mold Market research to guide executive decision‑making in 2026. This article is designed as a “trailer”: it surfaces the study’s most consequential insights, the forces that will shape the sector over the next investment cycle, and the pragmatic options open to manufacturers, OEMs, investors and procurement leaders — while intentionally withholding the granular segment detail and proprietary financial tables that sit behind our paywall.
Glass Mold Market
Market at a glance: where we are and where we’re headed
-
Historic momentum: The global glass mold market grew steadily through the early 2020s, rising from roughly USD 920 million in 2020 to an estimated USD 1,135 million in 2025. That trajectory reflects a combination of steady end‑market demand and targeted productivity improvements among leading manufacturers.
Glass Mold Market -
Near‑term outlook: Our forecast period begins in 2026 and extends through 2032. The market is projected to expand at a compound annual growth rate (CAGR) of approximately 5.0% over 2026–2032, reaching an estimated USD 1,618.27 million by 2032. The 2026 checkpoint is an important inflection year — our model projects a 2026 market size consistent with continued expansion versus 2025.
Glass Mold Market -
Competitive structure: The market exhibits moderate concentration: the top three players account for a meaningful share of industry revenue, and the top five amplify that position further. This creates both barriers and opportunities for scale, technology leadership and transaction activity.
Why this matters for 2026 corporate strategy
A 5.0% CAGR signals a market expected to grow steadily rather than explode overnight. That growth, combined with moderate concentration, means that 2026 is a year for calibrated strategic moves rather than broad‑brush bets. Executives should prioritize three decision imperatives:
-
Allocate capital where differentiation is defensible. Growth exists for premium, durable molds and for suppliers that can reduce total cost of ownership (TCO) through longer life, lower cycle times or advanced coatings. CapEx should favor automation and material engineering where payback is demonstrable under a 5% CAGR scenario.
-
Hedge input‑cost and talent risk. Escalating alloy and specialty ceramic prices, and a tight market for skilled mold technicians, mean procurement and HR strategies materially affect margin. Dual‑sourcing, long‑term material contracts, and in‑house upskilling programs are practical levers to protect throughput and margin.
-
Position for regulatory‑driven demand. Packaging regulations in key markets are reshaping demand profiles; for example, European policy pushes toward higher reuse and recycling rates for glass containers, increasing the premium on durable, repairable molds. Companies that can certify compliance and shorten time‑to‑market for compliant molds will capture outsized share of regulated procurement spend.
Market dynamics: five forces shaping outcomes in 2026
-
Raw‑material volatility: The cost base for high‑performance alloys and technical ceramics used in long‑life molds has been rising. Manufacturers will need more sophisticated input‑cost models and scenario planning to set sustainable pricing or to secure margin through productivity gains.
-
Skilled labor scarcity: Precision mold manufacture requires decades of tacit knowledge. The supply of experienced moldmakers is constrained in many production hubs. Business models that marry automation with targeted human expertise — for example, using operators for finishing and engineers for process tuning — are proving most resilient.
-
Regulation as a demand accelerator: Packaging rules that increase recycling or reuse rates create longer replacement cycles for downstream containers but increase demand for more durable mold technologies and retrofits that extend machine life. Regulatory trajectories should be a central input to product roadmaps and commercial conversations with container producers.
-
Technology substitution and differentiation: Additive manufacturing for mold prototyping, advanced surface treatments to reduce defects, and sensorized molds for process feedback are not uniformly adopted yet, but they are rapidly becoming table stakes in premium segments.
-
Consolidation and value migration: With moderate concentration at the top, the industry is predisposed to selective M&A — either to secure scale in target geographies or to acquire technical capabilities (coatings, IS‑machine integration, sensorization). Strategic buyers are also on the lookout for tuck‑in specialty players that serve niche artisanal or high‑value decorative segments.
Competitive landscape — what to watch from the leading players
Our full report contains deep profiles and capability maps for the principal suppliers. Below is a condensed strategic assessment of the named incumbents and what their moves imply for 2026 planning.
-
Omco International N.V. — European engineering and integrated mould manufacturing. Strengths: systems integration with IS machines and a mature service network. Strategic focus: expand aftermarket services and lean into higher‑margin integrated solutions. Watch for partnerships with container machinery OEMs and aftermarket subscription models.
-
Ross International LTD — U.S. engineering and hollow glass mould expertise. Strengths: deep engineering services and tooling expertise for commercial glass forming. Strategic focus: verticalizing into maintenance and retrofits for older IS fleets. Look for cross‑selling into packaging converters and capital equipment OEMs.
-
Changshu Jianhua Mould Technology Co., Ltd. — China‑based manufacturer with breadth in container and glassware molds. Strengths: cost‑competitive production and growing quality control. Strategic focus: climbing the value chain through quality certifications and exports. Expect more aggressive global tender participation and strategic OEM relationships.
-
TOYO Glass Machinery Co., Ltd. — Japanese precision and machine component specialist. Strengths: precision engineering and integration with forming machinery. Strategic focus: add‑on technologies and higher tolerance molds for premium container lines. Watch for licensing/technology alliances.
-
Slumpy’s — The Glass Mold Company — Niche artisan and specialty molds. Strengths: unique capabilities for warm‑glass slumping, draping and artistic applications. Strategic focus: defend niche pricing through IP and bespoke services. Attractive as a strategic bolt‑on for companies seeking specialty market exposure.
Across these players, common vectors to monitor include capital investment plans, IP filings (coatings & sensorization), aftermarket service expansion, and geographic footprint changes tied to trade dynamics and regional regulation.
What the PW Consulting report delivers — practical, actionable modules
Our research is designed to be immediately operational for strategy, procurement and corporate development teams. Key modules include:
-
Executive synthesis with decision checklists for 2026 planning.
-
Market sizing and forecast models (historic 2020–2025, base year 2025, and detailed scenario forecasts through 2032) with downloadable model files to stress‑test assumptions.
-
Supplier capability heatmaps, manufacturing footprint maps and lead‑time overlays to inform sourcing decisions.
-
Unit cost and TCO models that isolate the impact of raw‑material prices, labor, and maintenance regimes on profitability.
-
Technology adoption roadmaps (additive prototyping, surface engineering, embedded sensing) and practical pilot templates.
-
Regulatory impact scenarios (including high‑compliance pathways) and procurement specification templates to accelerate RFPs.
-
M&A screening lists with strategic value drivers — scale, capability or access to regulated markets — and a prioritized shortlist of targets and integration checklists.
-
Commercial playbooks for pricing, warranties and service contracts calibrated for differing customer maturity and regulatory regimes.
Note: the granular regional and application breakdowns, company financials, and the embedded model spreadsheets are part of the full report and purposefully omitted from this preview to protect proprietary analysis and to encourage direct engagement.
Strategic recommendations for 2026 — a five‑point checklist
-
Secure material supply: enter multi‑year agreements for critical alloys and ceramics or build inventory cushions tied to a rolling six‑month price review.
-
Invest in targeted automation and digital tooling: prioritize investments that shorten mold qualification cycles and improve OEE on container lines.
-
Design a regulatory playbook: map product modifications required to address evolving packaging mandates in core markets and build certification timelines into product roadmaps.
-
Pursue selective M&A or partnerships: prioritize targets that deliver immediate aftermarket scale, proprietary surface technologies, or access to regulated demand pockets.
-
Build talent resilience: couple recruitment with apprenticeship programs and cross‑training so critical tacit knowledge resides with the firm rather than a few individuals.
Events and near‑term signals to watch
-
Trade shows and industry exhibitions that surface new mold materials and process technologies — for example, pre‑registration for major glass industry events in 2026 will showcase high‑end manufacturing and green development themes.
-
Procurement cycles among major beverage and container OEMs that align product spec updates to regulatory timetables.
-
Public filings and patent activity from the leading suppliers that indicate strategic focus on coatings, additive manufacturing or sensor integration.
Next steps — how to convert insight into action
If your 2026 strategic plan requires validated market sizing, supplier due diligence, executable M&A targets, or procurement playbooks tailored to regulatory scenarios, PW Consulting can deliver the full market study including the interactive forecast model, supplier scorecards and transaction templates. The full report supplies the granular regional, application and type breakdowns, detailed competitor financials and the spreadsheets you need to operationalize the recommendations above.
For decision‑makers who must allocate capital, negotiate long‑term supply contracts, or evaluate acquisitions in 2026, the difference between a conservative, defensive plan and an opportunistic, growth‑oriented play often lies in access to the underlying segment detail, cost models and supplier maps. This preview surfaces the strategic contours — the full report gives you the tactical instruments.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Glass Mold Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


