



PW Consulting: Silicon Metal Market to Expand at 5.5% CAGR (2026–2032)

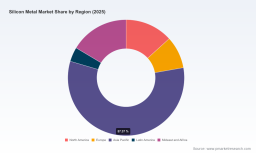
Silicon Metal Market — Strategic Preview for 2026 Decision Makers
Why this briefing matters now
As companies reset industrial strategies for the mid-2020s, silicon metal has re-emerged as a cross‑sector choke point: it is simultaneously a feedstock for aluminum alloys, silicones, polysilicon and select semiconductor applications, and a barometer for energy- and trade-driven supply risk. PW Consulting’s new Silicon Metal Market study (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) crystallizes that complexity into actionable insight for executive teams planning capital allocation, procurement, and geopolitical risk mitigation in 2026.
Silicon Metal Market
Market at a glance (directional)
- The global silicon metal market, measured in USD million, demonstrated steady growth through the early 2020s and crossed the two‑billion USD threshold in 2025.
- Our forecast model projects a medium‑term compound annual growth rate (CAGR) of 5.5% for 2026–2032, driven by demand elasticity in energy‑transition and electronics value chains and by policy incentives favoring low‑carbon domestic production.
- Market concentration is moderate: the top three producers account for a little over one‑third of market share, and the top five under half — a structure that supports both strategic partnerships and targeted capacity expansion by mid‑sized players.
What this study delivers — practical, transaction‑ready outputs
Our objective was to create a study that senior leaders can use immediately to inform procurement strategies, capital project prioritization, and M&A/partnership screens. We do not publish raw granular invoices or confidential contract terms; instead, the report provides:
Silicon Metal Market
- Proprietary scenario models that map price, input‑cost and policy shocks to EBITDA and cash‑flow profiles across typical silicon‑using plants (aluminum‑alloy smelters, silicone manufacturers, polysilicon operations).
- Supply‑chain stress tests showing node‑level vulnerability to export controls, trade remedies, and regional energy price volatility. Each test produces a ranked mitigation playbook (sourcing diversification, inventory policy, strategic offtake, localized processing, and flexible feedstock clauses).
- A rolling capital‑project ROI matrix that converts capacity expansions, brownfield upgrades, and low‑carbon retrofit projects into NPV and payback timelines under three energy‑price and carbon‑policy regimes.
- Commercial negotiation templates and procurement KPIs tailored to silicon metal spot, term and tolling frameworks — including clauses to protect buyers during regional pricing dislocations and regulatory actions.
- Competitive supplier assessments and a prioritized shortlist for joint ventures, off‑take, and technology licensing, each backed by operational and ESG due‑diligence checklists.
Key strategic implications for 2026
Executives should treat 2026 as a hinge year. The interplay of trade measures, regional industrial policy, and rising input costs has created both near‑term price volatility and durable incentives to reorient supply chains. From a decision‑making perspective, three priorities rise to the top:
Silicon Metal Market
- De‑risk procurement with a dual approach: secure near‑term term contracts to cap exposure and concurrently develop optionality through geographic diversification and technology partnerships (for example, low‑emission electrochemical routes, waste‑heat integration).
- Reassess capital projects through a policy lens: new incentives in large markets for domestic or low‑carbon production change expected returns on retrofits and greenfield investments; projects that were marginal under previous assumptions can become value‑creating under incentive scenarios.
- Build regulatory intelligence into commercial clauses: antidumping and countervailing actions, import licensing changes, and strategic‑materials classifications now materially affect price spreads and delivery risk. Contract design must reflect dynamic tariff and licensing exposure.
Competitive landscape — who matters and why
The industry remains dominated by a mix of vertically integrated aluminum/ferrosilicon groups, specialized silicon producers, and regional exporters. Each class brings different strategic value to buyers:
- Large vertically integrated groups offer scale and downstream integration but are sensitive to alumina/electrolytic aluminum cycles and commodity price swings. When such groups pivot to secure domestic or low‑carbon outputs, they can reshape regional supply cost curves.
- Independent high‑purity specialists provide product quality and technical service for electronics and photovoltaics — a premium segment where long‑term agreements and technical collaboration deliver the most value.
- Regional exporters fill short‑term supply gaps and are often price‑competitive; however, these suppliers can be subject to trade actions and demand‑side concentration risk, which has implications for procurement resilience.
Notable firms profiled in our analysis include European integrated producers with multi‑continent footprints, large Nordic and Chinese suppliers focused on high‑purity streams, U.S. niche refiners with strategic domestic shares, and Latin American exporters serving global markets. For each company we map asset location, feedstock exposure, product-grade mix, recent strategic moves and ESG posture — and we translate that into a buyer‑facing capability matrix that ranks suppliers on reliability, price risk, and low‑carbon transition readiness.
Recent market moves that reshape 2026 planning
Several developments in 2025–early 2026 altered the playing field and are reflected in our scenario work:
- New production technologies and product launches: entrant firms and established producers announced low‑carbon or low‑emission silicon product lines using electrochemical or renewable‑powered routes. These innovations change the cost and carbon calculus of long‑term offtake contracts and create opportunities for branded low‑carbon feedstocks in supply agreements.
- Capacity adjustments and commercial linking: incumbents expanded capacity in select jurisdictions while some regional producers secured long‑term commercial agreements with downstream manufacturers — moves that alter short‑term tightness and the visibility of supply for buyers in strategic value chains.
- Trade and regulatory action: antidumping and countervailing duty filings, and formal determinations by trade authorities, have widened regional price spreads and prompted re‑routing of trade flows. Separately, policy moves classifying silicon metal as a strategic raw material, and new export‑licensing regimes for related critical inputs, have increased the value of onshore capacity and secure supply chains.
Price and input cost environment
Energy and quartz ore cost trends are the dominant upstream drivers. Recent regional price upticks tied to energy and feedstock shortages underscore how supply‑side shocks in one region can transmit globally by shifting trade flows and prompting policy reactions. Our modeling shows that even moderate cost inflation erodes margins for spot buyers but can improve returns on investments in localized, low‑carbon capacity when coupled with production incentives.
What we intentionally withhold (and why)
True to the “trailer” principle of this preview, we demonstrate methodological depth while withholding the granular, segment‑level matrices and the full supplier scoring tables that constitute the study’s proprietary value. Specifically, we do not publish detailed region‑by‑region or application‑by‑application line items in this briefing. Those segmented figures are available only in the complete report and underlying data package. This protects commercial confidentiality of sources and preserves the strategic advantage for subscribers who require transaction‑level specificity.
How executives should use the full study in 2026
- Procurement leaders: deploy the procurement playbooks and contract templates immediately to hedge exposure for H2 2026, reprice term sheets and institute force‑majeure/articulation clauses tied to trade measures and licensing regimes.
- Strategy and corporate development teams: use the ROI matrix to re‑rank greenfield and brownfield projects; the report’s M&A screen identifies targets by technical capability and policy fit rather than headline volume alone.
- Government and public‑affairs teams: leverage the regulatory scenarios and supplier intelligence to inform advocacy and to design incentive requests that are credible and quantified for policymakers.
Final word for 2026 planning
Silicon metal sits at the intersection of decarbonization, electronics scaling, and trade geopolitics. The market has demonstrated resilience and a steady growth trajectory through 2025, and our forecast to 2032 at a mid‑single‑digit CAGR reflects continued structural demand from energy‑transition technologies and electronics. However, the real strategic battleground in 2026 will be around supply certainty and low‑carbon credentialing: companies that move now to lock flexible supply, redeploy capital to policy‑aligned projects, and embed trade‑aware clauses into commercial contracts will convert today’s volatility into multi‑year advantage.
Next steps
For boards and executive teams preparing 2026 plans, PW Consulting offers targeted briefings that pair the full Silicon Metal Market study with a workshop to translate findings into one‑page decisions — from immediate procurement actions to a 36‑month capital allocation roadmap. Contact PW Consulting to access the full report, the underlying datasets, and a customized strategic session tailored to your company’s position in the silicon value chain.
For detailed analysis of this topic, please visit the official page: Silicon Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


