



PW Consulting: SMT Equipment Market Poised for 7.49% CAGR Through 2032

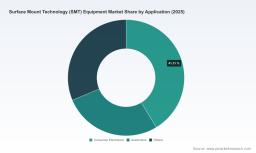
Surface Mount Technology (SMT) Equipment Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
Surface Mount Technology equipment sits at the intersection of electronics manufacturing scale-up, automation intensity, and materials volatility. Our PW Consulting market model — anchored to a 2025 base year and drawing a five‑year historical series (2020–2025) into a 2026–2032 forecast window — shows the global SMT equipment market expanding steadily, supported by continued demand from consumer electronics refresh cycles, automotive electrification, advanced packaging, and higher automation penetration across contract manufacturers. The market grows from about USD 6.1 Billion in 2025 to just over USD 10 Billion by 2032, implying an annualized expansion near a 7.5% CAGR across the forecast period.
Surface Mount Technology (SMT) Equipment Market
Why this research matters for 2026 corporate strategy
-
Timing capital: 2026 is a hinge year for many manufacturers — component packaging transitions, investments in unmanned lines, and regional sourcing shifts mean that a narrowly timed CapEx decision can lock in five- to seven-year productivity differentials.
Surface Mount Technology (SMT) Equipment Market -
Supplier selection and configuration: Equipment choice today defines throughput, flexibility, and total cost of ownership (TCO) across several product cycles. The research decodes vendor roadmaps and maps them to factory architectures that are likely to be dominant through 2032.
Surface Mount Technology (SMT) Equipment Market -
Risk-adjusted sourcing: Raw-material and export-control dynamics are elevating supply‑chain risk premiums. Our work translates those macro risks into specific mitigation levers — dual sourcing, vertical integration, buffer strategies — that are actionable in 2026 procurement plans.
-
M&A and partnership playbooks: For corporate development teams, the market’s structure and growth vector point to targeted tuck-ins and strategic alliances (automation software, 3D inspection, high-speed placement niches) that accelerate near-term capabilities without three‑ to five‑year organic build cycles.
What’s in the full PW Consulting SMT Equipment Market report
-
Transparent market sizing and methodology: historical series (2020–2025) and a detailed 2026–2032 projection with scenario variants (base, accelerated automation, constrained-supply scenarios).
-
Practical CapEx playbook: prioritized equipment investments by factory archetype, expected payback ranges, and sensitivity to utilization and labor-cost assumptions.
-
Supplier scorecards and vendor fit-maps: comparative assessments across throughput, flexibility, integration readiness (SMT + AOI + reflow), software maturity, and aftermarket economics.
-
Technology adoption roadmap: when and where to introduce hybrid placers, jet dispensing, inline 3D AOI/AXI, and automatic kitting to achieve optimal mix of yield, speed, and floor-space efficiency.
-
Supply-chain risk matrix: granular impact scenarios for raw-material price swings (notably silver and critical minerals), export control episodes, and feeder/component lead-time stress tests.
-
M&A and partnership investment memos: target profiles, valuation comparables, and integration checklists for strategic acquisitions or joint ventures in automation and inspection.
-
Operational diagnostics library: benchmarking KPIs, throughput calculators, and a modular checklist for retrofitting legacy lines into semi-autonomous cells.
Market structure and competitive dynamics — what to watch
The SMT equipment market is fragmented relative to many mature machinery sectors: the top three vendors account for roughly a quarter of market revenues, and the top five for around thirty percent — a structure that keeps innovation cycles competitive and creates room for niche specialists. That fragmentation favors buyers who can assemble heterogeneous lines optimized by function rather than adopt single-vendor mono-lines indiscriminately.
-
Fuji Corporation — Japan-based Fuji continues to push automation at the cell level. Recent product developments such as a compact all‑in‑one placement machine and an automated kitting station signal an intentional move to enable unmanned, high-mix production cells. Their strategy is to marry modular hardware with line automation to reduce indirect labor and improve line uptime.
-
Yamaha Motor — Yamaha’s portfolio spans mounters to printers to smart-factory software. New hybrid placers and entry-level printers indicate a two-pronged approach: defend share in high-throughput lines while capturing growth among smaller, automation-hungry contract manufacturers.
-
Juki — Juki’s high-speed flexible mounters underscore the persistent demand for speed in areas where component densities rise quickly. Their speed leadership remains a selling point for high-volume electronics OEMs.
-
ASMPT — ASMPT is positioning SIPLACE and DEK as combined productivity levers, promoting hybrid solutions that bridge oversized board handling and semiconductor/SMT integration — an important play as packaging convergence accelerates.
-
Inspection and niche leaders — Vendors such as Koh Young, Viscom, Mirtec, Saki, and TRI remain central to quality assurance. Their 3D AOI/AXI capabilities and inline X-ray inspection are becoming required investments as component miniaturization makes visual inspection insufficient.
-
Process specialists — Firms including Nordson and Heller continue to anchor materials dispensing and thermal processing respectively; their upgrades in precision dosing and thermal profiling are critical to defect reduction and cycle-time optimization.
-
Mid‑market and modular vendors — Europlacer, Mycronic, Hanwha, and other modular-system providers offer configurable approaches, which are attractive to contract manufacturers and regional OEMs pursuing staged automation investment.
Recent vendor moves — what they signal for buyers
-
Product launches emphasizing hybrid placers, compact all‑in‑one machines, and auto‑kitting are a clear signal: vendors are optimizing for unmanned, flexible production cells that can be deployed rapidly and scaled modularly.
-
Showcase improvements in throughput (productivity uplifts announced at trade shows) indicate that incremental productivity gains — in the 20–30% range from specific vendor claims — will be a key short-term driver of replacement cycles for mid-life lines.
-
Awards and strategic initiatives around die placement and semiconductor integration demonstrate vendors’ response to cross-domain demand as advanced packaging and IDM/OSAT needs influence SMT equipment design.
Headwinds and structural risks for 2026 planning
-
Materials cost inflation: Elevated prices for silver and other critical inputs have increased both BOM costs for solder pastes and the price of consumables (feeders, nozzles). Buyers must factor higher per-board material cost into payback analyses and negotiate longer-term supply contracts.
-
Export controls and concentration risk: Recent export restrictions on certain minerals and semiconductor-related materials have increased supply concentration and created jurisdictional risk for sourcing. Manufacturers should run jurisdictional stress tests and consider geographic diversity for critical spares.
-
Component availability and feeders: Lead-time volatility for feeders and certain components is contributing to longer procurement cycles; strategic inventory and supplier bifurcation are practical mitigations.
-
Regulatory compliance: New export control measures affect equipment with semiconductor-capable functions, requiring tighter legal review in procurement contracts and potential licensing workflows for cross-border sales.
How to use this research in your 2026 decision cycle
-
Layer the report’s scenario outputs against your plant-level capacity plan to prioritize which lines to upgrade in 2026 versus 2027–2028.
-
Use our supplier scorecards to design mixed-vendor lines that maximize throughput and resilience, and to negotiate bundling discounts on service agreements and spares.
-
Apply the CapEx playbook to model replacement versus retrofit decisions, including sensitivity to silver price swings and utilization thresholds that affect payback.
-
Leverage the M&A memos to identify targets that can deliver missing capabilities (e.g., inline 3D inspection, jet printing, or automatic kitting) without protracted internal development.
What we intentionally withhold (and why)
To preserve the value of the research package and direct users to the full dataset, this preview deliberately omits granular regional and application split tables, and the detailed subsegment revenue and share figures that underpin our vendor positioning and scenario analytics. Those granular breakouts — including regional demand curves, application-specific unit economics, and vendor-specific revenue tables — are included in the full report and interactive dashboards available from PW Consulting.
Next steps — how to get actionable insight now
-
Download the full report package to access interactive models and vendor scorecards, or schedule a workshop with our SMT practice to run the model against your factory-level data.
-
Commission a rapid 4‑week diagnostic if you require a CapEx road‑map aligned to your product mix and regional risks; our engagement combines the report’s quantitative backbone with on-site productivity and maintenance audits.
-
Subscribe to our quarterly SMT monitoring brief for vendor-release tracking, commodity-price alerts, and regulatory-watch updates to keep procurement and operations teams aligned through 2026.
In 2026, SMT equipment choices will determine not just throughput but flexibility, compliance posture, and the ability to capture higher-value assembly work. PW Consulting’s SMT Equipment Market research provides the decision-grade inputs to align procurement, operations, and corporate development to that reality — combining a transparent market model, supplier intelligence, and practical execution playbooks tuned for the next technology and geopolitical inflection points.
For detailed analysis of this topic, please visit the official page: Surface Mount Technology (SMT) Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


