



PW Consulting: HCl Market to Grow at 5.5% CAGR Through 2032

Hydrochloric Acid (HCl) Market — Strategic Primer for 2026 Decision-Makers
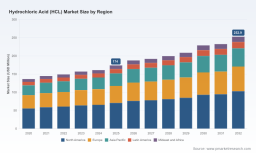
As companies prepare for a pivotal planning cycle in 2026, hydrochloric acid (HCl) stands out as a small-but-critical chemical whose market movements ripple across metals, energy, electronics, and specialty chemicals. Our PW Consulting market model — anchored to a 2025 base year and projecting through 2032 at a 5.5% CAGR — captures a clear trajectory: a market that has grown steadily through the early 2020s and is set to accelerate under the combined influence of advanced electronics demand, supply-structure shifts in the chlor-alkali complex, and tightening environmental and logistics requirements. This brief synthesizes the strategic implications of those dynamics and explains how our full study equips commercial, operations, and corporate development teams to convert insight into action — without disclosing the full segment tables that reside in the full report.
Hydrochloric Acid (HCL) Market
Why HCl Matters Strategically in 2026
-
Leverage nexus: HCl is tightly coupled to core industrial value chains — steel pickling, mining and ore processing, water treatment, chemical manufacturing, and increasingly, semiconductor fabrication. Because of this, modest shifts in HCl availability or pricing can magnify across downstream margins and capital plans.
Hydrochloric Acid (HCL) Market -
Supply-side inflection: The last two years have seen structural changes in chlor‑alkali operations and an uptick in direct chlorine consumption in higher-value end markets. That dynamic is reducing some traditional co-production flows of HCl and thereby changing who must make capex bets versus who can rely on merchant supply.
Hydrochloric Acid (HCL) Market -
Regulatory and ESG overlay: Tighter environmental codes on transportation, emissions, and handling of corrosives are raising compliance costs across the value chain. For producers and distributors, these are not one-time costs but recurring operating constraints that change optimal plant size, location, and logistics strategies.
Market Trajectory — A Data-Driven Snapshot
Our market sizing follows a consistent historical build (2020–2025) and a granular forecast period (2026–2032). Between the beginning of the decade and the 2025 base year the market demonstrated steady expansion driven by post‑pandemic industrial reopening and electronics restocking. Looking forward across the 2026–2032 horizon, the model applies a 5.5% compound annual growth rate, returning a clear picture: demand momentum across specialty and merchant streams, punctuated by bouts of cyclical softness tied to semiconductor and steel cycles.
For commercial strategists, the implication is straightforward: the market is neither hyper‑volatile nor static — it is growing with episodic swings that make timing of capacity additions, long‑term offtake agreements, and price‑linked contracts high-leverage decisions.
Dynamics Shaping Price and Availability
-
Short-term price moves: Recent regional price observations show meaningful softness in Q1 2026 after supply restoration in major chlor‑alkali centers and weaker electronics demand. Those episodes underscore how quickly merchant pricing can reverse when upstream supply constraints abate or when consumption in high‑value segments pulls back.
-
Structural tightening risk: Offsetting short‑term softness is a medium‑term risk of balance tightening as more chlorine is channeled directly into electronics and pharmaceutical intermediates rather than as co‑product HCl. That structural shift is likely to change the economics for merchant producers unless they pursue technology upgrades (for example, membrane cell adoption) or new commercial models.
-
ESG and logistics costs: New transport and emissions rules increase the fixed-and-variable cost profile for widely distributed HCl networks. Companies that internalize compliance through digital tracking, route optimization, or localizing production will achieve a differentiated cost-to-serve position.
Competitive Landscape — Who Matters and Why
The HCl market is commercially significant but remains concentrated: the leading three suppliers account for a material share of the market, and the top five together hold a clear majority — a profile that both raises barriers for fragmented entrants and creates whitespace for focused challengers. The vendor ecosystem is bifurcated between global commodity producers and a smaller set of specialists targeting ultra‑high‑purity HCl for semiconductor and advanced electronics.
-
BASF (Ludwigshafen, Germany) — A leader in ultra‑high‑purity HCl for advanced node semiconductor cleaning. Recent investments include new product lines and dedicated high‑purity capacity designed to serve the most demanding wafer‑processing steps.
-
Olin Corporation (Clayton, Missouri, USA) — A major supplier with capability in electronic grade HCl and a distribution footprint built around industrial customers requiring consistent quality and regulatory compliance.
-
Detrex Chemicals (Cleveland, Ohio, USA) — Focuses on cGMP‑registered ultra‑pure HCl, differentiating through pharmaceutical and semiconductor quality assurances.
-
KMG Electronic Chemicals (USA) — Notable for automation in drum handling and logistics tailored for semiconductor fabs.
-
Regional and specialized players — A cohort of manufacturers (in Europe and Asia) competes on purity controls, service models, and regional proximity to key fabs. New entrants with localized ultra‑high‑purity capacity are strategically important in regions pursuing semiconductor sovereignty.
Recent market moves illustrate how competitive advantage is being created today: established players have announced new ultra‑high‑purity product lines and capacity expansions, while regional producers are bringing localized facilities online to capture near‑fab demand. Automation investments in filling and logistics are another theme: they lower handling risk and improve on‑time delivery metrics — critical when customers are fabs running on tight yields.
Recent Developments to Watch (select)
-
New domestic high‑purity capacity announced to serve semiconductor hubs — signaling both a demand pull for near‑site supply and an answer to geopolitical supply‑chain priorities.
-
Product and capacity investments from major chemical players aimed at next‑generation node requirements.
-
Automation and distribution line deployments reducing fill/transport risk and enabling higher customer service levels for ultra‑pure streams.
-
Quarterly regional price contractions observed in early 2026 following restored upstream chlorine production and softer electronics offtake — a reminder that cyclicality remains a central management theme.
What Our Full Study Contains — Practical Tools for 2026 Execution
This PW Consulting report is designed for immediate operationalization. It combines strategic narrative with executable assets that clients use directly in boardrooms and procurement war‑rooms. Highlights include:
-
Proprietary market model (2020–2032) with scenario toggles for demand elasticity, chlor‑alkali supply shifts, and regulatory cost curves — enabling stress testing of capex and sourcing options.
-
Commercial playbook: a decision matrix for sourcing (spot vs contract vs captive production), pricing mechanisms, and contract terms customized for industrial vs ultra‑high‑purity customers.
-
Supply‑chain maps and logistics optimization templates that incorporate new ESG transport constraints and local compliance regimes.
-
Competitive audit and market‑entry shortlists: granular profiles of incumbents and regional specialists, plus a prioritized list of potential M&A and JV targets aligned to strategic gaps.
-
Risk register and mitigation playbook covering regulatory shifts, feedstock volatility, plant‑level safety and community consent issues, and downstream demand shocks.
-
Investment appraisal toolkit: project IRR sensitivity templates that internalize expected compliance cost trajectories and price volatility scenarios, tailored for greenfield vs expansion decisions.
How Executives Should Use These Insights in 2026
-
Procurement & commercial teams: move beyond unit‑price negotiations to contract design that balances volume, quality tiers, and escalation clauses tied to feedstock and compliance indices. Short‑term price dips are tactical opportunities to secure flexible contracts that protect against medium‑term tightening.
-
Operations and supply chain: run a triage of asset footprint options — localize high‑purity supply for semiconductor exposure; rationalize merchant routes where transportation compliance costs are high; invest in automation in handling to reduce loss events and claims.
-
Strategy & corporate development: evaluate targeted acquisitions of regional high‑purity producers or minority strategic investments in distribution infrastructures. The market’s concentration profile creates room for bolt‑on consolidation or niche specialization plays that quickly move the needle on margins.
-
Risk & sustainability teams: quantify the cost of compliance as a recurring margin pressure and pursue solutions (digital manifests, route consolidation, low‑emission logistics partners) that convert regulatory expenditure into strategic advantage.
Trailer, Not Disclosure — What You’ll Find in the Full Report
In keeping with a “trailer” approach, this primer emphasizes the high‑level strategic implications while preserving the proprietary granularity that underpins corporate decisions. The full PW Consulting study contains the detailed segment tables, regional demand breakdowns, application‑level forecasts, supplier and capacity maps, and downloadable financial models used to produce the topline projections summarized here. Those elements are intentionally withheld from this public summary so that subscribing clients obtain the full, calibrated datasets and interactive models required for transaction‑level decisions.
For executives planning capital allocation, contract negotiations, or M&A in 2026, the decision advantage comes from coupling macro scenario thinking with the granular, verifiable inputs that shape price and availability at plant level. Our report packages both: a strategic narrative to set priorities and a toolkit to execute.
Next Steps
If your 2026 agenda includes new sourcing strategies, capacity planning, or pursuit of semiconductor‑grade HCl opportunities, PW Consulting’s full Hydrochloric Acid market study provides the calibrated data, scenario models, and competitor intelligence to act with conviction. Access to the full dataset and the interactive model is the logical next step for teams that need to move from strategic intent to executable decisions before the next budget cycle closes.
For detailed analysis of this topic, please visit the official page: Hydrochloric Acid (HCL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


