



PW Consulting: Low Melting Fiber Market to Hit USD 345M by 2032 at 6.8% CAGR

Low Melting Fiber Market — Strategic Outlook for 2026
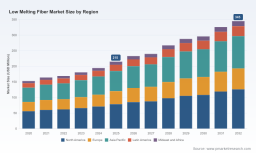
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present a focused strategic primer on the Low Melting Fiber (LMF) market to guide executive decision-making in 2026. This briefing synthesizes our proprietary analysis and primary research (base year 2025) and sets out the implications of industry dynamics that will matter most to investors, procurement leaders, R&D heads, and M&A teams. The market is entering a phase of selective expansion: after steady growth through 2025, our model projects a compound annual growth rate (CAGR) of 6.8% over the 2026–2032 forecast window. The global market baseline in 2025 stood at USD 215.0 Million, with near‑term growth to a larger footprint in 2026 and sustained upside toward 2032.
Low Melting Fiber Market
Why this matters for 2026 decision cycles
Three strategic choices dominate calendar‑year 2026 for companies linked to LMF—where to lock capacity, whether to pursue M&A or partnerships, and how to structure procurement to manage raw materials. The market’s moderate concentration (top 3 firms account for roughly half of global supply and the top 5 approach two‑thirds) means that both incumbents and challengers can shape pricing and product pathways. At the same time, supply‑side developments and raw material behavior make timing critical: polyester staple fiber (PSF) price behavior in 2025 showed a short spike followed by a reversion and range‑bound trading, and importantly, no new low‑melting PSF capacity is planned for 2026. These facts create a window in 2026 where supply rationalization, selective capacity redeployment, or acquisition of distressed assets can deliver outsized strategic value.
Low Melting Fiber Market
Market dynamics: drivers, constraints, and near‑term inflection points
- Demand fundamentals: LMF continues to be pulled by durable demand from nonwovens, automotive interiors, bedding, and technical insulation. Product innovation—conjugate architectures, hollow fibers and engineered cross‑sections—remains the primary mechanism to extract value beyond commodity pricing.
- Raw material and cost volatility: The PSF market’s 2025 gyrations transitioned into a range‑bound state heading into 2026. With no announced new low‑melting PSF capacity for 2026, firms face a near‑term supply tightness risk if demand surprises to the upside, favoring players with vertical integration or long‑dated supply contracts.
- Regulatory and structural events: The announced cessation of operations by a European fiber producer at the end of Q1 2026 and its concurrent acquisition by an investor group introduces both supply disruption and acquisition precedent in the region. That event underscores how regulatory and insolvency outcomes can reconfigure regional sourcing and create pockets of asset opportunity.
- Consolidation pressure vs. niche differentiation: Given the moderate concentration metrics, strategic responses will bifurcate: scale players will pursue cost and distribution advantages, while specialists will double down on engineered formulations (thermal‑bonding conjugates, hollow fibers, eco‑friendly low‑melt solutions) to command premium placement.
Competitive landscape — capabilities to watch in 2026
Our benchmarking of the competitive set identifies several archetypes and capability clusters that define how market players will compete:
Low Melting Fiber Market
- Global scale technology leaders: Firms with broad portfolios and established global footprints are positioned to serve high‑volume channels (automotive, mattresses, hygiene) and to underwrite long‑cycle OEM qualifications. Their strengths lie in R&D pipelines for conjugate and engineered fibers and in the ability to service multinational customers with synchronized quality standards.
- Regional champions with integration advantages: Companies with local raw‑material linkages, domestic sales networks, or adjacent polyester businesses can manage input risk more effectively and offer price stability—an advantage in 2026 when PSF capacity is static.
- Specialists and fast followers: A cohort of mid‑market and regional producers focuses on differentiated product forms (colored LMF, hollow conjugates, specialty staple lengths) and agile custom manufacturing for insulation, technical textiles, and certain automotive applications.
Key companies whose strategies and moves we analyze in the full study include leading global producers and regional specialists spanning Korea, Japan, Taiwan and China. The profiles emphasize product portfolios (e.g., engineered conjugates for thermal bonding, low‑melt polyesters for nonwovens and automotive interiors), geographic footprints, vertical integration, and go‑to‑market positioning. For decision makers, the question is which archetype to emulate or partner with to secure access to differentiated LMF capability versus scale throughput.
What the PW Consulting report delivers (practitioner content)
Our full research is intentionally operational and action‑oriented. Highlights of the deliverables include:
- Forward‑looking market sizing (base year 2025) and robust scenario forecasts across 2026–2032 incorporating technology adoption curves, end‑market elasticity, and raw material scenarios.
- A validated supply‑side map and capacity tracker that flags near‑term closures, acquisitions, and the absence of new low‑melting PSF capacity in 2026—critical for procurement and capacity planning.
- Segment‑level demand drivers and a technology roadmap that shows the commercial readiness and adoption timelines for conjugate/hollow/polyolefin variants and eco‑oriented low‑melt alternatives.
- Company profiles and competitive heatmaps for the leading global and regional players, including capability matrices (thermal bonding tech, fiber architectures, downstream partnerships) and strategic SWOTs to inform partner selection or M&A targets.
- Scenario‑based strategic playbooks for buyers, producers and investors: procurement contracts and hedging strategies, capacity redeployment options, licensing vs. in‑house technology choices, and M&A integration checklists.
- Supply‑chain risk modeling and a shortlist of mitigations for 2026 disruptions—covering dual sourcing, inventory positioning, and flexible production conversions.
Strategic recommendations for 2026 (executive checklist)
- Procurement & commercial: Shift from spot exposure to a mix of short‑term collars and multi‑year supply agreements with volume flex provisions. Prioritize suppliers with integrated polyester feedstocks or demonstrated ability to supply through contractual commitments.
- Capacity & investment: Defer non‑critical greenfield expansions until H2‑2026 unless you have secured feedstock. Instead, evaluate brownfield upgrades (line conversion to conjugate or hollow formats) that deliver higher margin per ton.
- M&A & partnerships: Use the 2026 environment—where insolvency‑driven asset dispositions have precedent—to selectively evaluate distressed or divested assets that fill geographic or technology gaps. Focus on assets that accelerate product qualification with strategic customers.
- Product strategy & R&D: Accelerate development of differentiated LMF formulations that enable higher‑value thermal bonding, improved recyclability, or lower melting points for energy savings. These will command premium positioning as demand for sustainability and performance intensifies.
- Risk & operations: Build scenario playbooks around supply interruptions tied to regional closures and regulatory shifts. Maintain tactical buffer inventories for critical automotive and insulation commitments in 2026 while reducing inventory for commoditized lines.
How to use this analysis
For C‑level leaders and functional heads, the immediate value of this analysis is in prioritizing scarce capital and negotiating leverage in 2026. Short‑term actions (procurement contract design, opportunistic acquisitions, and selective brownfield upgrades) will materially affect competitive positioning through the forecast period. Medium‑term moves (product differentiation and sustainability investments) will determine who captures premium segments as the market grows at an expected 6.8% CAGR over 2026–2032.
Next steps — obtain the full intelligence
This primer highlights the strategic contours you need to evaluate in 2026. To unlock the full, actionable intelligence—including detailed segment economics, region‑level scenarios, supplier scorecards and opportunity maps—access the complete PW Consulting Low Melting Fiber Market report. The comprehensive datasets, supplier due‑diligence annexes and scenario models are essential for teams that must convert strategic intent into executed advantage.
Contact PW Consulting to obtain the full brief, proprietary spreadsheets, and an executive workshop tailored to your role in the value chain. The coming 18 months will separate opportunistic players from strategic winners—use 2026 to position for sustained leadership.
For detailed analysis of this topic, please visit the official page: Low Melting Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


