



PW Consulting: Epoxy Active Diluent Market to Reach USD 1,050M in 2025; 4.5% CAGR (2026–32)

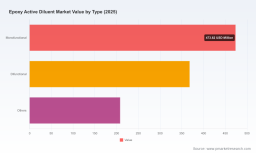
Epoxy Active Diluent Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As PW Consulting’s lead industry analysis for specialty resins, this briefing introduces our forthcoming Epoxy Active Diluent Market study and explains why it should be central to corporate strategy in 2026. Using a 2025 base year, our conservative market model pegs global epoxy active diluent industry value at roughly USD 1,050 Million in 2025, with a forecast trajectory to about USD 1,430 Million by 2032 driven by a 4.5% CAGR across the 2026–2032 forecast window. This steady expansion masks important inflection points—regulatory pressure, material substitution, and new bio‑derived entrants—that will shape winners and losers over the next investment cycle.
Epoxy Active Diluent Market
Why this research matters for 2026 choices
-
Capital allocation: Board-level decisions on capacity expansion, greenfield investments, or acquisitions require defensible, scenario-based sizing and upside/downside cases. Our model quantifies those scenarios against regulatory and feedstock shocks.
Epoxy Active Diluent Market -
R&D prioritization: Chemistry roadmaps (bio-based CAS alternatives, low‑toxicity glycidyl ethers, multifunctional diluents) must be sequenced to protect margins as end-markets demand lower VOC and cleaner supply chains.
Epoxy Active Diluent Market -
Commercial strategy: Sales and product managers need demand segmentation, value‑capture levers, and recommended channel plays to convert incremental formulation advantages into price premia.
-
M&A and partnership screening: With the sector characterized by modest concentration (CR3 ≈ 25%, CR5 ≈ 30%), opportunistic carve-outs and technology tuck-ins remain available but require tight commercial and technical due diligence.
What the PW Consulting report delivers — operational and strategic content
-
Robust market sizing methodology and sensitivity analysis — base year 2025 and a 2026–2032 forecast horizon with scenario-led CAGR paths.
-
Demand-driver mapping by application groups and end‑market adoption curves, anchored to macroeconomic and sectoral indicators.
-
Technology and product landscape — chemistry classes, performance trade-offs, processing constraints, and a technology-adoption timeline.
-
Regulatory risk matrix and compliance playbook — jurisdictional exposure, occupational limits, labelling, and sound mitigation strategies for manufacturers and formulators.
-
Supplier and feedstock risk dashboard — cost‑curve analysis, single‑sourcing risk, and recommendations for contract structures and hedging.
-
Competitive benchmarking — capability heat maps, co‑development opportunities, and a prioritized M&A target list with valuation heuristics (note: granular target scoring is available in the full report).
-
Commercial playbooks — pricing uplifts by value proposition, channel tactics, and customer segmentation for coatings, adhesives, composites, and niche electronics markets.
-
Implementation toolset — slide‑ready executive summaries, an editable financial model, and technical appendices to expedite board-level decisions.
Market dynamics — drivers, constraints and regulatory inflection points
Growth in epoxy active diluents is not monolithic. Demand is being reshaped by three overlapping dynamics: (1) end‑market structural trends such as lightweighting in composites and intensified specifications for industrial coatings; (2) regulatory and occupational health constraints on certain glycidyl ether chemistries; and (3) supply‑side innovation in bio‑based and multifunctional diluents that change formulation economics.
On the regulatory front, there is material movement. Agencies have tightened exposure parameters for common reactive diluents — for example, authoritative sources document an occupational exposure threshold for n‑butyl glycidyl ether — and multiple jurisdictions have set limits on phenyl glycidyl ether. These developments are not theoretical: they create compliance cost floors, potential use restrictions in certain applications, and sourcing complications for downstream formulators. Equally important, regulatory divergence across markets means companies must design flexible compliance frameworks rather than one‑size‑fits‑all product lines.
Raw material volatility and feedstock constraints remain a parallel risk. Some diluents are derived from petrochemical intermediates whose pricing and availability map to broader hydrocarbon cycles; others leverage bio‑feedstocks (e.g., cashew nutshell liquid routes) that introduce agricultural and supply-chain seasonality. The net result: margin compression for commoditised chemistries and opportunity for differentiated, higher‑value formulations.
Competitive landscape — capabilities that matter in 2026
The sector remains moderately fragmented, with small pockets of scale. Success in 2026 will hinge on three capabilities: chemistry differentiation, regulatory/compliance leadership, and integrated go‑to‑market channels into coatings and adhesives OEMs.
-
Cardolite Corporation — specialist in CNSL‑based bio epoxies and reactive diluents; strong footing where bio‑credentials and performance intersect (notable product families address low color and low viscosity requirements).
-
Dow Inc. — scale producer of glycidyl ether diluents with a focus on aliphatic and aromatic chemistries for viscosity control in coatings and composites; strength in supply integration and global reach.
-
Hexion Inc. — emphasis on multifunctional diluents for structural adhesives and high‑performance epoxy systems; technical depth in high‑end applications.
-
Huntsman Corporation — positions around specialty low‑VOC, thermally robust diluents for emissions‑sensitive markets.
-
Evonik Industries AG — focusing on low‑toxicity and zero‑VOC targets; recent sustainability investments underline an ESG‑oriented premium offering.
-
Arkema, Air Products, EMS‑Chemie, Aditya Birla, and SACHEM — each brings either multifunctional expertise, customized formulation capability, bio‑based routes, or high‑purity supply for electronics; collectively they define the competitive vectors.
Recent corporate moves underscore market direction. For example, a major specialty player transitioned curing‑agent production to run fully on green electricity in 2025 — a move that materially reduces Scope 1/2 emissions and strengthens sustainability claims across its epoxy value chain. Another player expanded its bio‑derived diluent portfolio with ultra‑low color, low viscosity products that appeal to premium coatings formulators. These actions illustrate how sustainability and formulation performance are converging into a commercial imperative.
Actionable playbook for 2026
-
0–90 days: Perform a regulatory exposure audit across product lines; stress‑test formulations against evolving occupational limits and identify immediate reformulation candidates. Start supplier resilience scoring focused on single‑sourced intermediates and bio‑feedstock seasonality.
-
3–6 months: Launch prioritized formulation pilots (low‑toxicity glycidyl alternatives, CNSL blends, multifunctional diluents) with selected OEM customers. Negotiate conditional supply agreements with performance‑based pricing to preserve margin while sharing reformulation risk.
-
6–18 months: Execute scale decisions—either incremental plant retooling, capacity rightsizing, or targeted M&A to acquire proprietary low‑VOC chemistries or high‑purity supply lines for electronics. Embed ESG and lifecycle credentials into product specification sheets to command price premium in regulated markets.
How the full PW Consulting report helps you execute
This briefing highlights the strategic levers and risks at play. The full report contains the granular apparatus organizations need to operationalize the insight: detailed scenario financials, region/type/application splits, pricing and margin curves, supplier scorecards, primary‑interview intelligence with formulators and OEMs, and a ranked list of acquisition and partnership candidates with valuation heuristics. In line with our “trailer” approach, we have intentionally withheld detailed segment numbers from this preview to preserve the analytic yield for licensed report subscribers.
If your 2026 capital plan, R&D prioritization, or M&A pipeline touches epoxy diluents, the full PW Consulting dossier converts the macro picture above into executable choices and measurable KPIs. Contact PW Consulting to request the full market intelligence package, including the editable model and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Epoxy Active Diluent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


