



Crystalline Fructose Market: USD 850M in 2025, 5.4% CAGR through 2026–2032 | PW Consulting

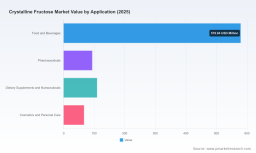
Crystalline Fructose Market: Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
As the ingredient economy rebalances toward lower‑glycemic and calorie‑reduction solutions, crystalline fructose is transitioning from niche sweetener to strategic portfolio element for food, beverage, and nutrition manufacturers. Our PW Consulting analysis anchors on a 2025 base year (USD 850 Million) and projects steady expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.4%. The trajectory from a 2020 starting point through 2025 demonstrates resilience and incremental recovery, with the market continuing to expand into the early 2030s.
Crystalline Fructose Market
Why this matters in 2026
2026 is shaping up to be the inflection year for product teams and procurement functions. Regulators and consumers are simultaneously tightening definitions of “reduced sugar” while demanding taste parity. That combination elevates crystalline fructose from a functional ingredient to a strategic lever for reformulation, product segmentation, and margin protection. With the market poised to grow meaningfully from the 2025 baseline toward the 2032 horizon, executives who align sourcing, R&D, and commercial strategies in 2026 will be positioned to capture disproportionate value as adoption accelerates.
Crystalline Fructose Market
Macro dynamics shaping the next wave
- Taste and functionality premium: Crystalline fructose offers higher sweetness intensity and favorable mouthfeel characteristics that allow formulators to reduce bulk sugar with limited sensory compromise. This is driving sustained adoption in mainstream beverage and bakery applications as well as in higher‑margin nutraceutical and pharmaceutical formats.
- Regulatory and labeling tailwinds: As jurisdictions refine sugar‑reduction claims and front‑of‑pack labeling, manufacturers will rely more heavily on sweetener blends and specialty sweeteners to meet thresholds while managing consumer perception.
- Supply chain and feedstock dynamics: Corn availability, hydrolysis capacity, and regional processing footprints determine both cost volatility and the speed at which innovation can be scaled. Liquids vs. dry forms, particle size variants, and non‑GMO or organic claims create distinct sourcing strategies.
- Consolidation pressure: The competitive landscape is moderately concentrated: the largest global players control a meaningful share of global capacity, while regional manufacturers and traders supply flexibility and price competitiveness. This structure creates both partnership opportunities and risks around supplier concentration.
What PW Consulting’s report gives you in practical terms
We designed the report as a decision tool for commercial, R&D and M&A leaders. The publication contains:
Crystalline Fructose Market
- Market sizing and a seven‑year forecast built on an audited base year (2025), with sensitivity scenarios that stress test demand under diverging regulatory and consumer scenarios.
- A demand model that translates end‑market demand drivers (taste, price, regulation, health claims) into volume requirements and formulation budgets for 2026–2032.
- Price and margin simulation tools that quantify the P&L impact of ingredient switching, blended sweetener strategies, and premiumization.
- Supplier scorecards and capability matrices to prioritize partners by product forms, quality certifications, geographic reach, and scale—ready for procurement RFPs.
- Manufacturing and capacity heatmaps highlighting where commercial scale exists today and where capex will be required to meet projected demand ramps.
- M&A and partnership playbooks that identify targets by strategic fit—capacity, technology, market access—and provide diligence checklists and valuation heuristics.
- Regulatory tracking and labeling implications across major markets, including tactical guidance for claim substantiation and audit readiness.
- Operational risk matrix covering feedstock volatility, logistics bottlenecks, and contract structures to inform hedging and inventory strategies.
Note: To preserve commercial confidentiality and maximize actionable value, detailed segment level splits and granular company market shares are available in the full report.
Competitive landscape: what we see and what it means
The crystalline fructose market sits at the intersection of ingredient manufacturing, specialty sweeteners, and commodity processing. Key global suppliers combine branded product advantages with broad distribution networks, while regional players supply elasticity and price arbitrage. The competitive mix can be summarized as follows:
- Tate & Lyle (London, UK) — Operates a branded crystalline fructose product family with multiple physical formats. Their value proposition centers on consistent sensory performance, particle size options, and an established brand that eases formulators’ validation cycle. For commercial teams, Tate & Lyle represents a partner for higher‑value, co‑developed solutions.
- Archer Daniels Midland (ADM, USA) — A vertically integrated producer with scale in corn processing and downstream sweetener granulations. ADM’s advantage is integrated feedstock control and diverse dry/liquid offerings that suit large CPG accounts seeking supply security.
- Cargill (USA) — Focuses on global reach and technical support for beverage and pharmaceutical customers. Cargill is a natural anchor for multinational rollouts that require synchronized launches across regions.
- Ingredion (USA) — Positions crystalline fructose within a broader reformulation toolkit, emphasizing customization and label‑friendly options (e.g., non‑GMO). Their strength lies in co‑innovation with customers and ingredient blending expertise.
- Gadot Biochemical (Israel) and select Chinese suppliers — These players supply large, stable bulk volumes and are often the backbone for cost‑sensitive formulations and contract manufacturing. Their role in the market is increasingly important for buyers balancing cost and scale.
Strategic implication: top providers already control a significant portion of capacity, but there is meaningful room for selective partnership or acquisition to secure capability gaps—particularly for firms looking to accelerate product reformulation at scale. The market structure favors a dual‑track procurement approach: anchor volumes with tier‑one suppliers for security, and source margin or innovation projects from regional specialists.
Actionable strategies for 2026
Below are prioritized, practical moves that executives should consider implementing in 2026 to convert the market’s structural trends into competitive advantage:
- Lock in multi‑tier supply agreements: Establish at least two supply lanes—one with a global integrated player and another with a regional bulk supplier—to manage price shocks and capacity constraints.
- Invest in formulation kitchens and rapid sensory testing: Shorten time‑to‑market for reduced‑sugar SKUs by enabling in‑house blending and quick validation against shelf stability and sensory gates.
- Pursue co‑development partnerships: Engage a strategic supplier for co‑branded or co‑formulated solutions that can carry shared risk and accelerate commercialization in priority geographies.
- Embed price‑scenario planning into every new product business case: Model multiple feedstock and logistics outcomes to stress test margins before launch commitments.
- Screen M&A targets for capability gaps: For companies seeking inorganic growth, prioritize targets that bring either differentiated product forms (e.g., specialty particle sizes or liquid concentrates) or access to high‑growth channels like nutraceuticals and pharma.
- Operationalize sustainability and provenance claims: Consumers and retailers increasingly demand traceability. Build procurement specs and supplier audits to support non‑GMO, low‑carbon, or origin claims without exposing the brand to regulatory risk.
How to use this intelligence in 2026
Leaders should treat crystalline fructose as both a product engineering tool and a strategic lever for market positioning. Use 2026 to align cross‑functional teams—procurement, R&D, regulatory, and commercial—around a unified ingredient roadmap. Pilot projects should be measured not just for speed to shelf but for scalability and supply resiliency. The PW Consulting report supplies the quantitative models, supplier scorecards, and scenario playbooks to make these choices defensible and actionable.
Next steps
Our public preview outlines the structural market direction and strategic imperatives for 2026, but the full intelligence pack contains the granular segmentation, supplier share tables, and executable playbooks required to operationalize these recommendations. For procurement RFPs, M&A diligence, or reformulation roadmaps, the detailed appendices and model files in our full report are engineered to plug directly into 2026 planning cycles.
Contact PW Consulting to access the full Crystalline Fructose Market report and the accompanying toolkit (market models, supplier templates, regulatory tracker). Strategic decisions in 2026 will separate market leaders from followers; use evidence‑based, scenario‑driven planning to be in the former camp.
For detailed analysis of this topic, please visit the official page: Crystalline Fructose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


