



PW Consulting: FMD Vaccines Market Projected to Grow at 7.8% CAGR Through 2032

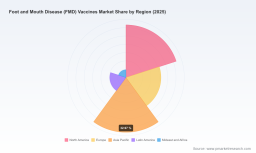
Strategic Outlook: Foot and Mouth Disease (FMD) Vaccines Market — A 2026 Decision Playbook
Executive summary
By 2026, executives and policy-makers in animal health must make high-stakes choices about manufacturing scale, distribution partnerships, and technology investment for Foot and Mouth Disease (FMD) vaccines. Our PW Consulting market study — grounded in a 2025 base year and historical analysis covering 2020–2025 — shows the global FMD vaccines market accelerating from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025, with a projected compound annual growth rate (CAGR) of 7.8% across the 2026–2032 forecast window. By 2032 the market is forecast to approach USD 362.3 Million under the baseline scenario.
Foot and Mouth Disease (FMD) Vaccines Market
This article previews the practical intelligence and decision-grade analysis included in the full report. We surface the structural drivers and competitive tensions that will determine winners in 2026, while intentionally withholding granular segment and regional breakdowns to encourage access to the full dossier for transaction- or planning-level actions.
Foot and Mouth Disease (FMD) Vaccines Market
Why this study matters for 2026 decisions
- Investment sizing: A stable mid-single-digit to high-single-digit CAGR provides a predictable backdrop for capital allocation toward manufacturing upgrades, fill–finish capacity, and cold-chain investment.
- Policy alignment: National vaccination programs and emergency stockpiles will continue to be material demand levers; the study maps policy-driven procurement cycles and timing risks.
- Technology timing: Novel platforms (RNA, marker/DIVA, synthetic antigen approaches) are transitioning from proof-of-concept to field validation — creating windows for early-commercial partnering and licensing.
- Market structure implications: The market exhibits relative fragmentation (the three- and five-firm concentration ratios are modest), which shapes M&A strategies and partnership models (see Competitive Snapshot below).
What the full report delivers — practical, transaction-ready intelligence
Our 200+-page study is structured to be immediately usable by corporate strategy teams, BD executives, and government procurement planners. It includes:
Foot and Mouth Disease (FMD) Vaccines Market
- Market sizing and forecast model (2020–2032), with transparent assumptions and downloadable scenario worksheets for sensitivity testing under alternate outbreak and adoption cases.
- Go-to-market playbooks tailored to five archetypal entrants: incumbent global manufacturers, regional public producers, contract manufacturers, technology licensors, and hybrid public–private partnerships.
- Competitive benchmarking with capability heatmaps (R&D platforms, antigen purification, DIVA/marker capacity, emergency fill–finish, regulatory filings, and distribution reach).
- Supply-chain risk assessment and mitigation templates covering antigen supply, adjuvant sourcing, cold-chain logistics, and manufacturing bottlenecks — with contingency playbooks for surge demand during outbreaks.
- Regulatory and policy intelligence: country-level procurement protocols, vaccine approval pathways, and guidelines for vaccine composition and traceability.
- M&A and partnership screening: a prioritized pipeline of target profiles, synergy estimates, and integration risk checklists — designed to help teams evaluate deals quickly in 2026.
- Operational checklists for launching or scaling production (facility upgrade roadmaps, tech-transfer milestones, validation timelines, and cost-to-scale estimates).
Market trajectory and near-term dynamics
The market’s projected path — underpinned by baseline epidemiology, livestock population trends, and public vaccination commitments — implies steady demand growth rather than a single-source boom. The baseline forecast assumes continued government-led vaccination programs, periodic emergency procurements associated with outbreaks, and gradual adoption of newer vaccine platforms. Scenario analysis in the full study quantifies upside from accelerated adoption of marker and RNA-based vaccines as well as downside risks from supply disruptions or abrupt regulatory retrenchment.
Competitive snapshot: incumbents, challengers and regional anchors
FMD vaccine supply is supplied by a diverse mix of global multinationals, regional specialists, and government-affiliated producers. Key dynamics to watch in 2026 include scale versus specificity, DIVA/marker adoption, and the strategic use of regional production capacity to shorten response times:
- Biogénesis Bagó (Argentina): A global leader in traditional FMD supply with very high-volume production capability and deep distribution linkages across Latin America. Their scale provides a structural advantage in routine program supply and emergency responsiveness.
- Boehringer-Ingelheim (Germany): Differentiates through highly purified antigens and DIVA-compatible vaccine offerings, positioning them strongly for markets prioritizing traceability and disease surveillance integration.
- MSD Animal Health: Offers multi-territory manufacturing and strain breadth, making them a resilient supplier across key livestock markets.
- Zoetis: Notable for joint-development of marker vaccine platforms and domestic manufacturing initiatives aligned with USDA collaboration — a player to watch if marker platforms become a regulatory preference in new markets.
- Indian producers (Indian Immunologicals, Brilliant Bio Pharma, Biovet): Competitive on cost and proximity to large livestock populations; their role in regional security of supply is increasingly strategic.
- Regional public producers (Botswana Vaccine Institute, NVI Ethiopia, Ourofino in Brazil): These organizations secure supply for specific epidemiological profiles (e.g., SAT-type strains, trivalent formulations) and act as government-backed stabilization nodes during crises.
Collectively these players create a marketplace where incumbents compete on scale, quality differentiation (purification, DIVA compatibility), and local presence. The relatively low three- and five-firm concentration ratios indicate opportunity for niche entrants and contract manufacturers to capture value through specialization or service-led models.
Supply chain and manufacturing signals to act on in 2026
Recent industry moves illustrate critical inflection points:
- Public manufacturing resumption in Southern Africa: In early 2026, a national institute restarted local SAT-type vaccine production using modern bioreactor technology and plans to scale weekly output substantially. This highlights the strategic priority governments place on regional manufacturing sovereignty and the opportunities for vendors to support technology transfer and scale-up.
- Large-scale public procurement commitments: Several governments have announced multi-million-dose allocations for 2026 vaccination campaigns, underscoring the importance of synchronized supply agreements and transparent delivery milestones for contract award competitiveness.
- Emergent platforms demonstrating proof-of-concept: Clinical evidence from an RNA-based challenge study showed full protection in cattle with no viral shedding — signaling that platform technologies could materially change durability, manufacturing speed, and cold-chain profiles over the medium term.
Technology convergence and regulatory implications
Two technological vectors will shape strategic choices:
- DIVA/marker vaccines: Where regulators and trade partners demand distinguishability between vaccinated and infected animals, DIVA-compatible options become a procurement differentiator. Companies that can pair DIVA platforms with validated surveillance packages will secure premium tenders.
- Novel platforms (RNA, synthetic antigen): These can shorten development timelines and reduce biosecurity complexity in antigen production. Early movers will need to demonstrate field effectiveness, manufacturability at scale, and a clear regulatory pathway.
Regulatory acceptance timelines will be decisive. Strategies that hedge bets across traditional inactivated formulations and newer platforms — with staged investment linked to milestone-based de-risking — will be best positioned for 2026–2028 transitions.
Strategic imperatives for executives in 2026
Based on our modelling and deal-level analysis, PW Consulting recommends five immediate actions for organizations making 2026 decisions:
- Secure flexible capacity: Pursue flexible, modular manufacturing investments or contract-manufacturing agreements that can respond to both routine program volumes and outbreak surges.
- Pursue strategic partnerships: Combine global product expertise with regional manufacturers’ distribution reach or government relationships to win large public tenders and to shorten lead times.
- Invest in DIVA and surveillance integration: Prioritize vaccine platforms that facilitate trade-friendly disease monitoring and align with purchaser priorities for traceability.
- De-risk supply chains: Lock long‑term supply agreements for critical inputs, and identify dual-source adjuvant and antigen vendors to avoid single-point failures during peak demand.
- Create an M&A/alliancing pipeline: Target acquisitions or minority investments that deliver complementary capabilities (regional fill–finish, strain coverage, or novel platforms) rather than duplicative scale.
How to use the PW Consulting report
Use the full report as a playbook: run the scenario model against your balance-sheet thresholds, apply our supplier heatmaps to shortlist partners, and adopt the regulatory templates to accelerate approvals and tender submissions. The full archive includes downloadable models, supplier diligence checklists, and term-sheet templates that materially shorten time-to-decision.
Closing — a staged call to action
The FMD vaccines market in 2026 is neither a winner-take-all commodity nor an emergent niche locked to incumbents. It is a market where manufacturing agility, platform differentiation (especially DIVA/marker and novel platforms), and government partnerships converge to create strategic advantage. With an estimated market size doubling over a decade under a 7.8% CAGR, the economics justify timely, targeted investments — but success will hinge on execution and the ability to navigate local procurement realities.
PW Consulting’s full study contains the underlying models, proprietary segmentation, and deal-level playbooks needed to operationalize the recommendations above. Note: this preview intentionally omits detailed regional, type, and application splits to protect source-level granularity; those critical subsegment tables and executable tender-by-tender analyses are available in the complete report.
For access to the full dataset, scenario workbooks, and our executive workshop offering to translate findings into a 90-day action plan, please refer to the PW Consulting release page. Our team is prepared to run a tailored briefing to convert the market outlook into a concrete 2026 investment and commercial plan.
For detailed analysis of this topic, please visit the official page: Foot and Mouth Disease (FMD) Vaccines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


