



PW Consulting: Commutator Market to Hit USD 345 Million by 2032

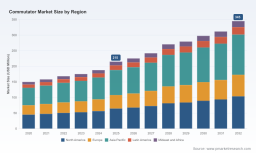
Commutator Market 2026: Strategic Preview for Executive Decision-Making
Executive snapshot
As PW Consulting’s senior strategy team, we prepared this forward-looking primer to frame why the commutator market should be an active element of executive agendas in 2026. The market has completed a multi-year recovery and consolidation phase (historical window: 2020–2025) and enters a period of steady expansion driven by industrial electrification, renewed investment in transportation infrastructure, and durable demand from motor-intensive end-markets. On a macro basis the global market reached its 2025 base and is projected to expand through our forecast window (2026–2032) at a compounded annual growth rate (CAGR) of 6.9%—a profile that supports both organic capacity plays and targeted strategic transactions.
Commutator Market
Why this matters for 2026 corporate strategy
- Investment horizons are tightening. With mid-cycle growth now predictable, capital allocation decisions (capacity expansion, digital manufacturing upgrades, and MRO service capabilities) require precise timing lest firms over-invest in low-return assets or miss first-mover advantages in niche high-margin applications.
- Supply-chain resilience has moved from tactical to strategic. Firms with visibility across commutator raw materials, rotor/stator integration, and remanufacturing pathways will capture outsized margins as OEMs seek single-source partners with quality, speed, and contingency plans for tariff shocks.
- M&A and partnership corridors are opening. The market’s moderate concentration (CR3 ~45%, CR5 ~55%) signals room for consolidation, bolt-on acquisitions, and regional platform plays—especially where local production can mitigate trade friction and logistical costs.
Market trajectory: what the headline numbers tell us
Historical trends from 2020–2025 show recovery from pandemic-related disruption into stable demand growth, driven by replacement cycles in industrial motors and new-volume demand from electrified subsystems. Looking forward, our baseline scenario projects consistent year-over-year expansion through 2032, underpinned by a 6.9% CAGR. For executives, that profile is notable: it is sufficiently robust to justify strategic initiatives while not so hyperbolic as to require speculative product diversification strategies. The preferred corporate responses are therefore pragmatic: invest selectively in capacity, upgrade manufacturing automation, and deepen aftermarket and remanufacturing capabilities.
Commutator Market
Key demand drivers and risks
- Electrification and industrial automation. Demand remains anchored to traditional motor-intensive sectors, but incremental growth is driven by higher-spec applications—where tolerances, materials, and serviceability matter more than commodity pricing.
- Remanufacturing and aftermarket economics. The cost-to-replace calculus favors skilled rebuilders and service players who can deliver turnaround and certified quality, creating a recurring revenue channel that complements new-unit sales.
- Regulatory and trade policy volatility. Recent shifts in U.S. and EU tariff regimes have material impacts on unit economics and supply-chain design—particularly for firms supplying cross-border OEMs. Smart participants are already re-evaluating footprint strategies to insulate margin.
- Raw-material and component integration risk. Access to copper, graphite variants, and precision-machined cores remains a gating factor for consistent output and quality. Supply partnerships and vertical integration are increasingly strategic, not just operational.
Supply chain and manufacturing implications
Manufacturers and OEMs must view commutators not as isolated components but as nodes in an integrated rotor assembly and motor ecosystem. Key implications for 2026 planning include:
Commutator Market
- Nearshoring versus footprint optimization: Tariff-driven cost shocks underscore the value of locating production closer to end customers for high-volume or sensitive applications. However, nearshoring requires investments in local labor skills, quality control systems, and certification processes.
- Automation and digital quality control: Incremental productivity gains from automated winding, segment assembly, and laser inspection can compress lead times and shrink scrap rates—critical for firms competing on reliability rather than price alone.
- Service-network expansion: A resilient aftermarket with rapid-response rebuild centers and certified refurbishment protocols reduces total lifecycle costs for customers and expands recurring revenue streams for suppliers.
Technology and product evolution
Technical differentiation is increasingly decisive. Innovations are concentrated along three vectors: material science (optimized copper alloys and alternative conductive materials), manufacturing tolerances (miniaturization and precision balancing), and serviceability (modular designs that ease field maintenance). For strategic planners, the right question is not only whether to adopt new materials, but where to align R&D and partner investments to secure IP or preferential supply.
Competitive landscape: profiles and strategic positioning
The market comprises specialist manufacturers, regional rebuilders, high-volume component suppliers, and a growing number of integrated motor producers. Several firms illustrate the diversity of approaches:
- ICC International (Maryville, Tennessee, USA; https://iccinternational.com/) — A bespoke supplier focused on custom commutators and slip rings for large industrial motor applications. ICC’s value proposition centers on engineering breadth and capability to support large-scale OEMs with tailored solutions.
- AKARD COMMUTATOR of TENNESSEE (ACT) (Alcoa, Tennessee, USA; https://www.facebook.com/akardcommutatoroftennessee/) — A specialist rebuilder and manufacturer emphasizing service continuity via 24/7 production and emergency response. Their model demonstrates how aftermarket responsiveness can be a competitive moat. Note: ACT recently announced trade-show participation in June 2026, signaling active commercial engagement.
- Ningbo Haishu Nide International (Ningbo, China; https://www.nide-international.com/) — A component supplier with a broad catalog covering a wide range of form factors. Their playbook focuses on breadth of SKU availability and cost-efficient production for global buyers.
- Zhejiang Greatwall Commutator Co., Ltd. (Zhejiang, China) — A high-capacity manufacturer with scale-driven advantages in cost and lead time, representing the large-volume supply tier.
- Huarui Electrical Appliance Co., Ltd. and Dongxu Electricity (Shenzhen) Co., Ltd. (Shenzhen, China) — These players demonstrate integration into motor ecosystems and high-volume production capability, including series motors and commutator assemblies for diverse end-markets.
- Anhui Sinomag Technology Co., Ltd. — A magnetic materials producer that highlights the vertical integration opportunity: pairing magnetic materials with commutator production closes a key supply loop for motor manufacturers.
Collectively, these companies illustrate three viable strategic models: high-service rebuild specialists, scale-driven OEM suppliers, and vertically integrated material-component producers. For 2026 strategies, the choice among these models should align with customer segmentation, margin targets, and risk appetite for capital investment.
Report highlights: what PW Consulting delivers (practical contents)
Our full Commutator Market report offers the operational and strategic depth required by commercial and corporate development teams. Below are representative capabilities included in the full study:
- Market sizing and forward-looking scenarios across 2026–2032, with sensitivity analysis to tariff shocks, raw-material price swings, and demand re-rates.
- Granular supply-chain maps showing material sourcing, critical single points of failure, and near-term capacity bottlenecks.
- Competitive benchmarking and capability matrices for leading suppliers, with suggested playbooks for partnerships, M&A targets, and JV structures.
- Aftermarket and remanufacturing economics models that quantify lifetime value and optimal service-network design.
- Commercial testing protocols and quality metrics for specifying commutator components in high-reliability applications.
Importantly, the report includes primary interviews, process flow diagrams, and templated diligence checklists intended to accelerate execution for corporate development, procurement, and operations teams. To preserve commercial value for subscribers, detailed segment-by-region tables, sensitive pricing schedules, and vendor-level unit economics are reserved for the full publication.
Strategic playbook for 2026
- Prioritize aftermarket and rebuild growth. Short-term returns and margin protection are strongest in service channels where speed and certified quality command premiums.
- De-risk supply by diversifying material sources and securing long-term contracts for critical inputs—especially where tariffs expose single-shore dependencies.
- Pursue selective automation investments. Target yield improvement and inspection automation first; defer heavy-capex line expansions until near-term demand crystallizes.
- Use partnerships to bridge capability gaps. Where internal scale is insufficient, structured alliances with local rebuilders or material suppliers can provide market access without large upfront investments.
- Maintain a disciplined M&A approach. The market concentration metrics show consolidation opportunities—but target assets must offer either supply-chain control, proprietary process capability, or immediate access to high-margin aftermarket channels.
Concluding perspective and call to action
For 2026, the commutator market presents a pragmatic growth story: steady expansion, pockets of high-margin opportunity, and clear levers for value creation through supply-chain optimization and aftermarket focus. Executives who align capex, M&A, and service strategies to the market’s structural drivers will capture disproportionate returns while mitigating exposure to trade-policy and input-price volatility.
PW Consulting’s full Commutator Market report provides the datasets, scenario models, and execution-ready frameworks necessary to translate these insights into near-term actions. For the complete breakdown—including regional and application-level segmentation, vendor-level economics, and the proprietary models that underpin our forecasts—visit our report page or contact our team for a subscriber briefing.
For detailed analysis of this topic, please visit the official page: Commutator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


