



PW Consulting: Biodiesel Market Poised for 7.5% CAGR Through 2032

Biodiesel Market 2026 — Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted executive briefing that distills the strategic implications of our full Biodiesel Market study (base year: 2025) for decisions you will make in 2026. The market has shown durable expansion over the last five years — growing from approximately USD 29.8 Billion in 2020 to USD 45.0 Billion in 2025 — and our modelling indicates continued acceleration through the forecast window to reach roughly USD 73.8 Billion by 2032, at a compound annual growth rate (CAGR) of 7.5% for the forecast period. The pace, policy backdrop and competitive actions now converging make 2026 an inflection year for capacity allocation, feedstock strategy, and M&A activity.
Biodiesel Market
Why 2026 Is an Inflection Point
-
Policy clarity is materially reshaping demand signals. Recent regulatory announcements set support volumes for biomass‑based diesel that materially underpin demand forecasts into 2027, reducing one major source of uncertainty for producers and integrators. Parallel regulatory proposals in key markets continue to influence contract durations, eligibility rules for feedstocks and certification pathways — all of which change the risk profile for new investments.
Biodiesel Market -
Supply‑side momentum is visible across the value chain. Strategic expansions and capacity optimisations — from small, feedstock‑focused facility upgrades to large catalyst and bio‑chemical plants — are advancing in several jurisdictions. At the same time, nimble local producers are scaling grease‑trap and waste oil collection to secure low‑cost feedstocks.
Biodiesel Market -
Price and labour dynamics are creating both headwinds and strategic opportunity. Wholesale B100 price trajectories and reported unit prices have introduced renewed attention to short‑run margin management. Labour metrics show a sizeable existing workforce with clear upside should capacity expansion scenarios be realised, underscoring workforce planning as a pivotal execution risk.
-
Technology and product differentiation are increasingly decisive. The competitive divide between traditional transesterification biodiesel and hydrotreated renewable diesel (HVO) solutions is influencing feedstock sourcing, capital intensity and market access, particularly in jurisdictions tying incentives to lifecycle carbon performance.
What the Full Report Delivers — Practical, Transaction‑Grade Intelligence
Our full study is purpose built for executives, corporate development teams and investors who need to convert market insight into high‑confidence actions. The report contains:
-
Proprietary supply‑demand models and scenario engines that quantify outcomes under alternate regulatory, feedstock price and technology adoption assumptions for the 2026–2032 forecast period.
-
Plant‑level economics: capex/opex benchmarks, retrofit vs greenfield decision matrices, throughput optimisation levers and break‑even timelines suitable for use in investment committees and valuation models.
-
Feedstock strategy playbooks that rank resilience and margin resilience across feedstock pools and collection models, and that include contract design templates to protect margins in volatile commodity cycles.
-
Commercial go‑to‑market accelerators: offtake negotiation scenarios, blending and co‑processing opportunities, and logistics optimisations that reduce delivered feedstock costs.
-
M&A and JV heatmaps identifying target archetypes, integration risk checklists, and value capture levers supported by benchmark deal multiples and recent transaction precedent.
-
Regulatory impact assessments and compliance roadmaps tailored to major jurisdictions, including modelling of credit markets, subsidy mechanics and certification pathways tied to lifecycle carbon accounting.
-
Decision‑ready executive summaries, board presentation packs and an editable Excel model that allow you to run what‑if scenarios in minutes.
Competitive Landscape — Strategic Postures and Implications
The competitive field remains moderately concentrated: the top three players account for roughly 30% of market activity, and the top five for about 40%, leaving meaningful room for regional champions and specialist entrants to win scale. Below are the strategic profiles and near‑term considerations for industry incumbents and fast movers we track closely.
-
Archer Daniels Midland (ADM) — Vertically integrated feedstock capability and global trading presence allow ADM to optimise sourcing and manage margin volatility better than most. Their strategy favours feedstock integration and downstream offtake partnerships; they are a primary counterparty in contract negotiations and a credible acquirer of capabilities that complement their merchant business.
-
Cargill — Similar to ADM in integration, Cargill’s strength is global origination and industrial scale. Expect continued focus on blending solutions and leveraging agricultural value chains to secure long‑dated feedstock streams, especially in markets where agricultural policies intersect with renewable fuel mandates.
-
Wilmar, Bunge, Louis Dreyfus — These agribusiness majors operate with high flexibility across feedstocks and geographies. Their playbook centres on modular expansion, risk‑balanced sourcing and stepping into downstream capacity when spread economics are favourable.
-
Renewable Energy Group (REG) and FutureFuel — Independent producers that have pursued capacity aggregation and plant acquisitions. They compete on operational excellence and contractual access to feedstocks, and are likely to remain active consolidators where regulatory tailwinds make bolt‑on capacity accretive.
-
Neste — A strategic outlier focused on hydrotreated renewable diesel and high‑value, low‑carbon products. Neste’s feedstock emphasis on waste and residues, plus its high‑margin product mix, positions it to capture premium channels even as feedstock competition intensifies.
-
VERBIO, Pacific Biodiesel, Biodiesel Bilbao — Regional specialists that combine feedstock locality with agility. Recent investments in catalyst and processing capacity by some of these firms underline a two‑track industry evolution: large players scaling integrated value chains, and regional players optimising local circular‑economy feedstocks.
-
Ag Processing, Aemetis — Players with strong domestic footprints and targeted export/customer relationships. Aemetis’ fulfilment of large government orders underscores the role of state procurement in shaping export opportunities and scale economics.
Strategic Imperatives for 2026 — What Executives Should Do Now
-
Prioritise feedstock diversity and secure low‑carbon residues. Given price volatility and policy premiums tied to lifecycle carbon intensity, organisations must hedge across agricultural oils, waste oils and animal fats while investing in feedstock logistics and traceability to access premium incentives.
-
Evaluate retrofit vs new‑build decisions against refined scenario outputs. Our plant economics tools show that retrofit timing, permitting lead times and access to scarce catalysts materially alter NPV outcomes — treat these as first‑order capital allocation decisions.
-
Negotiate flexible long‑term offtakes with indexed clauses. Price volatility and regulatory changes make rigid fixed‑price contracts risky; hybrid agreements that include collars, index links and volume flex protect both producers and buyers.
-
Prepare workforce and operational scalability plans. The sector’s employment footprint can expand materially under capacity build scenarios; early workforce development reduces ramp risks and protects timelines.
-
Use targeted M&A to acquire feedstock control or premium product pathways. Bolt‑ons that secure collection networks, certification capability or catalytic processing can be more value‑accretive than greenfield capacity additions.
-
Engage proactively with regulators and commodity associations. Firms that shape implementation details around crediting mechanisms and feedstock eligibility will reduce implementation risk and preserve optionality.
How to Convert Our Findings into Board‑Level Decisions
Boardrooms need quick clarity: what investments de‑risk the most value and what moves create optionality. Use our dataset to:
-
Run three strategic scenarios (conservative, baseline, accelerated) across your asset portfolio to identify which assets to prioritise for retrofit, mothballing or expansion.
-
Stress test your contractual book against feedstock price spikes and regulatory shocks to set liquidity and covenant buffers before drafting new capital commitments.
-
Use the M&A heatmap to screen acquisition targets by strategic fit and integration complexity, and to set negotiation thresholds based on plant‑level IRRs under multiple policy outcomes.
Closing — Why PW Consulting’s Full Study Is a 2026 Strategic Must‑Have
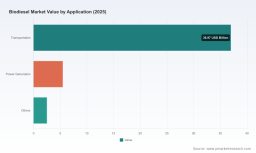
We have built this study to be decision‑centric: not a catalogue of numbers, but a toolkit for executives who must act in 2026. The executive summary above shows the contours — robust historical growth to USD 45.0 Billion in 2025, a projected expansion to roughly USD 73.8 Billion by 2032 at a 7.5% CAGR, a market that is moderately concentrated, and a competitive field actively re‑shaping capacity and feedstock strategies. Yet the most valuable insights — granular regional dynamics, application splits, plant‑level economics, contract templates and the full scenario models — are reserved for the full report and accompanying data deliverables.
For organisations planning capital deployment, M&A, or strategic repositioning next year, the difference between a good and an optimal decision will be the quality of scenario analysis and the granularity of feedstock and plant economic data. Access the full PW Consulting Biodiesel Market study for the complete datasets, proprietary models and actionable playbooks that will inform your 2026 boardroom decisions.
For detailed analysis of this topic, please visit the official page: Biodiesel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


