



PW Consulting: Resilient Flooring Market to Reach USD 55,100 Million by 2032 (6.85% CAGR)

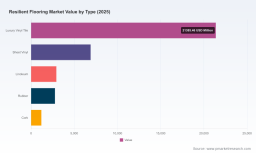
Resilient Flooring Market — 2026 Strategic Preview for Decision-Makers
Executive summary
PW Consulting's Resilient Flooring Market study surfaces the high-level facts every executive needs to orient 2026 strategy. The global resilient flooring market grew from approximately USD 27,000 Million in 2020 to USD 35,200 Million in 2025 (base year). Our forecast period (2026–2032) projects continued expansion at a compound annual growth rate (CAGR) of 6.85%, taking the market to roughly USD 55,100 Million by 2032, with an intermediate market value near USD 38,704 Million in 2026. These topline dynamics reflect sustained end-market demand, product innovation cycles, and intensifying sustainability and regulatory requirements.
Resilient Flooring Market
Why this research matters for 2026 decision-making
- Strategic prioritization: The market’s multi-year growth profile requires disciplined choices on where to invest—capacity, product innovation, premiumization or cost-led scale.
- Risk calibration: Volatility in raw-materials and shifting certification regimes mean procurement, quality and compliance actions will materially affect margins and time-to-market.
- Go-to-market optimization: Channel and product strategies must be re-aligned to capture demand in both established and emerging customer segments while protecting legacy channels.
- M&A and partnership timing: Mid-cycle consolidation and bolt-on acquisitions can accelerate capability buildouts, but target selection requires granular, region- and product-level intelligence.
Market dynamics and structural shifts to watch
The resilient flooring category has transitioned from a largely commoditized commodity into a differentiated ecosystem driven by technology, sustainability and channel sophistication. Key structural themes we detail in the full study include:
Resilient Flooring Market
- Product innovation and premiumization: Rigid-core constructions, new composite substrates and surface technologies (visual realism and durability) are expanding specification by architects, contractors and discerning homeowners.
- Sustainability as a business driver: Certifications and lifecycle declarations are moving from marketing differentiators to procurement gatekeepers. Notable standards and certifications now shaping specs include low-VOC programs (e.g., FloorScore compliance with health-based emission standards), the NSF/ANSI sustainable assessment protocols, and third-party rigid-core standards that provide end buyers with consistent assurance. These requirements are forcing investments in materials sourcing, EPDs and testing.
- Standards and certification harmonization: Industry-wide quality and sustainability programs (including newly introduced uniform standards for rigid core products) are compressing supplier differentiation around compliance and traceability—buyers increasingly expect uniform quality irrespective of origin.
- Channel evolution and experiential selling: Trade shows and live product experiences remain critical—recent exhibitions have accelerated adoption cycles for novel surfaces and brand narratives.
- Supply-chain and input cost pressures: Resin, plasticizers and logistics dynamics continue to create margin compression, favoring manufacturers that combine scale with nimble product development.
Competitive landscape — what incumbents are doing
The market is shaped by legacy flooring manufacturers, vertically integrated players and specialty brands that compete on product design, distribution reach and technical certification. While we do not disclose segment-level revenue tables in this preview, the competitive fabric is characterized by a handful of large players complemented by regional specialists and innovative challengers. Recent public moves illustrate these dynamics:
Resilient Flooring Market
- MSI (Orange, California) — A leading supplier whose trade-show presence and portfolio breadth underline a strategy of broad-market coverage and channel intensity. MSI continues to use flagship exhibitions to launch surface innovations and engage distribution partners.
- LX Hausys (Adairsville, Georgia) — The company’s HFLOR brand has been active on the trade-show circuit and strengthened institutional ties by joining key industry bodies in 2026, signaling a push to accelerate credibility and market access in North America.
- Shaw Industries and Mohawk Industries (Dalton, GA; Calhoun, GA) — Large incumbents that combine R&D scale, brand recognition and broad distribution. Both remain central to channel standards-setting and trade-event leadership.
- Karndean Designflooring and Amtico International (United Kingdom) — Premium design-led players focused on specification channels, high-margin residential and commercial segments, and cross-border brand positioning.
- Tarkett and Armstrong Flooring (France; Lancaster, PA) — Global manufacturers prioritizing sustainability credentials, homogeneous product ranges and lifecycle disclosure to win institutional procurement.
- Roppe Corporation and The CLASSEN Group — Regional and manufacturing specialists that strengthen portfolio completeness (base/trim, complementary products) or expand geographic reach via membership in industry associations.
These firms are actively exhibiting, standardizing and aligning with certification programs — behaviors that both raise category expectations and create barriers to new entrants that lack compliance or scale. In the aggregate, market concentration favors established brands, but white-space opportunities remain for innovators with strong sustainability, installation-support and channel strategies.
Recent, decision-relevant developments (selected)
- Major trade-show activity in 2026 has been a de facto product-launch calendar for the category—industry-leading exhibitors used events to showcase surface innovation and new rigid-core lines.
- Manufacturers are accelerating formal association membership and adopting third-party certification programs to shorten procurement cycles with specifiers and institutional buyers.
- Standardization efforts around rigid-core quality and sustainability create both compliance burdens and differentiation pathways—organizations that invest early in verification will see faster specification wins.
What the PW Consulting report delivers (practical, actionable content)
The full report is designed as an operational playbook for 2026 strategy. Highlights include (excerpt):
- Strategic scenarios for 2026–2032 with demand-sensing outputs and sensitivity testing versus raw-material and channel shocks.
- Go-to-market playbooks by product archetype and buyer persona, including distributor/discretionary renovation channel tactics and commercial-specification engagement models.
- Procurement and margin-improvement levers—cost-engineering templates, routed BOMs and supplier consolidation strategies.
- Regulatory and certification roadmaps with step-by-step actions to achieve key seals and declarations required by institutional buyers and LEED-like frameworks.
- M&A screening framework and prioritized capability gaps—identify targets that accelerate product technology, geographic reach or certification capacity.
- Operational readiness assessments: capacity planning, installation labor force modeling, and SKU rationalization playbooks for SKU-heavy portfolios.
- Commercial intelligence—channel economics, pricing elasticity models and promotional effectiveness metrics validated through primary interviews and trade-show feedback loops.
Note: This preview intentionally omits the granular segmentation tables, regional revenue splits and application-level figures that are included in the full deliverable—those datasets are available exclusively in the report download and interactive dashboards.
How to use this intelligence in 2026 — recommended next steps
- C-suite (strategy & finance): Re-evaluate capital allocation to prioritize product lines that meet new sustainability thresholds and deliver higher specification win rates. Use our M&A screening to accelerate capability acquisition within 6–12 months.
- Commercial leaders: Implement differentiated pricing pilot programs and strengthen specifier relationships through targeted certification investments. Re-align incentive structures for distributor partners based on margin contribution and installation support.
- Product and R&D teams: Fast-track certifications and EPD generation for high-potential SKUs. Prioritize rigid-core and surface-coating innovations that reduce warranty claims and simplify installation.
- Operations & procurement: Run a 90-day supplier risk audit and a 6–18 month procurement hedging program informed by our input-cost scenarios. Consider nearshoring or contractual indexing where appropriate.
- Investors & PE sponsors: Use our scenario outputs to stress test IRR cases under alternative commodity and standardization outcomes; prioritize targets with verified certifications and demonstrable specification pipelines.
Methodology and credibility
The analysis is built on a synthesis of primary interviews, company disclosures, trade-show observations, association announcements and third-party certification sources, anchored to historical data for 2020–2025 and a forecast window of 2026–2032. We combine bottom-up shipment and pricing models with top-down demand drivers to produce robust scenario outputs and a conservative base case. Regulatory inputs include recognized standards for emissions and sustainability that are actively affecting procurement and product claims.
Conclusion — why act now
The resilient flooring market’s steady compound growth, clear movement toward standardized sustainability, and concentrated competitive set create a narrow window for strategic action in 2026. Companies that align product development, certification investments and channel economics now will translate market growth into durable margin expansion and market share gains. Those that wait risk ceding specification-led channels to better-prepared competitors.
Next step
This preview intentionally showcases direction and strategic implications while withholding the granular regional, application and product-level datasets that underpin tactical decisions. Access the full PW Consulting Resilient Flooring Market report and interactive dashboards to obtain the segmented revenue tables, bespoke scenario outputs, and executable playbooks referenced above.
For detailed analysis of this topic, please visit the official page: Resilient Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


