



PW Consulting: Circular Saw Blades Market to Top USD 15,621.94 Million by 2032 (4.4% CAGR)

Circular Saw Blades Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting presents a sector-first briefing that distills the actionable intelligence executives need to navigate the Circular Saw Blades market through 2026 and beyond. This introduction previews the analytical depth and decision-grade outputs in our full Circular Saw Blades Market study (base year: 2025; forecast period: 2026–2032) — highlighting why this market warrants strategic attention, what is changing, and which moves separate winners from the rest.
Circular Saw Blades Market
Why this market matters in 2026
The circular saw blades market has demonstrated steady expansion through the first half of the decade. From 2020 to 2025 the industry expanded consistently, reaching an estimated market size of approximately USD 11,548 million in 2025. Our forecast projects the market to continue growing at a 4.4% compound annual growth rate (CAGR) across the 2026–2032 horizon, approaching an aggregate in the mid-teens of USD billions by 2032. That trajectory reflects a mix of end-market demand resilience, incremental product innovation, and shifting buyer priorities such as cutting efficiency, safety, and lifecycle cost.
Circular Saw Blades Market
For executives contemplating resource allocation in 2026 — whether R&D budgets, manufacturing footprint, M&A appetite, or commercial go-to-market — the combination of modest but reliable growth and high market concentration (the top three players account for a large share of the market and the top five an even larger share) creates a specific strategic logic: scale and differentiation win, but niche specialization and operational agility unlock outsized returns in pockets of the value chain.
Circular Saw Blades Market
Market dynamics shaping strategic choices
-
Regulation and safety: New and updated standards (e.g., ISO 19085‑9 and regional equivalents) and active regulatory consideration of injury-mitigation features for table saws are redefining product validation timelines and compliance costs. Firms must move from ad hoc compliance to product development roadmaps that integrate certification milestones into launch plans.
-
Input-cost inflation: Raw material inflation — particularly in carbide and specialty steels — is projected to influence pricing and margin dynamics in 2026, with industry sources pointing to single-digit percentage pressure on blade costs. Manufacturers with hedging programs, vertical integration options, or alloy-substitution capabilities will enjoy immediate margin resilience.
-
Acoustic and user-experience innovation: Practical advances such as idling noise reductions (industry examples show up to ~6 dB reductions in controlled comparisons) and anti-vibration geometries are shifting procurement criteria for high-end OEMs and professional end-users. These attributes increase perceived value and create levers for premium pricing.
-
Tool electrification and thin-kerf trends: The broader electrification of power tools — especially cordless platforms — is driving demand for blades optimized for thin-kerf performance, reduced kickback, and battery-friendly cutting efficiency. Suppliers aligned with major power-tool OEM programs can capture disproportionate share in fast-growth subsegments.
Competitive landscape — who matters and why
The competitive field is a mix of global powerhouses, regional specialists, and technology-focused niche players. Market concentration is high: the top three firms account for a substantial portion of global revenue, and the top five capture an even larger share. That structure creates two pragmatic plays for challengers and incumbents alike: pursue scale through volume and channel control, or invest in differentiated technologies and service models that protect margin.
-
Global tool and component leaders: Brands such as Bosch, Makita, DeWalt, and Festool leverage integrated portfolios and deep OEM relationships to bundle blades with tools, pushing premiumization through optimized blade-tool pairings, surface treatments, and thin-kerf designs for cordless platforms.
-
Specialist performance innovators: Companies like Diablo Tools, Freud, and Amana Tool focus on advanced carbide blends, anti-vibration geometries, and application-specific tooth designs aimed at cabinetry, laminates, and composite substrates — enabling premium pricing and strong channel loyalty among professional end-users.
-
Industrial and metal-cutting specialists: Firms such as Lenox Tools, The M.K. Morse Company, and Specialty Saw dominate heavy industrial, metal-cutting and high-throughput applications with engineered tooth geometry, HSS/TCT options, and products for automated cutting cells. Their value proposition stresses durability, cycle-time reduction, and predictable tool life.
-
High-volume Asian manufacturers: Companies originating from Asia (including notable Chinese producers) have scale advantages in commodity and industrial-grade blades — competing on cost, distribution reach, and speed-to-market for standard formats, while selectively moving up the value chain via product enhancements.
-
Precision and panel specialists: European manufacturers and medium-size players focus on panel, track saw, and woodworking niches where finish quality and noise/vibration performance are premium decision drivers. These players often lead in compliance with new woodworking safety standards.
Recent trade-show presence and exhibition calendars (WIRE&TUBE, TUBE, AMB, IMTS and regional machinery fairs) underscore an active product-development and partnership cycle across the industry — a useful proxy for where R&D dollars and distribution pushes will concentrate in 2026.
What our full report delivers (practical outputs)
PW Consulting’s full Circular Saw Blades Market study is organized to equip strategy teams with executable plans rather than high-level commentary. Key deliverables include:
-
Market-sizing and forecast models (2020–2025 historicals; 2026–2032 forecasts) with scenario outputs and sensitivity to input-cost swings.
-
Competitive benchmarking matrices covering product portfolios, channel strategies, pricing positioning, and technological differentiators for the leading 20+ vendors.
-
Commercial playbooks: go-to-market options for OEM partnerships, aftermarket distribution, and direct-to-professional approaches, including expected ROI curves for each route.
-
Regulatory impact analysis and compliance roadmaps tied to recent standards and proposed rules, with estimated certification timelines and cost envelopes.
-
Supply-chain heatmaps and raw-material risk assessments — including mitigation levers (strategic stock, multi-sourcing, alloy substitution) — with modeled P&L impact under different inflation scenarios.
-
Technology and innovation opportunities: prioritized R&D investments (e.g., coatings, carbide blends, anti-vibration designs, noise reduction) and recommended test/validation protocols aligned with certification pathways.
-
M&A and partnership target shortlist based on capability gaps, geographic priorities, and scale thresholds (including integration risk scoring and value-creation timelines).
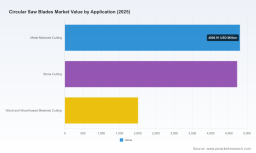
Note: This briefing intentionally omits granular segment-by-segment revenue tables and region-level percentage splits — those detailed segment matrices and downloadable datasets are available in the full report and on our source webpage.
Strategic recommendations for 2026 (what to do this year)
Our analysis points to a small set of high-impact actions that firms can execute in 2026 to protect margin and accelerate growth:
-
Lock supply and diversify inputs: Implement multi-tier sourcing for carbide and specialty steel and negotiate indexed contracts or hedges to absorb the expected input-cost pressure. Rapidly validate alloy substitutes in pilot lines to reduce exposure to single-supplier disruptions.
-
Prioritize compliance-enabled product launches: Fast-track a product family that targets new ISO regulatory requirements and expected active-safety rules. Early certification is a competitive moat for OEM and retail distribution channels.
-
Move up the value chain with performance services: Offer blade lifecycle management (sharpening, analytics, return-for-recycle) and bundled warranties for professional segments to convert one-time buyers into recurring revenue customers.
-
Align with electrification trends: Co-develop thin-kerf, low-friction blades with leading cordless tool OEMs to secure preferred-supplier status and jointly market efficiency gains to value-conscious contractors.
-
Pursue targeted M&A or JV plays: With high market concentration, bolt-on acquisitions that fill capability gaps (coatings, diamond technologies, speciality HSS) deliver faster returns than greenfield R&D. Prioritize targets with validated IP and established OEM contracts.
Key indicators to watch in 2026
-
Raw material price indices for carbide and high-grade steel, and the tenor of supplier lead-times.
-
Regulatory milestones and public comment timelines for proposed safety rules affecting table saws and bench-mounted equipment.
-
Major power-tool OEM product roadmaps and planned announcements on cordless system upgrades or new tool-platform launches.
-
Trade-show activity and new product introductions at the machinery and woodworking exhibitions that typically set product and partnership trends.
-
Consolidation signals: M&A activity among the top players or targeted strategic partnerships that reconfigure distribution channels.
Concluding perspective
For 2026, the Circular Saw Blades market presents a classic strategic trade-off: steady macro growth and concentrated incumbency create stable profit pools, yet continuing product innovation, regulatory shifts, and raw-material volatility open windows for disruptive entrants and well-timed incumbents. Executives who combine supply-chain rigor, regulatory foresight, and focused product differentiation (either via technology or embedded services) will capture the premium margin streams as the market evolves.
PW Consulting’s full report converts these strategic themes into executable plans — including the granular segment matrices, regional dynamics, and supplier-level data intentionally withheld in this preview. Access the complete study for the segment-level forecasts, downloadable datasets, and vendor scorecards that will enable precise 2026 capital allocation and commercial decisions.
For detailed analysis of this topic, please visit the official page: Circular Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


