



PW Consulting: Valves Market to Reach USD 126.8 Billion by 2032 at 5.5% CAGR

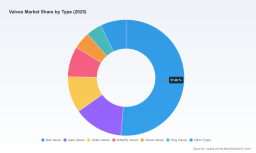
Valves Market 2026 Strategic Outlook — A PW Consulting Preview
As companies prepare capital allocation, product roadmaps, and M&A priorities for 2026, the valves market has re-entered a phase of structurally predictable growth underpinned by regulatory tightening, digital adoption and a renewed capex cycle in energy and infrastructure. This preview distills the strategic implications of PW Consulting’s full Valves Market research (base year 2025; forecast period 2026–2032) and explains how executives should convert macro momentum into defensible revenue and margin gains. We demonstrate analytical depth while reserving detailed segment-level metrics for the full report — think of this as the trailer that tells you where to focus and why to download the movie.
Valves Market
Market sizing and trajectory — what the headline numbers mean for 2026 choices
After steady expansion during 2020–2025, the global valves market reached roughly USD 87 billion in our 2025 base year and is on a trajectory to exceed USD 120 billion within the next investment cycle. The forecast period reflects a compound annual growth rate of approximately 5.5%, driven by blend of retrofit demand, greenfield energy projects, and rising aftermarket services. For decision makers, this is a market large enough to sustain both high-volume OEM plays and specialist, margin-rich niches — but the arithmetic favors companies that convert product leadership into services, compliance solutions, and digital monetization.
Valves Market
Why 2026 is a pivotal inflection point
- Regulatory acceleration: Tighter emissions and fugitive-loss standards in major markets are moving retrofit cycles forward and creating new demand for higher-spec, certified designs.
- Service monetization: As installed bases age, operators shift budget from one-off purchases to lifecycle and performance contracts — boosting recurring revenues for providers that can offer diagnostics, spares and guaranteed uptime.
- Digital at scale: The convergence of IoT-enabled actuators, cloud analytics and standardized protocols is making “smart valve” upgrades commercially viable across industrial segments.
- Supply chain recalibration: Post-pandemic sourcing strategies, regional content rules and steel/raw-material volatility are encouraging localized assembly and just-in-sequence distribution models.
Core market dynamics and strategic implications
- Standards and compliance are demand multipliers: International and industry standards (including widely adopted API and ASME specifications, and fugitive-emissions protocols) are no longer optional considerations; they determine procurement eligibility for major projects. Suppliers that certify product lines and embed compliance documentation into their digital offering reduce buyers’ transaction friction and accelerate procurement cycles.
- Retrofit-led growth creates margin arbitrage: Retrofitting legacy installations with emission-compliant and digitally instrumented valves yields higher gross margins than commodity new-builds. Manufacturers and service providers should prioritize retrofit kits, flange-to-flange drop-in solutions and modular actuator packages.
- Aftermarket services are the durable moat: Warranty packages, predictive maintenance subscriptions, and on-site calibration services convert episodic revenues into durable cashflows. OEMs should convert field performance data into priced service tiers.
- Materials and sustainability shape product roadmaps: Demand for lower-carbon materials and compliance with environmental norms drives R&D toward alternative alloys, coatings and re-manufacturing models that lower lifecycle emissions.
- Digital enablement changes buyer-seller economics: Value-adding features — remote diagnostics, health scoring, and lifecycle cost models — reduce total cost of ownership for buyers and increase wallet share for suppliers.
Competitive landscape — clusters to watch (and what they signal)
The market structure combines global OEM platforms, regional specialists, and technology-focused niche players. Rather than treat each firm as an isolated rival, executives should view competition through functional clusters and capability ownership:
Valves Market
- Global OEM platforms (e.g., Emerson, Flowserve, Baker Hughes, Crane, Velan): These companies control broad portfolios across control valves, severe-service designs and integrated flow systems. Their advantages are scale, installed-base access and systems integration. Expect continued investment in service networks and digital layers to defend margins.
- Regional and vertical specialists (e.g., KSB, KITZ, AVK, Victaulic): Firms with deep domain or geographic expertise can outcompete on localization, regulatory certification and aftermarket responsiveness. They are attractive partners or targets for bolt-on strategies to close service delivery gaps.
- Controls and actuation leaders (e.g., Rotork, Rexa, SAMSON, Spirax Sarco, Valtorc): As valves become nodes in automated control loops, actors that control the actuator–positioner–software stack gain pricing power. Integration plays that bundle hardware with performance guarantees will win procurement incumbency.
- Niche and high-performance specialists (e.g., ValvTechnologies, Trillium Flow, Bray): These players capture high-margin work in severe-service, metal-seated designs and specialty segments. They are often the source of technology licensing or acquisition targets for larger OEMs seeking performance credentials.
Strategic takeaway: 2026 winner profiles are those who combine product and service portfolios with digital credentials, regulatory compliance and a clearly articulated aftermarket strategy. Pure-play volume suppliers without a service and compliance roadmap will see margin pressure.
Signals and recent vendor activity to monitor
- Assorted 2025–2026 product introductions — from compact solenoid valves to enhanced dust-excluding components and updated digital catalogs — demonstrate suppliers are optimizing for space-constrained, lifecycle-cost-sensitive use cases.
- Standards-driven procurement is intensifying: broad voluntary adoption of API testing protocols and specific emissions standards is raising the bar for acceptance into major capital programs.
- Incremental product improvements (better ingress protection, compact actuation, updated digital interfaces) are converging into modular upgrade offerings, enabling staged retrofit paths that reduce upfront CAPEX for end users.
What the full PW Consulting Valves Market report includes (practical, executable content)
- Comprehensive market sizing and high-resolution forecast (2026–2032) with scenario sensitivity to energy, regulation and materials price swings — enabling capex vs. retrofit break-even analysis.
- Segment-level growth drivers and pain points (by valve family, by application cluster and by region) plus prioritized pockets of opportunity — presented as action maps rather than raw tables.
- Go-to-market playbooks for OEMs, distributors and service providers: product positioning, pricing migration strategies, and channel redesign templates.
- Vendor scorecards and capability heatmaps that rank firms on technology, scale, service footprint and compliance readiness — to inform partnership and M&A screening.
- Operational playbooks for procurement and asset owners: retrofit decision trees, TCO calculators and supplier selection frameworks that lower selection risk and accelerate deployment.
- M&A target shortlists and integration checklists tailored to buyers seeking scale in services, digital, or regional penetration.
- Regulatory compliance roadmaps mapped to likely enforcement timelines and procurement windows — critical for synchronization of product certification activities.
Practical recommendations for 2026 decision-makers
- CEO / Board: Prioritize acquisition and partnership capital toward aftermarket capabilities and digital analytics. Fund a 12–18 month program to convert 10–15% of new sales into subscription or service contracts.
- Product & R&D: Fast-track certification projects tied to the most consequential emissions and safety standards in your priority markets. Invest in modular, retrofit-compatible actuator interfaces to enlarge addressable installed base.
- Sales & GTM: Reorient incentives to secure multi-year service agreements and to bundle digital health solutions with hardware sales. Implement pilot outcome-based contracts in two strategic accounts before year-end.
- Supply Chain & Procurement: Implement dual-track sourcing for critical components and localize final assembly where regional content or lead time concerns constrain tender success.
- Investors & PE: Focus diligence on companies with >30% renewals or service revenue and those with defensible data assets (field telemetry, failure modes). Valuation premia will accrue to firms with predictable, recurring cashflows.
Closing: what to do next
For executives who must make capital, product or M&A decisions in 2026, the immediate priorities are clear: lock in compliance pathways, convert installed bases into recurring revenue streams, and accelerate digital feature delivery that demonstrably reduces TCO for end users. The market offers both scale and high-margin niches — but the window to secure leadership in retrofit and digital services is narrow.
PW Consulting’s full Valves Market report (base year 2025; 2026–2032 forecast) contains the granular segment analysis, vendor benchmarking and executable playbooks required to convert the macro trends outlined above into near-term action. Access the complete study on our website to obtain the detailed forecasts, segment breakouts, and transaction-ready diligence materials withheld from this preview.
For detailed analysis of this topic, please visit the official page: Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


