



PW Consulting: Piezoelectric Ceramics Market Poised for 5.5% CAGR Through 2032

Piezoelectric Ceramics Market — Strategic Outlook for 2026
Executive snapshot
As global manufacturers recalibrate product roadmaps to meet electrification, miniaturization, and sustainability priorities, piezoelectric ceramics move from niche enabler to strategic component class. Our new PW Consulting study (base year 2025; historical window 2020–2025; forecast 2026–2032) shows the market recovering from near-term volatility and re-accelerating at a compound annual growth rate (CAGR) of 5.5% through 2032. The total market has grown from roughly USD 1.25 billion in 2020 to about USD 1.59 billion in 2025, and our central forecast places the market at approximately USD 2.27 billion by 2032. Market concentration is meaningful: the top three players account for nearly half the market by revenue, while the top five control well over 60%, creating a structure that favors scale in manufacturing, technical IP, and integrated supply chains.
Piezoelectric Ceramics Market
Why this research matters for 2026 decision-making
-
Timing investments. The market inflection we identify in early 2026 is driven by simultaneous demand from automotive sensors, medical ultrasound upgrades, and industrial automation — each offering different margin and scale profiles. Executives must choose between capacity-led strategies and targeted high-margin product plays; our report maps the trade-offs with quantified scenarios.
Piezoelectric Ceramics Market -
Technology roadmaps. Material choices (PZT vs. lead‑free chemistries, single crystal options, polymer composites) are the primary determinant of product performance, regulatory exposure, and unit cost. The study provides a technology-readiness matrix that allows R&D and procurement teams to prioritize projects with the fastest ROI under realistic regulatory timelines.
Piezoelectric Ceramics Market -
Supply-chain resilience. Recent raw-material assessments show that feedstocks for lead-free variants currently attract higher unit costs than conventional PZT mixes. Combined with critical-mineral designations for base metals, this dynamics forces near-term sourcing shifts that we model across multiple procurement strategies.
-
Competitive positioning. With CR3 and CR5 metrics indicating mid-to-high concentration, mid-sized players can still carve defensible niches through specialization, co-development agreements, and regional proximity to key OEMs. The report gives playbooks for each position on the market map.
Macro and micro dynamics in play
The historical series (2020–2025) in our study captures a classic recovery pattern: initial demand growth, a mid-period correction, and an engineering-driven rebound. Noteworthy is a modest dip around 2023 followed by accelerated adoption as new end-market designs incorporated piezoceramic components into sensor fusion stacks and medical-imaging upgrades. Looking forward to 2026–2032, the market trajectory aligns with three structural drivers:
-
Electrification and sensing proliferation in mobility: increased adoption of advanced sensing for EV powertrain control and ADAS has created persistent demand for robust, high-performance piezo materials.
-
Medical modernization: ultrasound and precision therapeutic devices favor ceramics with predictable behavior at scale; clinical adoption cycles are lengthier but yield premium pricing for qualified suppliers.
-
Regulatory transition and materials substitution: legislative pressure (e.g., RoHS frameworks) creates both risk and opportunity. Exemptions remain for some lead‑containing applications where no viable substitutes exist at parity, but R&D investments in lead‑free families are accelerating.
Practical implications for corporate strategy
For 2026, we recommend executives focus on three executable priorities that our analysis proves to drive value under multiple scenarios.
-
Allocate capital with staged optionality. Greenfield capacity investments should be phased with modular production lines that can pivot between PZT and lead‑free formulations. This preserves near-term throughput while protecting against regulatory shocks.
-
Forge targeted co-development agreements. Leading technology shifts are now co-developed with OEMs (example: recent partnerships between materials specialists and an automotive OEM). Co-funded R&D reduces commercialization risk and secures offtake commitments.
-
Build cost-to-serve intelligence. Our cost-per-unit models demonstrate that raw-material sourcing and sintering efficiency drive >60% of incremental margin expansion potential. Procurement teams should deploy value-stream analyses and supplier scorecards tied to technical KPIs.
Competitive landscape — who moves first wins
The competitive set combines specialized manufacturers, integrated electronics groups, and defense/prioritized suppliers. Each archetype brings different offensive and defensive moves:
-
Specialist ceramics manufacturers (e.g., established European and US firms) continue to dominate high-performance and customized solutions, benefitting from deep process knowledge in PZT and barium titanate variants.
-
Integrated electronics groups and large component suppliers use vertical integration to capture higher value on end-products, leveraging scale and cross-selling into adjacent component lines.
-
Regional and niche players focus on rapid prototyping, short lead times, and service differentiation for medical and defense customers where certification and qualification create stickiness.
Across these categories, several recent company moves highlight strategic themes we discuss in the full study:
-
Product innovation and lead‑free breakthroughs: a European specialist announced a commercially viable lead‑free piezoceramic component and opened collaboration channels with OEMs to accelerate adoption — a classic first‑mover position that shortens the commercialization timeline for substitutions where feasible.
-
Capacity scaling in high-performance segments: another key manufacturer invested in a dedicated facility for high‑power and ultrasonic components, signaling confidence in demand durability for premium applications.
-
Strategic partnerships with automotive OEMs and capacity expansions in sensor production reflect the sector’s pivot to mobility sensors and the industrial automation wave.
Regulation, raw materials, and supply risk — the new operating environment
Regulatory and raw‑material signals are shaping strategic options. The European RoHS framework continues to restrict lead in many electronics use-cases, though exemptions persist where lead-based piezoceramics have no functional substitute. At the same time, trade instruments and tariff schedule updates reflect shifting global trade dynamics. From a supply perspective, raw materials for lead‑free ceramics are currently costlier than traditional PZT feedstocks; this gap is a central variable in our cost-sensitivity scenarios. Additionally, recent critical‑mineral designations underscore potential future constraints and geopolitical exposure for certain conductive and functional material inputs.
What the PW Consulting report contains (practical deliverables)
Our study is structured to move from insight to action. Key deliverables include:
-
Market sizing and 10+ year forecast with scenario bands calibrated to material‑cost, regulation, and demand shocks.
-
Technology-readiness and substitution matrix showing where lead‑free alternatives are commercially viable, near-term promising, or still early-stage.
-
Supplier landscape and capability mapping, including manufacturing footprints, typical lead times, and qualification barriers for medical and defense buyers.
-
Commercial playbooks: go-to-market strategies for scale players, premium specialists, and challengers — including pricing strategies, channel choices, and co-development templates.
-
Investment decision tools: capex calculators, break-even analyses for capacity lines, and acquisition screening filters tailored to size and technology focus.
-
Regulatory impact matrix and mitigation plans that translate compliance timelines into actionable procurement and product-development milestones.
-
Risk heatmaps covering supply, regulatory, and demand-side exposures with prioritized mitigation actions.
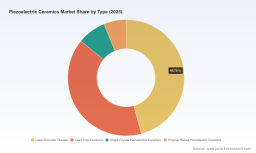
Note: in keeping with our “preview” approach, detailed segment-level tables (region, type, and application splits) and company-specific revenue breakdowns are withheld from this summary; they are included in the full report and accompanying data pack available through our web portal.
How to use this research in 90 days
-
Rapid diagnostic (0–30 days): Run a gap analysis of your current product portfolio vs. the technology-readiness matrix in the report. Identify one material substitution that can be de‑risked through co-development.
-
Operational mobilization (30–60 days): Prioritize supplier engagements using our procurement playbook and risk heatmap. Consider staged purchase agreements or strategic inventory for inputs flagged as supply‑constrained.
-
Capital and commercial planning (60–90 days): Finalize investment staging using the capex calculator scenario that aligns with your demand assumptions and margin targets.
Final perspective
Piezoelectric ceramics are positioned at the intersection of material science, regulatory change, and accelerating end-market demand. Our analysis shows a clear growth path from the current market base to a materially larger market by 2032 under the central 5.5% CAGR scenario, but the strategic winners will be those who combine technical depth, supply-chain agility, and regulated‑market savvy. PW Consulting’s report delivers the granular, actionable intelligence required to make those calls in 2026 — including scenario tools, supplier maps, and commercial playbooks. For decision-makers evaluating capacity, M&A, or R&D allocation this year, the full report and the data package are the fastest way to convert market insight into defensible strategy.
For detailed analysis of this topic, please visit the official page: Piezoelectric Ceramics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


