



PW Consulting: Industrial Silica Sand Market to Reach USD 25.0 Billion by 2032

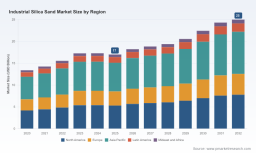
Industrial Silica Sand Market — Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-centric preview of our new Industrial Silica Sand Market study (base year 2025). This briefing distills the research’s strategic value for executives, investors, and supply‑chain leaders preparing for 2026 commitments. The market entered 2025 at roughly USD 17.0 Billion (base year 2025) after a post‑pandemic recovery, and our forward model projects a steady expansion at a compound annual growth rate (CAGR) of approximately 5.7% through the 2026–2032 forecast window — reaching an anticipated market scale in the high‑20s by 2032. The analysis that follows highlights the forces driving that trajectory, the structural competitive dynamics, and the high‑return actions companies should prioritize in 2026.
Industrial Silica Sand Market
Why this research matters for 2026 decisions
-
Capital allocation: The sector is capex‑intensive. Our report quantifies break‑even horizons for greenfield processing facilities, brownfield upgrades, and logistics investments under multiple price scenarios.
Industrial Silica Sand Market -
Pricing strategy and margin protection: With raw material sourcing and regulatory costs evolving, the study provides price elasticity models and segmentation‑level margin sensitivities necessary to design value‑based pricing and pass‑through mechanisms.
Industrial Silica Sand Market -
M&A and consolidation playbook: Concentration metrics show meaningful scale benefits for large producers; we outline acquisition targets, synergies, and integration risks tailored to strategic buyers and financial sponsors.
-
Regulatory & ESG risk mitigation: Recent policy shifts and occupational safety scrutiny materially affect operating cost and permitting timelines—our regulatory scenario analyses quantify the short‑ and medium‑term impact on supply and costs.
-
Commercial strategy: Demand drivers across glass, foundry, hydraulic fracturing, and industrial applications shift at different paces. The report helps prioritize go‑to‑market moves without exposing the proprietary segment splits summarized in the full study.
Underlying market dynamics — a synthesized view
The market has shown resilience since 2020, with recovery dynamics shaped by downstream cycles in construction, automotive glass demand, foundry throughput, and energy sector investment. Our base scenario assumes normalized demand growth across end uses, supported by modest increases in technical glass and specialty applications that favor higher‑grade sand. Key raw inputs remain quartz‑rich sand and sandstone; their availability, grade consistency, and proximity to processing and logistics networks are core determinants of project economics.
On the supply side, the landscape reflects a mix of large vertically integrated players and numerous regional producers. U.S. geological data indicates hundreds of active operations and well over a hundred companies in production — a structure that supports localized pricing power in some corridors while leaving room for scale benefits among the largest producers. Notably, our market concentration analysis shows that the top three firms capture a majority share of industry revenues, with the top five increasing that share materially — a structural reality that informs both competition and consolidation opportunity sets.
Regulatory inflection points and operational constraints
-
Tax and fiscal changes: Recent actions in certain U.S. states have reclassified some processed sands for tax purposes; companies must model incremental effective tax costs and develop contractual strategies to preserve margins.
-
Occupational health regulations: Heightened focus on crystalline silica exposure in 2025 has introduced additional monitoring, control, and compliance costs. Our impact matrix ranks jurisdictions and facility types by regulatory exposure and remediation lead time.
-
Permitting and environmental approvals: New permitting lead times and community engagement expectations are extending project timelines. We provide a decision tree to prioritize processing upgrades versus permitting new mines.
Competitive landscape — strategic profiles and recent moves
The competitive field combines multinational minerals groups and specialized regional players. Core firms included in our benchmark set are leaders in high‑purity sands, processing scale, and distribution networks. Each player exhibits a distinct strategic posture:
-
Large integrated producers leverage scale in mining, processing, and logistics to capture margin and serve capital‑intensive end markets. Recent capacity additions in key U.S. basins and new processing footprints underscore a push to lock in supply for premium industrial grades.
-
Mid‑sized and regional specialists focus on niche grades, proximity to local glass and foundry customers, and service‑quality differentiation. These firms can be attractive bolt‑on targets for acquirers seeking geographic or grade‑specific coverage.
-
International producers and European quartz specialists maintain competitiveness via technology, vertical integration into certain industrial end markets, and long‑standing customer relationships in high‑value glass and ceramics segments.
Two recent industry developments illustrate the dynamic environment: one major producer announced an expansion of processing capacity with a new facility in a key U.S. state, and another announced a price adjustment program targeting industrial products to take effect mid‑2026. These moves reinforce a market rebalancing in which capacity additions and pricing actions interact closely with downstream demand trends and regional policy shifts.
What the PW Consulting report contains — practical, transaction‑ready deliverables
-
Proprietary market model (2020–2032): A transparent, auditable model including historical reconciliation, base/alternate scenarios, and a sensitivity engine for price, demand, and cost inputs.
-
Supply‑demand matrices at plant and basin level: Facility‑level capacity, utilization, and throughput curves that allow you to simulate disruptions, rail/logistics constraints, and brownfield opportunities.
-
Plant cost curves and margin band maps: Detailed unit‑cost benchmarking across different processing configurations and feedstock qualities to prioritize efficiency investments.
-
Price elasticity and contract playbook: End‑market price drivers, pass‑through mechanisms, and recommended contractual clauses for captive buyers and toll processors.
-
M&A and inorganic growth toolkit: Target screening templates, synergy calculators, and integration risk checklists tailored to buyers and PE sponsors.
-
Regulatory & ESG impact assessment: Jurisdictional risk scoring, occupational‑health remediation cost templates, and recommended community engagement frameworks.
-
Commercial go‑to‑market playbooks: Customer segmentation, logistics optimization, and premium product strategies for specialized grades.
Actionable plays for executive teams in 2026
-
Prioritize portfolio upgrades that improve yield and reduce fines—small improvements in product recovery drive outsized margin gains across the cost curve.
-
Lock in feedstock access with multi‑year supply agreements that include grade and logistics clauses; where possible, co‑invest in upstream reserves to de‑risk feedstock quality.
-
Revisit pricing architecture to embed transparent escalators tied to input indices and regulatory cost pass‑throughs; pilot these in select customer segments before broader rollout.
-
Use targeted M&A to secure regional logistics hubs and processing capacity rather than incremental mine acreage alone—control of throughput matters more than raw acreage in the near term.
-
Make worker safety and dust suppression investments non‑negotiable: they reduce permit risk, lower insurance and compliance costs, and improve time to market for expansions.
-
Run three‑scenario contingency planning (base, accelerated demand, regulatory shock) to stress‑test capex and liquidity plans, with clear trigger points for execution.
How PW Consulting’s deliverables accelerate decision-making
Our study is designed for immediate application. Subscribers receive the full model and appendices, including downloadable Excel tools: a plant‑level ROI calculator, a target screening matrix for M&A, a regulatory impact simulator, and a commercial price elasticity dashboard. We also provide a short, executive‑level memo that translates model outputs into recommended 90‑, 180‑, and 360‑day actions tailored to producers, processors, and institutional investors.
Note: This preview intentionally omits the granular regional, product‑grade, and application split tables that form the core proprietary intelligence of the full study. Those detailed segmentations, company‑level KPIs, and the complete dataset are available only in the subscription report and are essential for transaction execution and high‑confidence capex decisions.
For teams preparing budgets, negotiating supply contracts, or evaluating M&A targets in 2026, the full PW Consulting Industrial Silica Sand Market study provides the models, market maps, and playbooks necessary to make informed, defensible decisions. Contact our research desk to access the complete dataset, scenario models, and bespoke advisory options tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Industrial Silica Sand Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


