



PW Consulting Market Insights: Carbon-Graphite Brush to Reach USD 257M by 2032

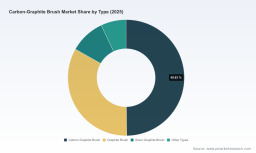
Carbon-Graphite Brush Market: Strategic Outlook for 2026 Decision-Makers
Executive overview
As global industrial systems and mobility architectures enter a new phase of electrification and durability-driven design, the carbon-graphite brush market is quietly evolving from a commoditized consumables market to a specialized, design-driven component industry. PW Consulting’s latest study (base year 2025) maps that transition and frames the concrete strategic choices that matter for executives preparing budgets, product roadmaps, and M&A pipelines in 2026.
Carbon-Graphite Brush Market
Market trajectory and macro metrics
Our analysis tracks the market from 2020 through the base year 2025 and models demand to 2032. The sector expanded from roughly USD 150 million in 2020 to about USD 186 million in 2025, reflecting steady end-market replacement cycles and selective demand pockets in electrified mobility and automation. Under the central scenario, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 4.8% through 2032, reaching an overall size in the mid-hundreds of millions of USD by the end of the forecast window.
Carbon-Graphite Brush Market
Two structural observations underlie this trajectory: first, absolute market growth is modest but consistent—driven by longevity improvements in rotating equipment and gradual adoption of higher-specification brush types; second, the competitive landscape remains fragmented (CR3 ~25.5%, CR5 ~38.2%), leaving space for focused scale plays and differentiated technology providers to expand share.
Carbon-Graphite Brush Market
Key demand and technology drivers
- Electrification and motor performance: incremental improvements in motor efficiency, higher RPMs in some applications, and tighter electrical contact tolerances are increasing demand for higher-spec carbon/metal-graphite formulations and engineered brush geometries.
- Industrial automation and lifetime expectations: OEMs are emphasizing longer maintenance intervals; this shifts buying criteria toward material science, performance under marginal lubrication conditions, and predictable wear profiles.
- Specialty applications and customization: niche segments—where brushes must meet high thermal, chemical or electrical demands—are growing faster than bulk commodity demand, creating margin opportunities for suppliers who can combine materials R&D with precision manufacturing.
- Raw-material and supply-chain volatility: graphite feedstock availability, energy-dependent processing, and localized production footprints make supplier continuity and vertical integration important long-term levers.
- Regulatory and sustainability pressures: recycling and lifecycle reporting requirements are beginning to influence procurement choices for larger OEMs, favoring suppliers with traceable materials and lower downstream disposal impacts.
Competitive landscape — profiles and strategic implications
The market’s fragmentation creates a dynamic battleground between legacy specialists and global engineering suppliers. Below we outline the positioning and strategic posture of five companies our research tracked closely; the full report contains benchmarking matrices and supplier scorecards.
- Fuji Carbon Manufacturing Co. (Anjo City, Japan) — Fuji Carbon leverages its deep automotive and appliance heritage to serve high-volume, quality-sensitive OEMs. Its strength is product breadth and tight integration with Japanese tier suppliers; its opportunity is to translate that volume expertise into higher-margin engineered solutions for electrified drivetrains. ( https://www.fuji-carbon.co.jp/en/)
- St Marys Carbon (St. Marys, Pennsylvania, US) — St Marys specializes in high-performance industrial brushes for aerospace and demanding industrial use-cases. Its competitive edge is materials know-how and custom formulations; a sensible growth path is to package material IP with service contracts for predictive replacement and performance validation. ( https://www.stmaryscarbon.com/)
- Helwig Carbon Products (Milwaukee, Wisconsin, US) — Helwig’s precision machining and broad accessory portfolio (brush holders, grounding systems) make it a one-stop supplier for industrial customers seeking integrated solutions. They can deepen differentiation via digital condition-monitoring add-ons and tighter OEM partnerships. ( https://helwigcarbon.com/)
- Schunk Group (Heuchelheim, Germany) — Schunk competes on application-specific engineering and sliding-contact systems for motors and generators. Their R&D posture and European manufacturing footprint position them well for high-spec, regulated markets. Strategic playbooks include platformizing core brush families and bundling retrofit kits for legacy assets. ( https://www.schunk-group.com/carbon-technology/en/)
- Mersen (Courbevoie, France) — Mersen’s strength is in electrographite and metal-graphite products for high-performance applications. Their global reach and electrical expertise enable them to target large generator and high-power motor segments; pursuing joint development agreements with motor OEMs would consolidate their position. ( https://www.mersen.com/)
Where the value pools are (and what we withhold here)
The full study dissects revenue and margin pools by product family, application vertical, and region, and maps supplier-level footprints and cost drivers. In keeping with our “preview” approach, we intentionally omit the granular segment tables and contract-level pricing here. That detailed intelligence—covering type-specific demand curves, application-specific wear profiles, and channel margins—is available only in the full report and is essential for precise pricing, procurement, and M&A decisions.
Actionable insights for 2026 planning
- Prioritize engineering differentiation over pure cost competition. With broadly modest top-line growth, margin expansion will come from higher-spec brush types, service contracts, and design wins with OEMs rather than volume alone.
- Build modular product platforms. Develop a portfolio of brush cores and accessory modules (holders, ground systems) that can be configured for fast OEM qualification—this reduces qualification cost and accelerates penetration in new motor platforms.
- Protect supply continuity through dual-sourcing and strategic inventory for critical raw materials. Given processing constraints and geographic supply variability, a small increase in working capital can prevent costly production interruptions.
- Invest selectively in condition monitoring and performance validation services. Offering predictive replacement and validated performance data can convert replacement customers into service-contract clients and justify premium pricing.
- Target bolt-on acquisitions that add material IP or regional manufacturing density. Given the market’s fragmentation, disciplined M&A focused on complementary chemistry or niche application expertise can accelerate share gains without heavy capital expenditure.
- Align sustainability messaging with procurement cycles. Prepare traceability and end-of-life plans now; tier-1 OEM procurement teams are increasingly requiring such documentation as part of supplier selection.
What the full PW Consulting study delivers
- Granular demand modeling by product type and application with scenario analysis calibrated to motor-electrification trajectories.
- Supplier scorecards, cost-to-serve benchmarks, and qualification time estimates for OEM channels.
- Detailed pricing matrices, channel margin mappings, and contract templates for aftermarket and OEM supply.
- Actionable M&A screening with target shortlists and integration playbooks tailored to different strategic objectives (scale, technology, geographic reach).
- Procurement playbook including dual-sourcing strategies, inventory hedging recommendations, and supplier consolidation roadmaps.
Note: the public summary intentionally excludes complete segmentation tables, contract-level pricing, and individual customer win/loss case studies—these are included in the full document and supporting datasets.
How to use this study in your 2026 planning cycle
- Use our market sizing and CAGR calibration to stress-test FY26 revenue targets under conservative and aggressive motor-adoption scenarios.
- Incorporate the supplier scorecards into procurement RFIs to shorten qualification timelines and surface potential joint-development partners.
- Align R&D budgets to the highest-payoff material and geometrics improvements identified in the report, and quantify the NPV of productized service offerings to accelerate margin recovery.
- Leverage the M&A screening to run a fast two-stage diligence on targets that can complement your footprint or close material-technology gaps.
Concluding perspective
For 2026 planners, the strategic choice is clear: in a market that offers steady growth but remains competitively dispersed, the winners will be those who combine materials expertise, application engineering, and services to move beyond transactional replacements toward integrated, validated solutions. PW Consulting’s full Carbon-Graphite Brush Market study provides the forensic detail needed to prioritize investments, de-risk supply chains, and scope tactical acquisitions—while this preview surfaces the strategic lines of play, the decisive segment-level data and supplier intelligence reside in the full report.
To discuss tailored briefings, supplier scorecards, or to request the complete study, contact PW Consulting’s industry team.
For detailed analysis of this topic, please visit the official page: Carbon-Graphite Brush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


