



PW Consulting: Rotary Encoders Market — USD 2,565M in 2025; 6.9% CAGR to 2032

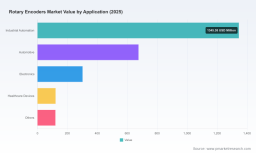
Rotary Encoders Market — Strategic Outlook for 2026 Decision-Makers
As industrial automation, robotics, and next‑generation mobility increasingly rely on precise angular and positional feedback, rotary encoders have emerged from component commodity status into a strategically critical node in motion‑control ecosystems. PW Consulting’s latest Rotary Encoders Market study synthesizes five years of historical performance (2020–2025) with a detailed forecast (2026–2032). At the aggregate level, the market reached approximately USD 2.565 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.9% across our forecast horizon, moving the total market toward the USD 4.06 billion range by 2032. These headline metrics frame the commercial terrain for investments and risk mitigation in 2026; the sections below explain why.
Rotary Encoders Market
Why this research matters for 2026 strategic decisions
-
Timing and portfolio prioritization — A near‑7% CAGR means greenfield and retrofit opportunities will continue to grow, but not uniformly. Leadership teams must decide whether to chase volume growth, deepen high‑margin system integrations, or lock margins through vertical control of critical subcomponents (e.g., encoder ICs, magnets, optics).
Rotary Encoders Market -
Supply‑chain resilience — Recent semiconductor and materials disruptions make supply strategy a top boardroom issue. The report provides scenario playbooks for procurement hedging, dual‑sourcing, and inventory buffers calibrated to the encoder industry’s time‑to‑market demands.
Rotary Encoders Market -
Competitive positioning — Market concentration is moderate: the combined revenue share of the top three players is in the mid‑20s percent range, with the top five accounting for roughly one‑third of the market. That geometry creates advantages for mid‑tier challengers and niche specialists but also signals room for consolidation if transaction markets align.
-
Technology and product strategy — Precision interfaces, multi‑turn absolute solutions, and bearing‑free/harsh‑environment variants are differentiating vectors. Our analysis connects technology roadmaps to likely OEM procurement cycles, helping product and R&D leaders prioritize features that unlock premium pricing and system stickiness.
Macroeconomic and supply‑chain dynamics shaping 2026 tactics
-
Semiconductor concentration risks: Cross‑strait geopolitical tensions and capacity shifts have already impacted encoder‑grade sensor IC availability. Our interviews and supplier maps show that interruptions at advanced foundries can cascade into encoder lead‑times, pushing OEMs to consider longer component lead times or strategic inventory on critical SKUs.
-
Logistics volatility: Shipping reroutes and port congestion events in 2025 created measurable delivery delays. Procurement teams must incorporate transit risk into reorder points and evaluate alternate logistics partners and near‑shoring alternatives where cost and speed tradeoffs make sense.
-
Trade policy uncertainty: Tariff policy changes and export controls through 2025–2026 introduce margin pressure and sourcing complexity. Our cost‑build models demonstrate how modest tariff shifts can erode profitability for low‑margin encoder segments but have a smaller relative impact on high‑precision, high‑value offerings.
-
Industrial policy and supply incentives: Concurrent government initiatives to bolster semiconductor and critical magnet supply chains (notably incentives in the US and India) can reshape sourcing economics over a multi‑year horizon. The report provides timing and impact buckets to inform capital allocation decisions.
Competitive landscape — what to watch from incumbent and emergent players
The market features a mix of global industrial specialists, precision‑engineering houses, and regionally strong players. Key incumbents profiled in the study include long‑standing precision component firms and automation OEMs whose portfolios span optical, magnetic and contacting encoder technologies. For executives developing engagement strategies, the report synthesizes public product footprints and positioning for names you’ll recognize—firms that combine breadth across industrial automation and targeted expertise in machine tools, robotics, automotive, and hazardous‑environment encoders.
-
Bourns, Inc. — Offers a broad portfolio of optical and contacting rotary encoders targeting industrial automation, automotive and panel control applications; positions itself on reliability and scale.
-
HEIDENHAIN GmbH — Known for high‑precision external and internal encoders and digital interfaces well‑suited to machine tool and servo drive customers that prize absolute accuracy.
-
Omron Corporation — Provides compact incremental and absolute encoders with functionality tailored to factory automation and robotics, including multi‑turn features.
-
SICK AG — Supplies high‑resolution absolute and incremental encoders for automation, with recent product introductions focused on ease of integration and connectivity.
-
Pepperl+Fuchs GmbH — Develops optical and magnetic encoder variants, including bearing‑free and heavy‑duty types engineered for hazardous and offshore environments.
-
Grayhill, Hengstler, Baumer, Wachendorff, FRABA and Renishaw — Each contributes specialized offerings across haptic controls, compact robotics encoders, bearingless/high‑speed designs, app‑configurability, battery‑less absolute solutions, and ultra‑high accuracy optical encoders used in precision machining and metrology.
Competitive moves to monitor in 2026 include differentiated interface support (e.g., EnDat, SSI, DRIVE‑CLiQ), app‑based configurability, and ruggedization for offshore/wet environments. Our strategic benchmarking scores identify which manufacturers are best placed to capture premium segments versus high‑volume, cost‑sensitive applications.
Recent signal events and tactical implications
-
Product introductions: Recent launches demonstrate vendors investing in connectivity and system integration (example: new ProfiNet‑capable absolute encoders designed for simplified system integration), which shortens engineering cycles for OEMs and raises the bar for new entrants.
-
Environmental packaging and washdown ratings: Expanded lineups with higher ingress protection reflect growing demand from food, pharmaceutical and outdoor automation sectors; expect revised procurement specifications and longer validation programs.
-
Component supply alerts: Public reporting of advanced node foundry constraints has already influenced lead times for encoder controllers and signal processing ICs; procurement teams should map single‑sourced ICs and evaluate second sources or fallbacks in their BOMs.
What the full report delivers — practical, transaction‑grade intelligence
PW Consulting’s study is structured to support immediate commercial and technical decisions. Deliverables include:
-
Top‑line forecast model (2026–2032) with scenario toggles and sensitivity analysis anchored to a 6.9% base CAGR.
-
Demand driver matrices that link end‑market trajectories (automation, mobility, electronics, healthcare) to encoder requirements by accuracy, interface, and environmental rating.
-
Supplier risk and resiliency dashboards: single‑point‑of‑failure maps, lead‑time distributions, and recommended stocking policies calibrated to product criticality.
-
Competitive benchmarking and capability heatmaps for the leading vendors, including product positioning, channel strategy, and technology differentiators.
-
M&A and partnership playbooks: target archetypes, valuation multiples context, and integration risk checklists aligned to consolidation scenarios.
-
Go‑to‑market templates and pricing frameworks for launching differentiated encoder SKUs or entering adjacent automation subsystems.
-
Technical appendix: interface standards, test protocols, and recommended specification language to harmonize OEM procurement across regions.
-
Primary research corpus: executive interviews, OEM procurement surveys and anonymized vendor scorecards used to validate commercial judgments.
Actionable priorities for 2026
-
Conduct SKU triage: identify high‑value variants (precision, multi‑turn, ruggedized) where margin capture justifies closer control of supply and certification investments.
-
Implement a two‑track sourcing strategy: tactical buffering for short‑cycle components and strategic partnerships or equity stakes for tightly constrained semiconductor or magnet supplies.
-
Accelerate interface compatibility: support for industrial networks and encoder protocols materially reduces OEM engineering friction—design teams should prioritize protocol support roadmaps.
-
Test M&A or JV options selectively: moderate concentration leaves room for bolt‑on deals to acquire complementary tech or geographic footholds; prioritize targets with sticky OEM relationships or unique environmental capabilities.
-
Embed logistics contingency planning into commercial forecasts: model 2–3 week transit disruptions and reroute costs to understand true landed cost to end OEMs.
How to use the report and where to find the missing tables
The narrative above intentionally highlights strategic conclusions while withholding the granular segment tables, regional breakdowns, and SKU‑level revenue splits that commercial teams need for supplier negotiations and investment memoranda. Those core data assets—including detailed regional and application segmentation, price trajectories by encoder type, and downloadable forecast files—are accessible in the full PW Consulting study. If your priority for 2026 is a targeted play (e.g., entering absolute multi‑turn, pursuing a supply‑side JV, or optimizing SKU profitability), the report’s downloadable models and the advisory team’s scenario workshops will materially shorten decision cycles and reduce execution risk.
In an environment where precision matters both technically and commercially, the right mix of data‑driven forecasting, scenario planning, and supplier strategy converts a growing market into durable competitive advantage. PW Consulting’s Rotary Encoders Market research provides that mix—enough to act with conviction, and the full depth you’ll need to execute.
For detailed analysis of this topic, please visit the official page: Rotary Encoders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


