



PW Consulting: Hair Loss & Growth Market to Expand at 5.98% CAGR Through 2032

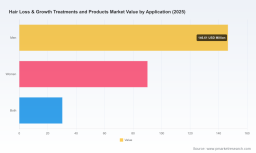
Strategic Outlook: Hair Loss & Growth Treatments and Products Market — A 2026 Playbook
As companies recalibrate strategies for 2026, the hair loss and growth treatments market presents a mixture of steady demand, accelerating clinical innovation, and regulatory complexity. Our new PW Consulting market research (base year 2025; forecast period 2026–2032) quantifies a clear expansion trajectory: the global market has grown from a mid-hundreds million USD base in 2020 to roughly USD 267 million in 2025 and is projected to approach USD 405 million by 2032, reflecting a compound annual growth rate of approximately 5.98% over the forecast window. This briefing highlights the research’s strategic value for 2026 decision-makers, outlines the actionable contents of the report, summarizes competitive and regulatory developments to watch, and proposes pragmatic moves that leaders should consider now.
Hair Loss & Growth Treatments and Products Market
Why this research matters for 2026 corporate decisions
-
Predictable, investable growth: The market’s mid-single-digit CAGR signals a stable but competitive growth environment. Organizations that blend clinical differentiation with commercial discipline can capture outsized returns against a backdrop of steady total-market expansion.
Hair Loss & Growth Treatments and Products Market -
Pipeline-driven market reshaping: Late-stage therapeutic advances — spanning topical biologics, oral non-hormonal agents, and immune-modulating therapies for autoimmune hair loss — are changing product mix, channels, and payer conversations. These shifts require companies to reassess R&D prioritization, launch sequencing, and cross-functional readiness now.
Hair Loss & Growth Treatments and Products Market -
Regulatory and safety noise demands active mitigation: Public health communications and agency alerts around compounded products have elevated regulatory and reputational risk. Companies must align clinical evidence strategies with regulatory engagement and communications plans to avoid commercial and compliance setbacks.
-
Moderate market concentration: The market exhibits mid-level concentration among leading firms, which means dominant players can shape standards, but gaps exist for focused entrants and differentiated offerings.
What PW Consulting’s report delivers (practical, execution-focused content)
-
Comprehensive market sizing and multi-scenario forecasting (2026–2032) with sensitivity analyses for clinical success rates, pricing scenarios, and reimbursement dynamics.
-
Go-to-market playbooks tailored to product archetypes — prescription therapeutics, over-the-counter cosmetics, and device-led interventions — covering channel strategy, physician engagement, and DTC marketing considerations.
-
Regulatory pathway mapping and decision trees, including risk mitigation templates for compounded product narratives and evidence packages aligned to FDA expectations.
-
Clinical landscape atlas: trial timelines, mechanism-of-action maps, endpoints comparison, and adoption curves that help prioritize indications and sequence launches.
-
Commercial benchmarking and pricing frameworks that reconcile R&D investment profiles with expected payer behaviors and consumer willingness-to-pay.
-
M&A and partnership playbooks with candidate screening criteria, valuation sensitivities, and integration checklists for quickly moving from diligence to deal-close.
-
Primary research insights: interviews with key opinion leaders, dermatology clinic directors, payers, and distribution partners to inform pricing, reimbursement, and promotional tactics.
Competitive landscape: who’s shifting the market and why it matters
-
Pelage Pharmaceuticals (Los Angeles) — advancing PP405, a topical stem cell reactivation therapy. Positive Phase 2a results in 2025 and a Phase 3 initiation in 2026 signal an intent to compete in the high-value topical therapeutics corridor. For incumbents, Pelage’s approach reflects a strategy to differentiate on mechanism and clinical durability rather than price alone.
-
Veradermics (New Haven) — developing VDPHL01, an oral non-hormonal agent for pattern hair loss. Completion of Phase 3 enrollment in early 2026 indicates a near-term potential for a new oral option that could shift prescribing patterns and broaden patient segments willing to pursue pharmacologic therapy.
-
Nektar Therapeutics (United States) — pursuing an IL‑2 receptor–modulating biologic (rezpegaldesleukin/Rezpeg) for severe-to-very-severe alopecia areata. The reported long-term topline data in 2026 show deepening regrowth responses, underscoring the rising role of immune‑modulating biologics in autoimmune hair loss and the subsequent implications for specialist care pathways and reimbursement.
-
Cosmo Pharmaceuticals (Dublin) — developing clascoterone (Breezula) topical solution with Phase 3 topline results reported in late 2025 and ongoing safety follow-up into 2026 ahead of planned regulatory submission. This program exemplifies the classic pharmaceutical pathway: late-stage data to underpin label differentiation and premium pricing.
Collectively, these programs highlight two strategic realities for 2026: (1) clinical differentiation will increasingly determine commercial outcomes, and (2) timing and sequencing around Phase 3 readouts and regulatory submissions will create windows of opportunity for partnerships, distribution agreements, and targeted marketing investments.
Regulatory dynamics and market risk
-
Recent agency communications have drawn attention to safety risks tied to compounded topical formulations. These advisories have elevated scrutiny on compounding practices and created both near-term reputational risk and longer-term opportunity for approved, standardized alternatives.
-
The absence of regulatory approvals for certain topical formulations commonly used in practice increases uncertainty for existing compounding-based channels and highlights the commercial advantage for firms that can bring approved, clinically-validated products to market.
-
For 2026, companies should anticipate intensified regulatory engagement, including expectations for post-approval safety follow-up and real-world evidence commitments that could shape launch timetables and promotional claims.
Strategic implications and recommended actions for 2026
-
For biotech and pharma: Prioritize regulatory-readiness and dossier quality. If you have late-stage assets, build parallel commercial preparations (payer dossiers, KOL networks, specialty distribution) ahead of approval decisions. Consider staged market entry to manage manufacturing scale-up and formulary negotiations.
-
For consumer brands and OTC players: Invest in clinical differentiation and consumer trust signals (clinical claims substantiation, clinic partnerships). Leverage digital channels to shorten trial-to-purchase cycles and capture demand from early adopters seeking non-prescription solutions.
-
For device manufacturers: Differentiate through integrated ecosystems — devices plus monitoring apps, clinician portals, and subscription models — to raise switching costs and create recurring revenue streams.
-
For investors and private equity: Target bolt-on acquisitions that provide clinical credibility or unique distribution access. Use scenario models that stress-test valuation under delays to pivotal trials and varying reimbursement outcomes.
-
Cross-cutting moves: enact a three-layer playbook: (1) evidence acceleration — pre-launch RWE studies and registries; (2) regulatory engagement — proactive safety communications and labeling strategy; (3) channel hedging — diversify between specialty clinics, retail, and DTC to balance risk.
Where winning competitive advantage will emerge
-
Biologic and immune-modulating therapies for alopecia areata — deep clinical efficacy will reconfigure specialist referral patterns and payer strategies.
-
Non-hormonal oral agents and novel topical mechanisms — those that combine convenience with demonstrated durability of response will broaden market penetration beyond traditional dermatology patients.
-
Integrated care models — combining diagnostics, teledermatology, and adherence-enabled products — will increase lifetime customer value and support premium pricing.
-
Validated, regulatorily cleared alternatives to compounded products — as safety concerns persist, evidence-backed, standardized products will capture share from informal compounding channels.
How PW Consulting turns insight into 2026 action
-
We translate the macro trajectory and competitive events into executable plans: launch readout calendars, payer engagement timelines, and contingency scenarios that map directly onto 2026 boardroom milestones.
-
Our report’s scenario modeling quantifies P&L and valuation impacts across a range of clinical and regulatory outcomes, enabling executives to prioritize capital allocation under uncertainty.
-
We provide deal-ready diligence packages and integration playbooks for M&A, licensing, and co-promotion arrangements that respect the compressed timelines around pivotal data readouts in 2026.
To lead in 2026 you need more than market sizing — you need a playbook that aligns clinical timelines with commercial execution, regulatory positioning, and capital strategy. PW Consulting’s full report contains the granular segmentation, channel-specific models, and primary research that will let your team operationalize the moves outlined here. For companies planning launches, partnerships, or portfolio reshapes in 2026, these are not theoretical levers — they are immediate decision points. Visit our report page to access the full dataset, interactive scenario models, and bespoke advisory options tailored to your organization’s role in the evolving hair loss and growth market.
For detailed analysis of this topic, please visit the official page: Hair Loss & Growth Treatments and Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


