



PW Consulting: Luxury Hotels Market Set to Reach USD 185.6 Billion by 2032

Luxury Hotels Market — Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
After a volatile half‑decade of disruption and recovery, the global luxury hotels market reached an inflection point in 2025. Our base‑year synthesis shows the market size crossing the low‑hundreds (USD, base‑year 2025) and, under a central scenario, expanding at a compound annual growth rate (CAGR) of roughly 5.1% across the 2026–2032 forecast window. That trajectory drives a material uplift in absolute market value by the end of the decade and cements luxury lodging as the hospitality complex’s primary growth engine.
Luxury Hotels Market
This briefing introduces the strategic value of PW Consulting’s full Luxury Hotels Market study for corporate leaders, investors, and portfolio managers planning 2026 actions. It highlights why the report is decision‑critical while deliberately withholding the granular segment tables and raw regional splits available in the full package — a curated “teaser” designed to demonstrate analytical depth and drive targeted engagement.
Luxury Hotels Market
Why this research matters for 2026
- Timing and capital allocation: With demand indicators (ADR and RevPAR) showing premium outperformance versus lower tiers, investors must re‑calibrate capex and development priorities to capture faster cash‑flow recovery in luxury assets.
- Portfolio optimization: Operators and owners face tradeoffs between brand‑led repositioning and asset conversion; understanding how premium segments rebound across scenarios determines ROI and hold/sell decisions.
- Competitive positioning: Brand architecture moves and consolidation activity in early 2026 mean immediate reassessment of distribution, loyalty alignment, and brand partnerships is necessary to defend or capture market share.
- Tech and labor planning: Labor cost pressures and emergent AI frameworks are reshaping staffing models and guest personalization; management teams must translate regulatory and technology futures into 12–24 month implementation roadmaps.
What the full report delivers (practical, operational outputs)
- Detailed market sizing and multi‑scenario forecasts (2026–2032) validated against historical performance and macro scenarios.
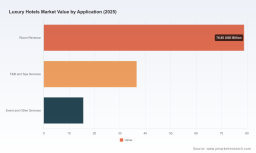
- Segmented demand and revenue models by region, product type and revenue stream — with downloadable financial model templates that let teams stress‑test price, occupancy and mixed‑use strategies.
- Competitive benchmarking with profile dossiers on leading global groups, recent portfolio moves and capability maps (brand positioning, loyalty reach, distribution strengths, and wholesale vs direct channel exposures).
- Revenue management playbooks that align ADR and packaging tactics to segmented willingness‑to‑pay and length‑of‑stay dynamics; includes sample rate fences and upsell architectures developed from transaction‑level proxies.
- Operational KPIs and cost‑base diagnostics (labor, energy, maintenance) with normalized comparables and gap‑analysis templates for asset owners and operators.
- Investment and M&A decision aids: valuation sensitivity matrices, accretion/dilution frameworks for brand acquisitions, and an opportunities scoreboard calibrated to risk appetite.
- Technology and ESG roadmaps: prioritized digital investments (guest personalization, housekeeping automation, predictive maintenance) and sustainability targets tied to capital planning.
Competitive landscape — what top players are doing and why it matters
The global luxury field remains meaningfully fragmented: a small number of global groups hold a meaningful share of aggregate revenue but do not dominate the market the way global players do in some other industries. That structure creates both opportunity and competitive complexity: strong brands enjoy scale economies in distribution and loyalty, while independents and boutique collections capture premium pricing through distinctive experiences.
Luxury Hotels Market
- Marriott International — Continuing to elevate its top brands through formal segmentation strategies, Marriott is sharpening the value proposition of its flagship luxury banners to reinforce premium rate integrity and loyalty uplifts. Expect a stronger focus on differentiated experiences and curated cross‑brand itineraries.
- Hilton Worldwide — The completed integration of a premier boutique collection into Hilton’s luxury fold has already translated into expanded distribution and membership acceleration for boutique properties. That integration creates downstream pressure on smaller independent operators to either join platforms or double down on ultra‑niche positioning.
- Hyatt — Hyatt continues to leverage its upper‑upscale and luxury brand stack to pursue selective growth, prioritizing experiential stays, branded residences and co‑developed F&B concepts.
- IHG, Accor and other global groups — These chains balance global scale with regional brand acquisitions and partnerships to secure market access, particularly in markets where luxury demand recovery is uneven.
- Ultra‑luxury and boutique independents (Mandarin Oriental, Rosewood, Capella, Four Seasons, curated collections) — These groups are doubling down on distinctiveness: localized storytelling, residential offers, and experiential F&B/spa programming that command rate premiums and drive loyalty among high‑net‑worth clientele.
Recent 2026 initiatives — from new flagship openings to brand integrations — are not cosmetic. They redesign distribution curves, alter pricing elasticities, and shift competitive arbitrage for owners and operators. The full report contains a tactical impact matrix for each major move, helping teams decide whether to reposition, reflag, or defend.
Key market dynamics and near‑term risks
- Demand resilience and pricing power: Luxury RevPAR and average daily rate metrics have outperformed mass leisure and economy tiers in the post‑pandemic rebound. That trend underpins stronger cash generation potential but also raises expectations on service delivery and product refresh cycles.
- Labor and cost inflation: Wage pressures remain a structural headwind. Operators that invest in productivity enhancing technology (while preserving high‑touch guest service where it matters most) will sustain margins; those who do not face margin compression or must trade service for efficiency.
- Consumer preference shift: Affluent travelers are increasingly allocating spend to curated experiences over ownership. The implication is that experiential F&B, wellness and bespoke excursions are high‑return investments for operators looking to grow ancillary revenues.
- Regulation and technology governance: The emergence of global AI frameworks for personalization and operational efficiency implies compliance complexity but also new levers for margin expansion. Early movers who deploy governed, privacy‑conscious personalization will capture disproportionate wallet share.
- Macro and geopolitical exposures: Regional demand shock sensitivities remain heightened. Scenario planning — including soft, central, and aggressive growth paths — should be embedded in all 2026 capital allocation decisions.
Strategic imperatives for 2026 (what leaders should do this year)
- Recalibrate capex and renovation windows: Prioritize product refreshes that unlock price elasticity (guest rooms, signature F&B, wellness offerings) and delay or re‑scope projects with uncertain demand horizons.
- Monetize experiences: Convert guest recognition data into higher‑margin ancillary revenue streams (bespoke excursions, in‑residence dining, long‑stay packages) while testing premium packaging at scale.
- Adopt governed AI where it pays: Deploy personalization engines for upsell conversion and housekeeping/maintenance predictive tools to mitigate labor inflation. Ensure regulatory‑first governance to avoid compliance back‑slides.
- Optimize distribution mix: Reduce dependency on rate‑diluting channels through loyalty, direct booking incentives and localized partnerships with luxury travel advisors.
- Refine M&A and brand strategies: Use the current market window to evaluate tuck‑ins that fill capability gaps (spa brands, experiential operators, technology platforms) and to assess accretive flag conversions versus leaseback models.
- Institutionalize scenario planning: Convert the report’s scenario outputs into concrete trigger points for capital deployment, hiring plans, and brand repositioning decisions.
How to use the full study — next steps
PW Consulting’s full Luxury Hotels Market report contains the granular split tables, regional and application forecasts, downloadable financial models, and company‑level impact assessments that underpin the strategic guidance summarized here. If your 2026 planning cycle requires actionable investment cases, a customized competitor impact analysis, or a workshop to convert the model outputs into board‑level decisions, the full report and our advisory teams are configured to deliver tailored outputs within a 4–6 week engagement.
In short: the luxury segment offers accelerated growth and elevated margin potential in the current cycle, but extracting that value requires disciplined product investment, intelligent use of technology, and strategic responses to a shifting competitive field. Our full study gives you the granular inputs and operational playbooks to make those calls. For access to the complete dataset, segment tables and bespoke advisory engagements, please visit the source page linked in PW Consulting’s distribution channels.
For detailed analysis of this topic, please visit the official page: Luxury Hotels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


