



PW Consulting: EV Traction Motor Market Poised for 29.14% CAGR Through 2032

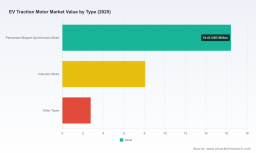
EV Traction Motor Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
The EV traction motor market is transitioning from niche electrification projects into mainstream powertrain architecture. PW Consulting’s analysis — built on a 2025 base year and a seven‑year forecasting horizon (2026–2032) — quantifies that transition: the addressable market expanded from USD 12.0 Million in 2020 to USD 27.28 Million in 2025 and is projected to exceed USD 35.42 Million in 2026, continuing to grow at a compound annual growth rate (CAGR) of 29.14% through 2032, when the market reaches an estimated USD 163.42 Million (USD Million units). This trajectory reflects accelerating EV adoption, rising electrification of commercial fleets, and increasingly diversified motor architectures that are being embedded across vehicle platforms.
EV Traction Motor Market
Why this study matters for 2026 strategic choices
For executives planning capital allocation, product architecture, and supply chain commitments in 2026, the market dynamics captured in this report are decisive. Rapid top‑line expansion combined with a relatively low concentration among incumbents (CR3 ~22.5%, CR5 ~30.0%) creates a window where well‑timed investments can secure outsized returns — but only if companies align strategy with near‑term constraints in raw materials, manufacturing scale, and regulatory requirements.
EV Traction Motor Market
- Timing capital expenditure: The steep growth implied by 2026–2032 forecasts compresses the payback horizon for new manufacturing lines and COGS reduction programs.
- Technology selection: Investments in axial‑flux, in‑wheel, e‑axle or modular central drives should be prioritized based on program pipelines and integration complexity — not just intellectual interest.
- Supply security: Raw material and magnet availability will determine which motor chemistries and design families are practical to deploy at scale within 12–24 months.
Market dynamics and risk matrix
The macro drivers are straightforward: electrification mandates, fleet electrification economics, and falling battery costs. The differentiators lie in supply‑side frictions and regulatory shifts that have outsized consequences on unit economics.
EV Traction Motor Market
- Raw materials: Rare earths remain a dominant cost input for many high‑efficiency motor topologies; sector analysis indicates rare earths can represent nearly 40% of the traction motor core production cost. Geographic supply actions — for example, export restrictions on heavy rare earths introduced in 2025 — have already widened sourcing premiums and require immediate procurement adjustments.
- Regulation & policy: Jurisdictions are tightening critical‑materials governance. The EU announced a set of measures in mid‑2025 targeting supply chains for EV motors and batteries, while U.S. federal roadmaps set manufacturing cost targets that are now baseline constraints for OEM supplier negotiations (e.g., DOE targets for a 100 kW on‑road traction drive system have established clear cost expectations).
- Material & manufacturing bottlenecks: Electrical steel lead times extended by 30–45 days during 2025 supply disruptions. Near‑term capacity investments (e.g., automated winding lines, modular assembly cells) will be the gating factor for meeting 2026 production ramps.
- Opportunity windows: New suppliers of sintered magnets and magnet processing capacity are entering the market with commercial deliveries scheduled in mid‑2026, relieving pressure if OEMs secure offtake agreements early.
Competitive landscape — who matters and how they are moving
The competitive field is a mix of large global Tier‑1s scaling existing product portfolios and specialized innovators carving niches in performance, packaging or integration:
- ABB Ltd. (Zurich, Switzerland) — Offers configurable traction systems and recently launched motor‑inverter packages that demonstrably reduce motor losses on heavy vehicles. Their strategy centers on system optimization for commercial vehicles and buses, leveraging inverter‑motor co‑development.
- YASA Ltd. (Kidlington, U.K.) — A specialist in axial‑flux permanent magnet designs; public OEM programs show their motors being used in high‑performance variants, indicating a premium, performance‑led go‑to‑market approach.
- Protean Electric (Coventry, U.K.) and Elaphe Propulsion Technologies (Ljubljana, Slovenia) — Leaders in in‑wheel direct‑drive technology; their value proposition emphasizes packaging, modularity and new vehicle architecture possibilities but faces trade‑offs in unsprung mass and durability engineering.
- Turntide Technologies (Gateshead, U.K.) — Pursuing axial flux and systems integration with recent product introductions and vehicle integrations targeting specialty vehicles and commercial platforms.
- Nidec Corporation (Kyoto, Japan) — Executing scale plays, with production expansions that increase annual output capacity and prioritize cost competitiveness for high‑volume OEM programs.
- European powertrain Tier‑1s (ZF, MAHLE, Continental, Valeo) — Competing with integrated e‑axle and inverter portfolios that emphasize platform‑level modularity and OEM systems responsibility.
- AC Propulsion — A niche, performance‑oriented player with deep controls and power electronics expertise.
Recent strategic moves illustrate where competitive advantage is being built. Several companies announced product launches and integration wins between 2025 and early 2026 (axial‑flux EDU launches, e‑axle packages for buses, and expanded high‑capacity motor winding lines). These moves signal two parallel plays: (1) scale cost efficiency through manufacturing investments; and (2) differentiated performance/packaging through topology innovation.
Strategic playbook for 2026
We recommend C‑suite and business unit leaders adopt a three‑pronged approach to position for the accelerated growth window beginning in 2026:
- Secure supply and manage material exposure: Lock in magnet and electrical steel offtake with tier‑2 strategic partners; evaluate vertically integrated options where upstream margins justify investment; and build dual‑sourced tooling recipes for the most magnet‑intensive platforms.
- Optimize portfolio sequencing: Prioritize product families that can deliver first cash flow within 18 months while keeping optionality for higher‑margin architectures as material economics evolve. Use modular e‑axle platforms to reduce integration cost and speed up OEM adoption.
- De‑risk production through staged scale: Combine contract manufacturing for initial production ramps with a phased capital program to bring incremental capacity online only as validated orders materialize. Embed advanced automation (e.g., robotic winding, cell‑level testing) to meet DOE‑style cost targets over the medium term.
- Commercial & partnership strategies: Pursue OEM strategic partnerships where co‑development reduces validation time and creates switching friction. For niche players, co‑branding or licensing can accelerate market penetration without requiring scale investments.
- M&A and alliances: With market concentration still modest, targeted acquisitions of complementary IP (controls, power electronics, magnet processing) or bolt‑on capacity can be accretive and defensible against fast‑moving incumbents.
What PW Consulting’s EV Traction Motor Market study delivers (practical modules)
The full PW Consulting report provides the operational intelligence necessary for deployment decisions in 2026. Core deliverables include:
- A granular demand model (historical 2020–2025, base year 2025) and a scenario‑based forecast 2026–2032 with sensitivity to material pricing, OEM program cadence and regulatory interventions.
- Supplier and competitor intelligence dossiers: product roadmaps, validated OEM integrations, production footprints and recent corporate events.
- Unit cost models and cell‑level sensitivity analysis that isolate the drivers of motor system COGS under multiple magnet and steel price paths, plus a path to meet leading government cost targets.
- Manufacturing & supply chain stress tests: lead‑time simulations, capacity adequacy assessments, and mitigation playbooks for material disruptions and export constraints.
- Commercial playbooks for OEM engagement, tier‑1 partnerships, and aftermarket strategies, including contracting templates and price indexation approaches.
- Strategic scenarios and decision trees for M&A, joint ventures, CAPEX timing, and production footprint optimization.
Note: This summary intentionally omits the detailed segmentation tables and supplier scorecards included in the full report (to preserve the utility of the complete dataset for purchasing clients). The full study contains the regional, application and technology splits required to model program‑level revenue and margin outcomes; these elements are only available in the paid deliverable.
How to use the intelligence in 2026 boardroom decisions
Executives should translate the report’s insights into a short list of board‑level actions for 2026:
- Approve conditional capital allocations for capacity based on milestone‑driven triggers tied to validated OEM contracts and material hedges.
- Establish a cross‑functional Magnet & Steel Task Force to secure multi‑year supply and develop cost‑reduction plans aligned to DOE targets and EU regulatory expectations.
- Implement a “fast follower” or “specialist niche” product strategy depending on corporate scale: larger OEMs should pursue integrated e‑axle systems; specialized suppliers should double down on axial‑flux/in‑wheel niches where technical differentiation yields margin.
- Prioritize short‑cycle customer wins that validate manufacturing processes, then scale via staged CAPEX to capture volume benefits without overcommitting before 2027 demand inflection points.
Conclusion — the window for defining market leadership
The EV traction motor market’s rapid expansion offers a rare opportunity to shape future powertrain economics and capture lasting OEM relationships. However, the path to leadership is neither automatic nor evenly distributed: it depends on pragmatic supply assurance, disciplined capital sequencing, and choosing the right technical bets. PW Consulting’s EV Traction Motor Market study converts the broad growth narrative (CAGR 29.14%; USD 27.28 Million base in 2025 and a projected USD 163.42 Million by 2032) into executable decisions for 2026. For teams preparing budgets, negotiating supply contracts, or evaluating M&A targets this year, the right intelligence will materially change outcomes.
Next steps
To access the full dataset, segmentation tables, supplier scorecards and proprietary cost models that underpin these conclusions, request PW Consulting’s complete EV Traction Motor Market report. The full deliverable contains the program‑level detail and downloadable models executives use to finalize 2026 investment and sourcing decisions.
For detailed analysis of this topic, please visit the official page: EV Traction Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


