



PW Consulting: Luggage Market to Reach USD 101.01 Million by 2032 at 8.3% CAGR

Luggage Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As global mobility re-enters a period of structural expansion, executives must navigate an environment shaped by accelerating consumer expectations, supply-chain turbulence and renewed regulatory friction. PW Consulting’s latest Luggage Market study—anchored on a 2025 base year, a five-year historical window (2020–2025) and a seven-year forecast (2026–2032)—translates macro momentum into 10 strategic decisions that corporate leaders should treat as immediate priorities for 2026. The study combines robust market-sizing, scenario-driven forecasting and practitioner-ready playbooks to convert insight into action.
Luggage Market
Why this report matters for 2026 decision-making
-
Market momentum: The luggage market demonstrated consistent expansion across the 2020–2025 period and is projected to continue growing through 2032 under an 8.3% CAGR (forecast period 2026–2032). Our base-year sizing and trajectory models show more than a doubling of market value from early-decade levels to the end of the forecast horizon—confirming a durable market opportunity for both incumbents and new entrants.
Luggage Market -
Consolidation dynamics: Market concentration is meaningful. The top three players account for roughly two-thirds of market value, and the top five approach three-quarters—conditions that favor scale-driven producers but also create whitespace for focused specialists and digitally native brands.
Luggage Market -
Regulatory and cost shock risk: New tariff measures implemented in 2025 broadened coverage to components such as frames, handles and wheel housings. The policy shift has already created observable cost pressure for importers and small manufacturers, prompting workforce adjustments and capex reallocation—risks that should be priced into 2026 planning.
What the study delivers (operational and strategic value)
-
Macro and scenario-based market sizing: Rolling base-year valuations and conservative/central/aggressive scenarios to stress-test demand in three macro states (soft travel recovery, structural premiumization, and constrained-cost inflation).
-
Go-to-market playbooks: Channel-specific strategies for premium, mid-market, and value tiers—coverage includes wholesale partnerships, direct-to-consumer scaling, and marketplace optimization with practical KPIs and conversion benchmarks.
-
Supply-chain risk maps: Component-level exposure tables (tariff-sensitive items, single-supplier risks, lead-time criticality) and prioritized mitigations such as dual-sourcing, nearshoring pilots and inventory-financing options.
-
Competitive playbook and M&A screen: Comparative profiles of incumbent players, archetypal disruptors, and specialty brands—scoring for strategic fit across brand equity, channel overlap, manufacturability and margin synergy potential.
-
Pricing and promotional models: Elasticity matrices and markdown optimization templates to protect margin while sustaining share in promotional-heavy channels.
-
Sustainability and circularity roadmaps: Practical implementation steps (materials substitution pilot prioritization, repair and refurbishment programs, take-back monetization) and financial case templates for ESG-linked investments.
-
Regulatory tracker and scenario playbooks: Monitoring and response frameworks for tariff, trade and materials-regulation developments—designed to shorten decision cycles when policy shocks occur.
Competitive landscape: who matters and what they signal
The market is anchored by established global brands alongside digitally native and specialty players. Leading incumbents combine scale manufacturing, broad distribution and recognizable consumer propositions—durability and design remain dominant purchase drivers. Several strategic patterns emerge from our company-level analysis:
-
Scale incumbents (e.g., long-standing global manufacturers) leverage distribution breadth and B2B channel depth to defend share, but face margin pressure from rising input costs and retail consolidation.
-
Premium specialists emphasize brand equity and after-sales service (lifetime guarantees and repair networks) as defensible differentiators; their pricing power, however, depends on sustained travel demand among higher-velocity cohorts.
-
Digital-first entrants adopt a direct-to-consumer model with rapid product cycles and integrated accessory ecosystems; these players accelerate category innovation but must overcome unit economics challenges as acquisition costs rise.
-
Adventure and specialty brands place emphasis on ruggedization and functional differentiation, an approach that becomes a natural hedge when leisure travel segments favor experiential trips.
Recent corporate activity underscores these dynamics. One specialty brand recently increased its profile via major event sponsorships, signaling a pivot to brand-led growth even as it navigates macro cost pressures. For leaders evaluating competitors or potential partners, the full report contains detailed company profiles, channel mix diagnostics, and acquisition candidate screens designed to shorten the time from diligence to deal execution.
Regulatory shocks and supply-chain playbook
Fiscal 2025–2026 introduced sharper trade-policy volatility that directly affects the luggage value chain. Expansion of tariffs to include structural components—such as frames, telescopic handles and wheel housings—has materially altered landed costs for imports. Some manufacturers have publicly disclosed attempts to recover tariff-related expenses, while smaller firms have reported layoffs and expenditure cuts in response to widened margins pressure.
For 2026, PW Consulting recommends a three-layer mitigation strategy:
-
Short term (0–6 months): Rapid cost-forensics to identify tariff-exposed SKUs, temporary repricing tests, and a targeted mix-shift toward higher-margin SKUs where possible.
-
Medium term (6–18 months): Supply diversification—nearshoring pilot programs, contract renegotiation with tier-1 component suppliers, and inventory hedging to smooth input-cost volatility.
-
Long term (18+ months): Vertical moves where economically viable (strategic in-sourcing or joint ventures for high-exposure components) and investing in design-to-cost initiatives to reduce dependence on tariff-sensitive bill-of-material elements.
Strategic priorities for executives in 2026
Based on our integrated analysis, the following priorities should guide executive agendas next year:
-
Prioritize resilience over optimization alone: Rebalance cost-efficiency programs with investment in redundancy for critical nodes to prevent single-point failures during policy or demand shocks.
-
Segment the portfolio with discipline: Use customer and margin analytics to rationalize SKUs—double down on high-growth, high-margin archetypes while considering divestiture or licensing for underperforming lines.
-
Monetize services: Expand repair, refurbishment and subscription offerings to extend lifetime value and differentiate against commoditized competitors.
-
Accelerate channel transformation: Invest selectively in first-party digital capabilities to capture margin improvements, while preserving strategic wholesale partnerships for scale.
-
Embed sustainability as commercial strategy: Material innovation and circular services should be pursued not just for compliance but as a source of product differentiation and PR value.
-
Calibrate M&A to concentration economics: With significant share controlled by a small number of players, acquisitions should prioritize capability adjacency (e.g., digital marketing, materials science) or geographic footholds to move the needle on market share.
How the report helps you act now
PW Consulting’s Luggage Market study is intentionally practical. Beyond strategic conclusions, the appendices include templates for scenario P&L, a supplier-risk heatmap, a prioritized regulatory watchlist and a 90-day execution checklist for operations, marketing and M&A teams. We designed these tools so leadership teams can transition from insight to implementation without reinventing analytic wheels.
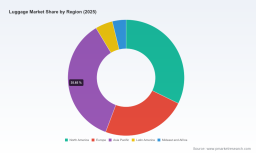
To preserve competitive value and adhere to our “trailer” principle, this executive introduction highlights the study’s core findings and recommended actions while withholding granular segment-level allocations and price-by-channel matrices. Those detailed breakdowns, including regional and application splits and the full financial model, are available in the full report.
Suggested next steps for 2026 planning
-
Immediate: Convene a cross-functional rapid-response team to stress-test your 2026 plan against three PW-defined scenarios. Use our 30–90 day checklist to identify immediate margin recovery levers and tariff mitigations.
-
Near term: Request the full report to access the supplier-risk heatmap, SKU-level pricing elasticity models and the M&A target shortlist tailored to your strategic profile.
-
Ongoing: Subscribe to our regulatory tracker for monthly alerts on trade policy changes that affect component-level cost exposure.
PW Consulting’s Luggage Market study is targeted at CEOs shaping portfolio strategy, CFOs quantifying mid-term capital needs, COOs reworking supply chains, and CMOs building brand growth roadmaps. If you are positioning your organization for the next wave of market expansion or defending against policy-driven cost shocks, the full report provides the granular analytics and operational playbooks to make confident, fast decisions in 2026.
Access to the complete dataset, company profiles and executable templates is available through the PW Consulting research portal—visit the source page to download the full report and supporting workpapers.
For detailed analysis of this topic, please visit the official page: Luggage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


