



PW Consulting: Clear Aligner Market Poised for 14.25% CAGR, Reaching USD 7.93B by 2032

Clear Aligner Market 2026: Strategic Imperatives for Decision-makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Clear Aligner (Invisible Braces) Market
Why this study is indispensable for 2026 planning
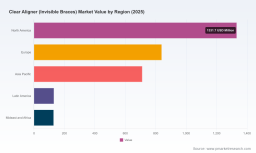
The clear aligner sector has moved from a fast-growth niche to a structurally expanding healthcare market. On a consolidated basis the market crossed the USD 3.14 billion threshold in our base year (2025) and, under our central forecast, is set to approach roughly USD 7.93 billion by 2032 — representing a compound annual growth rate of 14.25% across the forecast window. The transition from the 2020–2025 historical phase into a new 2026–2032 growth chapter marks a strategic inflection: new manufacturing technologies, regulatory clarifications, and shifting payer/provider dynamics are simultaneously expanding addressable demand and compressing time-to-scale for market entrants.
Clear Aligner (Invisible Braces) Market
For corporate leaders making investment, M&A, R&D, or GTM choices in 2026, the critical question is not whether the market will grow, but how value will be distributed among platform owners, materials suppliers, lab networks, and clinical channels. Our research converts that broad growth trajectory into actionable decisions by mapping value pools, operational breakpoints, and timing windows that matter for 12–36 month corporate agendas.
Clear Aligner (Invisible Braces) Market
Core strategic takeaways (what to act on in 2026)
- Re-evaluate your manufacturing footprint: direct-print, in-office production and hybrid lab models are viable disruptors to centralized production. Early pilots can deliver rapid learning about cost, quality, and regulatory burden.
- Prioritize regulatory and clinical evidence as a near-term moat: Class II device pathways (510(k)) remain the baseline for market entry in major markets — regulatory lead times and post-market evidence plans materially affect commercialization timelines and partner bargaining power.
- Design go-to-market choices around two levers — channel control (dentist/orthodontist relationships vs. DTC/consumer models) and service bundling (software + aligner + monitoring): winners will extract premium economics by integrating at least two of these elements.
- Adopt flexible pricing architectures tied to clinical outcomes and payment schedules — engaging payers and dental networks early prevents commoditization and supports higher average revenue per case in the mid-term.
- Use the 2026–2028 window to secure supply agreements for advanced polymers and to hedge against raw material volatility; material selection decisions will affect both margin and regulatory complexity.
What the PW Consulting report delivers — a practical toolkit
This study is built for the boardroom and the capture team alike. It blends rigorous market modeling with executable playbooks, including:
- Scenario-based market sizing (base, upside, downside) informed by historical 2020–2025 trends and a detailed 2026–2032 forecast horizon.
- Competitive landscaping with deep profiles of leading and fast-follow companies, including strategic intent, capabilities, and recent product/regulatory moves.
- Technology and operations roadmap covering thermoformed aligners, PETG and polyurethane material strategies, and the implications of direct 3D-printed aligners.
- Regulatory playbook detailing 510(k) pathways, evidence requirements, and practical checklist for product clearances and audits.
- Commercial and reimbursement modules: coding and billing guidance, provider engagement frameworks, and pricing sensitivity analyses for different customer segments.
- M&A screening framework and 100+ point commercial/operational diligence checklist designed for rapid target triage.
- Financial model templates (P&L, cash flow, unit economics) with plug-and-play inputs so teams can run internal scenarios without recreating the wheel.
Competitive landscape: players, pressure points, and differentiation
The market exhibits mid-to-high concentration: the top three players command a substantial share and the top five deepen that concentration further — an environment that favors scale economies, IP-backed differentiation, and channel control. Key players to watch and how they are reshaping competitive dynamics:
- Align Technology — continues to lead with strong brand recognition, broad clinical adoption and iterative product innovation. Recent product introductions targeting integrated mechanical features are intended to lock deeper clinical workflows into its ecosystem.
- Envista / Ormco (Spark) — leverages an orthodontics-focused commercial footprint and channel relationships; competitive emphasis is on clinician-centric features and lab partnerships.
- Institut Straumann (ClearCorrect) and Dentsply Sirona — incumbents with comprehensive dental portfolios; they compete by bundling prosthetic/implant capabilities and leveraging global distributor networks.
- Regional & fast-growth challengers (e.g., Angel Aligner, ALIGNERCO, CLEARPATH) — cost-efficient models and localized manufacturing provide footing in price-sensitive markets and create acquisition targets for larger platform players.
- Technology disruptors (notably LuxCreo with direct-print capability) — represent a structural threat to central labs by enabling validated, in-office production; successful commercial deployment would compress lead times and alter unit economics for consumables.
- Emerging innovators (OrthoFX, Dror Ortho-Design, MEM, Smarter Tooth) — they are differentiating through materials, clearance achievements, or service models; regulatory milestones through 2025–2026 are decisive for their scaling prospects.
Recent industry events underscore the dynamic competitive picture: FDA 510(k) clearances and FDA-cleared direct-print technology launches in late 2025 through early 2026 are accelerating product roadmaps and creating first-mover opportunities for in-office systems. These events increase optionality for providers and shift bargaining leverage among manufacturers, labs and clinic groups.
Regulation, materials and reimbursement — operational levers that change margins
Three operational levers will define profitability trajectories in the next planning cycle:
- Regulatory pathway management: Class II device classifications and 510(k) requirements are the gating items in major geographies. A pragmatic strategy combines pre-clearance clinical studies with a robust post-market surveillance plan to shorten commercialization lag while containing recall risk.
- Material strategy: polymer selection and supplier diversification are more than technical choices — they determine unit costs, aesthetic performance, and regulatory classification. Expect sustained demand for established polymer families, while alternatives that offer printing compatibility or enhanced clinical performance will command premium valuation.
- Reimbursement & coding: clear aligner treatment is supported by established dental procedure codes in major payor systems. Aligning case pricing to existing coding frameworks and developing payer-friendly evidence packages will accelerate adoption in insured cohorts.
Scenarios and decision frameworks for 2026
We present three actionable scenario archetypes for leadership planning (summary view):
- Consolidation-focused: incumbents double-down on channel control and M&A to defend share. Key actions: secure exclusive lab agreements; accelerate clinical evidence programs; deploy loyalty/pricing incentives.
- Platform-expansion: invest in vertical integration (printing hardware + software + consumables) to capture higher lifetime value. Key actions: pilot in-office printing; develop SaaS monitoring; lock strategic distributor partnerships.
- Cost-leadership & scale: scale centralized low-cost production and expand into price-sensitive geographies via local partnerships. Key actions: optimize supply chain, standardize processes, pursue high-volume labs.
Which scenario is right depends on your organization’s strengths in clinical trust, capital availability, and willingness to assume regulatory risk. Our report includes decision matrices that map company archetypes to scenario-fit and prioritized 12–18 month initiatives.
How to use this study in board-level decisions
- Investor diligence: use our M&A scoring and 5-year cash-flow templates to stress-test acquisition targets under regulatory and material-cost shocks.
- R&D prioritization: the technology roadmap highlights where incremental R&D spend produces outsized returns (materials that reduce treatment cycles, or software that shortens provider chair-time).
- Commercial pilots: the GTM playbooks enable 90–180 day pilots for in-office printing, clinician subscription models, or bundled service offerings with predefined KPIs for scale decisions.
- Risk mitigation: apply our risk heatmap to hedge supply chain dependencies, regulatory timelines, and payor coverage changes before committing capital.
Where alpha will be created (and what we deliberately withheld)
Alpha in the clear aligner market will accrue to organizations that simultaneously secure clinical trust, control material and manufacturing economics, and monetize recurring provider relationships. This report surfaces precise value pools across regions, material types, and patient segments, but we intentionally hold back granular segmentation figures and region/application splits here to preserve the full strategic narrative for the report subscribers. That granular segmentation — including detailed regional and application breakdowns, material-share trajectories, and lab-versus-in-office production economics — is available in the full report and the downloadable financial models.
Practical next step: if your 2026 planning cycle includes any allocation to orthodontic devices, schedule a strategic briefing with PW Consulting. We will walk your executive team through the full dataset, scenario models, and a 90‑day activation plan tailored to your corporate profile — because in a market growing at mid-teens CAGR, timing and detailed segmentation intelligence determine whether you capture upside or pay the acquisition premium.
For detailed analysis of this topic, please visit the official page: Clear Aligner (Invisible Braces) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


