



PW Consulting: TAVR market to grow at 7.26% CAGR, reaching $7.81M by 2032

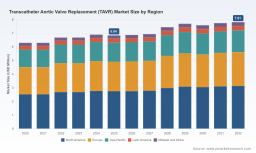
Transcatheter Aortic Valve Replacement (TAVR) Market — 2026 Strategic Preview
Executive snapshot
The TAVR landscape entering 2026 presents a classic market-of-mature-innovation: well-established platforms, accelerating regulatory expansion, a concentrated competitive structure, and renewed clinical ambition that together produce steady top-line growth and recurring strategic inflection points for manufacturers, payers, and health systems. Our base-year view (2025) captures a global market that has moved from a roughly USD 6.3 million scale in 2020 to about USD 6.8 million in 2025. Under the lens of our 2026–2032 forecast the market is projected to grow at a compound annual growth rate of 7.26%, reaching approximately USD 7.8 million by 2032. These aggregate trajectories mask meaningful pockets of clinical and commercial opportunity — and risk — that will determine competitive outcomes through the latter half of this decade.
Transcatheter Aortic Valve Replacement (TAVR) Market
Why this research matters to 2026 decision-makers
- Evidence-led market expansion: Recent pivotal regulatory approvals and trial readouts are changing which patient segments are considered treatable with TAVR and under what clinical governance structures. That expands addressable populations for incumbents and challengers alike, but it also changes payer calculus and hospital adoption thresholds.
- Consolidated competition with disruptive entrants: A small number of global device platforms continue to dominate capital and procedural flows, yet selective approvals and early-feasibility devices are beginning to open specialty niches (redo-TAVR, aortic regurgitation, ultra-low-profile delivery) that can alter procedure mix and procurement strategies.
- Reimbursement and coverage nuance: Payment policy and coverage determinations continue to be critical gating items for scaled commercial success. Procedural reimbursement and physician fee schedules materially influence hospital economics and therefore the speed of diffusion.
- Capital and clinical investments are now binary decisions: For hospital systems and manufacturers, choices about cath-lab capacity, training programs, inventory strategy, and clinical trial investment will determine whether 2026 becomes a period of opportunistic expansion or a moment of missed positioning.
Market dynamics — drivers, constraints and near-term catalysts
Three forces primarily shape the market dynamics for TAVR in 2026:
Transcatheter Aortic Valve Replacement (TAVR) Market
- Clinical indication expansion. Authorizations broadening the clinical envelope — including moves into earlier-stage or previously excluded pathologies — materially expand underlying demand curves. These shifts alter patient referral patterns and create new growth corridors for technologies validated in these populations.
- Technological differentiation. Incremental innovations (e.g., leaflet treatments, reduced-profile delivery systems, advanced sealing mechanisms) now function as commercial differentiators as much as clinical improvements. Devices that reduce vascular complications or simplify redo procedures will command premium positioning in contracting conversations.
- Market access & reimbursement complexity. National coverage frameworks and procedure-level reimbursement determine the speed at which approvals translate into procedure volumes. For 2026, coverage policies that require multidisciplinary adjudication and alignment with labeled indications mean manufacturers must integrate evidence, payer engagement and hospital economics into pre-launch plans.
Competitive landscape — what recent moves mean strategically
The vendor ecosystem remains concentrated around a handful of established platforms, but 2025–2026 developments underscore both defensive plays by incumbents and attack vectors for newer entrants:
Transcatheter Aortic Valve Replacement (TAVR) Market
- Edwards Lifesciences. The extension of the SAPIEN 3 platform into previously asymptomatic severe disease represents a material clinical expansion for a leading balloon-expandable franchise. Strategically, this shifts emphasis from late-stage procedural optimization to earlier referral and longitudinal follow-up pathways; it also raises the bar for evidence generation and post-market surveillance for competitors targeting the same patient cohorts.
- Medtronic. Expanded indications for redo-TAVR with the Evolut family unlock a reintervention market that has been poised for structured growth as the prevalence of prior TAVR implants increases. The ability to position a platform as “redo-compatible” is a potent commercial argument in tender and hospital procurement conversations, particularly where lifetime management pathways matter to catheterization labs and valve clinics.
- JenaValve. Gaining regulatory approval and beginning U.S. commercialization for a device specifically indicated in severe aortic regurgitation introduces a new therapeutic niche with high clinical need. Early commercial cases at tier-one centers signal a focused go-to-market that will test the economic and referral frameworks for this previously underserved indication.
- MiRus. Early feasibility activity around an ultra-low-profile delivery system suggests that next-wave competitors are concentrating on procedural access and vascular complication reduction as primary value propositions. If successful, these attributes could shift provider preferences in particular patient subgroups and catalyze new uptake patterns.
Strategic implications and recommended actions for 2026
Across manufacturers, providers, payers and investors, the 2026 playbook should prioritize the following strategic moves:
- For incumbent manufacturers: Double down on life-cycle clinical programs that validate differentiated outcomes in the expanded indications; translate clinical wins into hospital-level contracting tools (outcomes-based agreements, bundled-care pathways) and prioritize interoperability for redo strategies.
- For emerging device innovators: Focus initial commercialization in high-value centers of excellence to build real-world evidence quickly; pair limited commercial launches with rigorous comparative-effectiveness studies to shorten adoption timelines.
- For hospital systems and health networks: Re-evaluate capacity and center-of-excellence designations through the lens of lifetime valve management. Investments in dedicated structural heart teams and standardized post-procedure follow-up will protect margins even as device prices and procedural mixes evolve.
- For payers and policy-makers: Leverage clinical registries and value-based contracting to align payment with long-term outcomes and reintervention risk. Where investigational trials are covered under clinical study policies, ensure data collection plans are sufficient to reduce decision latency for broader coverage.
- For investors: Prioritize assets with clear differentiation in clinical outcomes or procedural ergonomics and those that minimize hospital integration friction. Watch for companies that can tangibly reduce total cost-of-care or demonstrably lower complication rates in real-world practice.
Decision frameworks and scenario triggers
To translate market intelligence into action, we recommend three operational decision frameworks for 2026:
- Evidence-to-Coverage timing model: Link clinical milestone calendars (PMA approvals, IDE trial readouts) to payer engagement triggers; use these to sequence geographic launches and prioritize real-world evidence collection.
- Procedure-economics sensitivity: Model hospital breakeven across variations in reimbursement, device purchase price, and complication rates. Use scenario outputs to support contracting strategies and training investments.
- Lifecycle management playbook: Map product iterations (e.g., leaflet chemistry, delivery profile, sealing systems) to five-year adoption arcs to inform R&D spend allocation and M&A targets.
What this report delivers — practical, operational tools
Our full TAVR market study is built as a decision-support kit for 2026 leaders. Key deliverables include:
- Transparent market-sizing and forecasting models (2026–2032) with sensitivity runs tied to alternative adoption and pricing scenarios.
- Competitive intelligence dossiers on incumbent and emerging manufacturers, including regulatory timelines, device differentiators, and commercialization footprints.
- Reimbursement and coverage intelligence: policy mapping, payer engagement playbooks, and decision timelines that affect adoption speed.
- Clinical & trial tracker: synchronized status of pivotal and registrational programs that alter addressable population assumptions.
- Go-to-market playbooks for device launches and hospital contracting templates for value-based arrangements.
- Interactive models and downloadable spreadsheets to run bespoke “what-if” analyses for procurement, pricing, and capacity decisions.
Note: this preview intentionally highlights strategic findings while omitting detailed line-item segmentation tables and granular regional/application splits. The full dataset, including the underlying tables, concentration metrics and downloadable models, is available on the report landing page.
Conclusion — strategic posture for 2026
2026 is a pivotal year in the development of the TAVR market: steady aggregate growth masks the strategic importance of timing, evidence, and payer alignment. Market winners will not be those who simply have the best device bench, but those who synchronise clinical evidence, commercial execution, and value messaging to hospitals and payers. Whether defending franchise share or carving out a niche, organizations must convert regulatory momentum into durable adoption — and do so with a clear picture of how reimbursement, redo-capabilities, and low-profile delivery changes the lifetime management of valve patients.
Next steps
Access the full PW Consulting TAVR Market report to download the models, review the segmented forecasts, and obtain the detailed competitor profiles and reimbursement matrices that underpin the strategic recommendations above. For tailored advisory support — including scenario modeling or competitive war-gaming sessions — our structural heart team is available to partner on implementation planning.
For detailed analysis of this topic, please visit the official page: Transcatheter Aortic Valve Replacement (TAVR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


