



PW Consulting: Foundry Coke Market to Reach USD 3.65 Billion by 2032 at 4.34% CAGR

Foundry Coke Market — Strategic Briefing for 2026 Decisions
Executive teaser
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our full Foundry Coke Market study. This briefing frames the near-term competitive and operational choices facing producers, buyers, and investors in 2026. It surfaces high‑confidence macro trends, supply constraints, regulatory inflection points and competitive moves that will determine which players capture margin and secure supply. Per the “trailer” design of this note, we demonstrate analytical depth while intentionally withholding granular segment tables and regional/application splits—those proprietary breakouts and scenario matrices are reserved for the full report.
Foundry Coke Market
Market snapshot: size, trajectory and what it means
The foundry coke market has shown steady expansion through the early 2020s, rising from a market base in 2020 to an estimated market size of approximately USD 2.71 Billion in our 2025 base year. Our forecast horizon (2026–2032) projects continued growth to about USD 3.65 Billion by 2032, reflecting a compound annual growth rate of 4.34% over the forecast period. This pace is neither hyper‑cyclical nor stagnant—rather it reflects a market that is maturing, with demand linked to structural manufacturing patterns, selective capacity investments and periodic price volatility driven by feedstock and trade dynamics.
Foundry Coke Market
For corporate leaders, the implication is clear: 2026 is a year for deliberate positioning. The market is large enough to justify investments in supply reliability and product quality, but concentrated enough in supplier capability and constrained inputs that first movers in logistics integration, quality differentiation (e.g., low‑sulfur, low‑ash products) and customer lock‑in can secure durable competitive advantage.
Foundry Coke Market
Supply‑side realities and raw material pressure
Supply fundamentals are a dominant theme. U.S. metallurgical coal production and coke capacity utilization patterns point to material constraints on incremental foundry coke availability. For context, U.S. metallurgical coal production reached roughly 67 million short tons in 2023; coke production utilization rates have historically been high, limiting the headroom available to shift tonnage into foundry‑grade production. Delivered coking‑coal prices to U.S. coke producers have historically traded at a premium to thermal coal—an observed average delivered price in recent history sits substantially above electric‑sector coal pricing—adding cost pressure to coke margins and making feedstock procurement a strategic priority.
Export dynamics also matter: U.S. metallurgical coal continues to be actively traded internationally, and quarterly export price movements have shown meaningful volatility through 2025. For buyers and producers alike, this creates two simultaneous imperatives for 2026: (1) develop supply‑chain hedging and contracted feedstock strategies to buffer price spikes, and (2) evaluate feedstock mix and technological options that improve yield and reduce ash/sulfur penalties.
Regulatory and trade dynamics shaping 2026 choices
Policy and trade instruments are a second—often overlooked—driver of strategy. In the U.S., NESHAP standards and related permitting and performance‑testing requirements impose capital and operating obligations on coke oven operations. Compliance timelines, emission measurement protocols and observer‑certification requirements increase the fixed‑cost threshold for plant operation and retrofits. Separately, active trade remedies—anti‑dumping and countervailing duty measures—continue to shape import economics and protect domestic foundry coke producers from low‑priced foreign offers.
For executives this means compliance is not just a cost center: it is a strategic barrier to entry and a source of commercial leverage. Firms that proactively invest in compliant process management, continuous emissions monitoring and transparent auditing will face lower regulatory execution risk and may unlock commercial opportunities with risk‑averse buyers.
Competitive landscape — profile and implications
The market is neither atomistic nor monopolistic. Our concentration metrics indicate a moderate level of market share aggregation among leading players (top‑three and top‑five share metrics show meaningful presence without full consolidation). This structure fosters both competitive tension and regional niches where scale plus service excellence win.
-
ABC Coke — Based in Birmingham, Alabama, ABC Coke is a leading merchant producer in the United States with a strong reputation for producing low‑sulfur, high‑quality foundry coke for cupola and grey‑iron casting customers. Their merchant model and product positioning make them a go‑to supplier for foundries seeking consistency and regulatory certainty. (Profile source: https://drummondco.com/operations/coke/ABCCoke.aspx)
-
SunCoke Energy — A vertically integrated producer headquartered in Lisle, Illinois, SunCoke expanded to dedicated foundry coke production in 2020 and operates facilities capable of serving cupola customers across construction, automotive and industrial casting segments. Their integration into the metallurgical value chain gives them strategic flexibility on feedstock allocation and product routing. (Profile source: https://www.suncoke.com/)
These incumbents illustrate two viable strategic archetypes in 2026: merchant producers that prioritize foundry quality and service, and vertically integrated players that optimize across metallurgical value streams. A third viable archetype—smaller specialty producers—competes on ultra‑low impurities and fast technical support for specialized casting applications.
Demand dynamics and end‑market signals
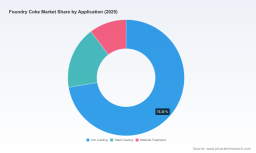
Demand for foundry coke is ultimately derived from casting activity across iron and steel casting and from material‑treatment applications. Near‑term demand sensitivity is tied to cyclical end markets—automotive production, construction activity and industrial equipment manufacturing—but structural demand is supported by the need for high‑quality carbonaceous inputs in foundry processes. In 2026, buyers increasingly emphasize product consistency, emissions footprints and supply resilience over spot price alone.
Event and ecosystem signals
Industry gatherings and trade exhibitions remain critical nodes for technical exchange and deal formation. Recent events that shaped thinking going into 2026 included the Eurocoke Summit (December 2025, Barcelona), a forum convening senior technical and commercial leaders across met‑coke and coal industries, and the 26th China (Guangzhou) International Casting Products & Foundry Industry Exhibition (May 2026), where foundry coke and related casting inputs were central topics. These venues underscored innovation priorities—process optimization, coke quality measurement and low‑emissions operations—and the cross‑border nature of sourcing and technology transfer.
Strategic implications for 2026 decision‑makers
Our analysis identifies five decisions that should be prioritized by management teams this year:
-
Secure feedstock through diversified contracting: Locking in metallurgical coal terms, colocated supply agreements, or partial tolling arrangements can blunt price volatility and protect margins.
-
Prioritize product quality certification: Buyers increasingly demand consistent low‑sulfur and predictable ash characteristics. Investments in QA/QC, third‑party certification and client‑facing data packages support premium pricing and longer contracts.
-
Evaluate incremental vertical integration or partnerships: For trading houses and producers, closer ties with coke ovens, coal suppliers or scrap metallurgy partners can create optionality to shift output between metallurgical and foundry channels as market signals change.
-
Model regulatory and trade scenarios: Given active anti‑dumping measures and domestic emissions rules, scenario planning should include compliance cost overlays and potential trade‑policy shifts to understand margin sensitivity to tariffs and permit timing.
-
Invest in logistics resilience and value‑added services: Because customer lock‑in often stems from reliable delivery and technical support, firms that expand terminaling, blending and just‑in‑time supply capabilities will win share among foundries focused on operational continuity.
What PW Consulting’s full report delivers (teaser)
The full Foundry Coke Market report contains pragmatic tools and datasets you will use to act in 2026. Highlights include:
-
Demand and supply models calibrated to historical 2020–2025 data and multiple scenarios through 2032, including sensitivity to feedstock price shocks and regional policy changes.
-
Competitive benchmarking that profiles capacity, product portfolios, service models and go‑to‑market plays for the leading producers and structurally important regional suppliers.
-
Commercial playbook—contract structures, price‑indexing approaches, and a short list of tactical supplier negotiation levers that have proven effective in recent cycles.
-
Operational diagnostics—QA/QC KPIs, emissions compliance checklists and a roadmap for retrofits or upgrades that improve product grades and reduce regulatory risk.
-
Interactive scenario dashboards (subscriber access) that allow clients to simulate outcomes from alternate assumptions on coal prices, production utilization and trade measures.
Note: Detailed regional and application‑level split tables, unit‑price curves by vintage, and proprietary segmentation matrices are excluded from this public briefing and are provided exclusively in the full report to paying subscribers.
Concluding guidance
2026 is a decisive year for actors in the foundry coke value chain. The market’s moderate growth trajectory (CAGR ~4.34% over 2026–2032) paired with constrained feedstock supply, active regulatory regimes and competitive differentiation around product quality create asymmetric opportunities for companies that prepare now. Tactical moves on contracting, product certification and logistics, combined with scenario‑based capital planning, will separate winners from the rest.
For practitioners ready to translate this briefing into an executable 90‑day plan—supplier scorecards, hedging playbooks, or a bidders’ short list—PW Consulting’s full Foundry Coke Market report and advisory services provide the detailed data and modeling capabilities you will need to de‑risk 2026 investments and capture near‑term share. Contact PW Consulting to obtain the full report and access the interactive tools underpinning these insights.
For detailed analysis of this topic, please visit the official page: Foundry Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


