



PW Consulting: Lactulose Market to Reach USD 704.23M by 2032 at 6.4% CAGR

Lactulose Market 2026: Strategic Imperatives for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise but strategically rich preview of our latest Lactulose Market study. Over the next pages you will find the high‑value, decision‑centric perspectives that matter to C‑suite executives, corporate strategists, business development teams, and investor committees planning for 2026 and beyond. This briefing is intentionally panoramic — demonstrating our analytical depth while reserving the detailed segment matrices and granular datasets for the full report.
Lactulose Market
Market trajectory at a glance
The Lactulose market has moved from a modest specialty chemical into a stable, mid‑single‑digit growth market driven by pharmaceutical demand, broadening therapeutic use, and steady integration into functional food and beverage applications. Our analysis places the market at approximately USD 456 million in the base year (2025), following steady expansion from the start of the decade. Under our base forecast scenario the market grows at a compound annual growth rate (CAGR) of roughly 6.4% through the 2026–2032 horizon, reaching an estimated USD 700+ million by 2032.
Lactulose Market
Several implications follow immediately: the market is large enough to support differentiated product strategies (formulation, service, regulatory pedigree) yet remains far from highly concentrated. Our concentration metrics indicate a fragmented supplier landscape, where the top three and five suppliers account for only a modest share of total revenue — a structural condition that favors both nimble niche players and accretive consolidators.
Lactulose Market
Why this study matters for 2026 decisions
- Resource allocation and capacity planning: With predictable, mid‑single‑digit growth, firms can plan multi‑year capital and capacity investments with reasonable confidence — but must account for episodic raw‑material volatility that can materially impact margins.
- Regulatory pathway optimisation: Lactulose’s long regulatory history in major markets creates both barriers and opportunities. Understanding the evolving NDA/ANDA landscape and manufacturer authorisation profiles allows faster market entry and lowers compliance risk.
- M&A and partnership timing: Fragmentation creates arbitrage for buyers and JV partners. Our scenario work highlights windows in which bolt‑on acquisitions or exclusive distribution agreements create outsized returns on invested capital.
- Pricing and contract strategy: Given the market’s growth profile, pricing discipline combined with hedged raw‑material sourcing (see below) will preserve margins while enabling selective volume growth through institutional contracts.
Demand drivers and supply dynamics
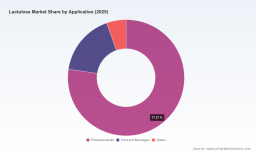
Pharmaceutical applications remain the primary demand engine: hospital use, chronic therapeutic prescriptions, and expanding OTC and supplement channels collectively sustain base volumes. Concurrently, food & beverage innovation — particularly in digestive health positioning — is creating high‑value product windows that reward proven supply chains and compliant ingredient sourcing.
On the supply side, the primary input is lactose. Edible lactose price volatility, as recorded in USDA commodity reporting, has direct and measurable implications for manufacturer margins and contract quoting. We detail hedging approaches and procurement playbooks in the full report, but the strategic takeaway for 2026 is clear: firms that integrate upstream raw‑material commitments (secure supply, multi‑year contracts, or tolling agreements) will outperform peers on margin stability.
Regulatory landscape — continuing to shape competitive advantage
Lactulose benefits from an established regulatory track record, with initial approvals decades ago and ongoing lifecycle activity through NDAs and ANDAs. For pharmaceutical manufacturers and suppliers, maintaining and communicating regulatory compliance is now table stakes. Our fieldwork and regulatory scans identify two practical edges:
- Manufacturers with long‑standing authorisations and inspection histories reduce buyer due diligence friction and command preferred supplier positioning for hospital and prescription channels.
- Proactive monitoring of ANDA/NDA filings unlocks opportunity windows for branded generics, exclusive distribution, or authorised generic rollouts ahead of competitor entry.
Notable compliance signals we track include sustained manufacturer authorisations in European jurisdictions, EDQM Certificates of Suitability, and long‑standing FDA establishment approvals — credentials that materially shorten time‑to‑contract in regulated markets.
Competitive landscape: who matters and why
The sector comprises a mix of specialised API producers, global pharmaceutical houses, branded product manufacturers, and regional generics suppliers. Key participants include long‑established GMP producers and diversified pharmaceutical firms. Strategic archetypes we observe:
- Specialist API manufacturers (e.g., BIOFAC A/S): These firms focus on compliant, large‑scale API production and hold manufacturing authorisations and inspections that make them natural partners for pharmaceutical customers seeking EP/USP compliant material.
- Global distributors and contract manufacturers (e.g., Relax Lactulose): Entities that combine production capability with regulatory dossiers and distribution networks — critical for rapid market penetration and supply continuity.
- Big pharma and diversified suppliers (e.g., Fresenius Kabi, Abbott, Sanofi): These players leverage scale, branded products, and hospital distribution to maintain durable demand — often focusing on finished dosage or institutional channels.
- Generics-focused firms and regional API producers (e.g., Teva, Chartwell RX, Lactose India): Target price‑sensitive segments, with business models optimized on cost and distribution advantage in specific geographies.
Our competitive benchmarking evaluates firms across four dimensions: regulatory credentials, supply reliability, cost competitiveness, and route‑to‑market strength. In 2026, competitive differentiation will be driven more by the first three than by pure scale — giving well‑credentialed mid‑tier suppliers outsized strategic opportunities.
Report content — what’s inside (practical, actionable modules)
The full PW Consulting report is designed as an operational decision tool. Highlights include:
- Historical demand and supply reconciliation (2020–2025) and scenario‑based forecasts to 2032, with sensitivity to raw‑material price swings and regulatory event risk.
- Commercially useful market sizing and pricing models (including invoice and landed cost build‑ups) that allow rapid scenario re‑runs for procurement and commercial teams.
- Regulatory tracker and dossier gap analysis: a practical checklist for market entry, bid readiness, and accelerated approvals.
- Supplier scorecards and capability maps: comparative strengths and risk flags for key producers and distributors.
- A 12‑point operational playbook for 2026: recommended actions for procurement, manufacturing, regulatory affairs, commercial, and M&A teams — including contract archetypes and KPIs.
To preserve strategic value for paying subscribers, the report omits granular public reproduction of regional and application splits in this preview. If your decision calculus depends on precise regional volumes, application‑level pricing, or company‑level revenue shares, the full dataset and downloadable models are available with the report.
Strategic moves that pay in 2026
- Secure upstream input economics: Move from spot purchases to blended sourcing (long‑term contracts + option volumes) to stabilize margins against lactose price swings.
- Prioritise regulatory credentials as a commercial lever: Acquire or partner with manufacturers holding EDQM/CEP or long‑standing FDA inspection histories to reduce time‑to‑market.
- Segmented portfolio plays: Differentiate between institutional (hospital/prescription) and consumer‑facing channels; allocate marketing and distribution capital accordingly.
- Value‑chain partnerships: Consider tolling, contract‑manufacturing, or exclusive distribution agreements to enter new geographies quickly while preserving capital.
- Selective M&A and bolt‑ons: Target small, compliant API producers with scalable capacity and regulatory dossiers — consolidation lifts margin baselines in a fragmented market.
Methodology and confidence
Our projections combine bottom‑up market reconciliation (manufacturing capacity, product flows, and known contract wins) with top‑down demand modelling calibrated against historical sales and regulatory filings. Scenario testing includes commodity price shocks, regulatory milestone events, and alternative uptake curves for non‑prescription applications. We attach a medium‑to‑high confidence level to the base case and provide downside/upside scenarios for stress testing.
Final thought — the advisor’s edge for 2026
Lactulose occupies a sweet spot for 2026 strategic plans: the market is substantial, growing predictably, and open to value creation through supply‑chain optimisation, regulatory investment, and targeted partnerships. Companies that treat regulatory credentials and upstream procurement as strategic levers — rather than operational afterthoughts — will capture superior margin and market share gains.
For executives ready to act, our full report supplies the granular regional and application breakouts, company scorecards, price decks, contract templates, and the downloadable model you need to run your own scenarios. This preview demonstrates the analysis and the implications — the full intelligence pack provides the data to execute.
Contact PW Consulting to access the complete Lactulose Market report and the accompanying decision toolkit for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Lactulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


