



TMS Market to Reach USD 1,370M by 2032 — PW Consulting Insight

Transcranial Magnetic Stimulators (TMS) Market: Strategic Preview for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, actionable preview of our authoritative market study on Transcranial Magnetic Stimulators (TMS). This briefing synthesizes the macro trajectory, competitive dynamics, and regulatory-reimbursement inflection points that will shape corporate decision-making in 2026. It is designed as a high-value “trailer”: it demonstrates the analytical depth you can expect from the full report while deliberately withholding the proprietary, granular segmentation tables that clients use to make tactical choices.
Transcranial Magnetic Stimulators (TMS) Market
Market trajectory at a glance
Between the historical window (2020–2025) and our forecast horizon (2026–2032), the TMS market demonstrates sustained, above-average growth driven by a combination of regulatory expansion, reimbursement clarity, and accelerating clinical adoption. On a macro level, the global market grew from roughly USD 583 million in 2020 to about USD 864 million in 2025 (base year), and our model projects continued expansion to approximately USD 1.37 billion by 2032. This path corresponds to a compound annual growth rate (CAGR) of 9.45% across the forecast period.
Transcranial Magnetic Stimulators (TMS) Market
These headline numbers reflect a market moving from specialized clinical applications toward broader acceptance in psychiatric and neurological care pathways. The growth is neither linear nor uniform: policy milestones, reimbursement roll-outs, and device-level innovations create uneven pockets of opportunity and near-term volatility in adoption curves. Understanding where and when these pockets emerge is precisely what our full study maps for executives.
Transcranial Magnetic Stimulators (TMS) Market
Why this matters for 2026 corporate strategy
- Timing of market entry and product investment — With Medicare and commercial payers implementing CPT codes for TMS treatment beginning November 1, 2025, the commercial dynamics in 2026 will favor vendors with ready-to-deploy clinical workflows and billing infrastructures. Companies planning product launches, protocol changes, or accelerated rollouts must align commercial readiness to capture front-loaded demand.
- Reimbursement-enabled scale — Reimbursement clarity reduces barriers to utilization but raises the bar for operational capability. Organizations that standardize billing, documentation, and prior-authorization processes will win share in ambulatory and hospital outpatient settings during 2026.
- Clinical differentiation vs. commoditization — As indications expand (including adolescent cohorts), device makers will need to demonstrate meaningful clinical or workflow differentiation — e.g., accelerated protocols, navigation systems, or integrated data capture — to avoid downward pricing pressure.
- M&A and partnership windows — The market concentration metrics indicate a moderately consolidated field with room for bolt-on acquisitions and strategic alliances. Buyers should model synergies using both device economics and downstream revenue capture from recurring treatment sessions.
Competitive landscape: leaders, challengers, and tactical moves
Our competitive analysis synthesizes product clearances, clinical positioning, and go-to-market strategies of the principal market participants. The field includes established manufacturers with broad clearance footprints and technology specialists that differentiate on modality, navigation, or indications.
- BrainsWay Ltd. — Known for Deep TMS systems and recent regulatory momentum, including adolescent indications and accelerated protocols granted in 2025. These clearances reposition BrainsWay as a growth-oriented leader for expanded clinical pathways.
- Neuronetics, Inc. — Offers a well-established therapy platform with a growing emphasis on real-world evidence. Recent presentations of registry data underscore the company’s focus on outcomes-driven adoption.
- Magstim Company Limited — Competes with systems emphasizing rapid therapy and broad clinical indications, maintaining strong presence in both clinical and research settings.
- MagVenture (Tonica Elektronik A/S) — Recent adolescent indication clearances have strengthened its U.S. competitiveness and expanded addressable patient cohorts.
- Nexstim Plc — Differentiates with navigated therapies and precision targeting, a strategic lever for clinicians emphasizing individualized treatment planning.
- eNeura, neurocare group, Neurosoft — Each brings verticalized capabilities or niche indications (e.g., migraine, adolescent indications, cloud-enabled platforms) that can be attractive acquisition targets or partnership candidates for larger OEMs.
Importantly, market concentration is meaningful but not prohibitive for disruptors: the top three players account for just over half of market share, and the top five represent two-thirds of the market. That concentration profile signals both the defensive power of incumbency and achievable entry points for focused challengers, especially those who combine clinical differentiation with optimized commercialization.
Regulatory and reimbursement inflection points to watch
- Expanded FDA indications — The FDA’s 2025 clearances for adolescent indications and multiple cleared systems under 21 CFR 882.5805 materially expand the treated population and reduce regulatory uncertainty for device firms pursuing label expansion.
- Reimbursement evolution — As of November 1, 2025, TMS procedures are covered through established CPT codes (including codes for initial planning, treatment sessions, and motor threshold determination). This removes a major payer barrier and converts clinical interest into billable demand.
- Local program constraints — Payer implementations vary. For example, certain public programs retain prior-authorization requirements and beneficiary limits, which can create geographic variability in uptake. Payers’ operational policies and coverage criteria will drive where early volume concentrates in 2026.
Practical content included in the full PW Consulting report
The full market study goes far beyond headline projections to provide the operational intelligence executives need to act in 2026. Key deliverables include:
- Methodology and assumptions: transparent modeling that blends historical market activity, device utilization rates, clinical adoption curves, and reimbursement timelines.
- Scenario-based forecasts: base, upside, and downside cases to stress-test investment timetables and capacity plans across different payer and regulatory conditions.
- Commercial playbooks: go-to-market tactics for hospital systems, outpatient clinics, and integrated behavioral health networks — including clinician training pathways and coding/billing templates.
- Technology valuation matrices: comparative tables that assess devices by clinical features, workflow integration, capital intensity, and data capture capabilities.
- Competitive intelligence dossiers: validated profiles and strategic options analysis for each major vendor, including recent regulatory wins and evidence-generation programs.
- Transaction support materials: valuation guidance, synergy estimates, and due-diligence checklists tailored for strategic buyers and private equity investors.
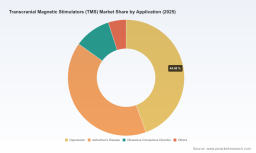
To preserve proprietary advantage, this preview intentionally omits the detailed splits by region, type, and application that subscribers rely on for market entry and channel planning. Those segmentation matrices — along with supplier-by-supplier revenue estimates, price benchmarking, and clinic-level utilization models — are available in the complete report.
Near-term tactical recommendations (for 2026 execution)
- Prioritize cash-flow positive deployments: Focus on channels where billing workflows are established and reimbursement is predictable; optimize training to reduce session abandonment.
- Invest in outcomes and data capture: Real-world evidence will be a differential asset. Build registries and clinician reporting to support payer negotiations and to justify premium positioning.
- Explore targeted partnerships: Consider alliances with navigated-therapy specialists, outpatient clinic networks, or digital therapeutics providers to create integrated care propositions.
- Calibrate M&A diligence to concentration dynamics: Small- to mid-sized assets with clear clinical differentiation or U.S. reimbursement-readiness can accelerate scale without the multiple pressure of acquiring a top-three incumbent.
What to expect from PW Consulting’s full deliverable
Subscribers will receive the complete dataset (annualized market estimates by region, modality, and clinical application), full competitive modeling, and an implementation toolkit that includes commercial templates and scenario analyses tailored to both device OEMs and downstream service operators. Our methods blend primary interviews, payer-policy mapping, device clearance tracking, and a proprietary utilization model calibrated to real-world evidence presented at major clinical meetings.
Conclusion — a pragmatic lens on opportunity and risk
The TMS market in 2026 presents a distinctive mix of accelerating demand and operational complexity. Macro growth is robust — a near-double-digit CAGR and a doubling-plus market size over the coming decade — but the path to value capture is dependent on surgical execution across regulatory, reimbursement, and clinical dimensions. Executives who combine differentiated clinical value with reimbursement-operational readiness will be positioned to translate market momentum into sustainable share gains.
For access to the complete segmentation matrices, device-level estimates, and our actionable commercial playbooks, visit PW Consulting’s full Transcranial Magnetic Stimulators (TMS) Market report. The detailed intelligence there is the operational backbone that will inform high-confidence decisions in 2026.
For detailed analysis of this topic, please visit the official page: Transcranial Magnetic Stimulators (TMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


