



PW Consulting: Sorghum Seed Market Poised for 5.5% CAGR to 2032

Sorghum Seed Market 2026: Strategic Imperatives for Growth and Resilience
Executive snapshot — why this matters for 2026 decision cycles
As agribusinesses and seed investors finalize budgets and strategic plans for 2026, the sorghum seed domain is moving from a niche defensive play into a mainstream portfolio consideration. Our PW Consulting analysis (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) shows the global sorghum seed market expanding at a compound annual growth rate (CAGR) of 5.5% through the forecast period. Measured in USD (Million), the market has grown from a baseline of 1,000 in 2020 to 1,250 in 2025 and is projected to reach approximately 1,817 by 2032 under the central case.
Sorghum Seed Market
These headline dynamics — steady growth, resilience to systemic shocks, and strong pockets of demand — are sufficient cause for corporate strategy teams to treat sorghum not as a one-off tactical play but as a component of medium-term product, channel and M&A plans. However, meaningful decisions require more than topline CAGR; they require line-of-sight to trait economics, channel economics, regional demand elasticity and competitive positioning. That depth is what our full report is designed to deliver.
Sorghum Seed Market
Market dynamics shaping 2026 strategies
-
Demand-side momentum: The market’s growth is anchored in diverse end-uses — animal feed, human food applications and industrial uses (including biofuel). Shifts in dietary protein demand and downstream processing economics are re‑allocating value across these uses, creating differentiated margin pools for seed suppliers with tailored varietal portfolios.
Sorghum Seed Market -
Supply-side innovation: Seed companies that combine hybrid vigor with trait packages (drought tolerance, herbicide resistance, stay‑green phenotypes and improved threshability) are commanding faster adoption curves. Recent product launches leveraging advanced genomics indicate an acceleration of breeding cycle efficiency and a steeper diffusion curve for premium hybrids.
-
Trade and policy tailwinds: Recent USDA program updates and variety listings are changing the economics of exportable grain and the incentives for certain varieties in subsidy-linked programs. Simultaneously, export opportunity forecasts to major importers are materially supporting grower interest in high-performing sorghum, altering planting decisions in producing regions.
-
Price and risk volatility: Cash price movements at key elevators and regional differentials continue to influence seed uptake timing and varietal mix. Effective risk management — from pricing contracts to logistical hedging — is now a core competence for seed distributors and upstream suppliers.
Competitive landscape — what the leading players signal
The market exhibits moderate concentration: the top three firms account for a meaningful but not dominant share, and the top five increase that concentration materially. This structure creates both room for differentiated positioning and a clear path for consolidation or strategic alliance formation.
-
Corteva Agriscience (Indianapolis, USA) — an established player leveraging legacy brands and trait pipelines. Recent launches of drought‑tolerant hybrids underscore their strategy to protect acreage in water‑stressed geographies and to capture premium seed premiums through genetics and trait licensing.
-
KWS SAAT SE & Co. KGaA (Einbeck, Germany) — focuses on early‑maturity and stability traits attractive to European and certain international producers. Their breeding emphasis on adaptation and yield stability complements regional cropping systems where risk‑adjusted yield is the primary purchasing driver.
-
Advanta Seeds (Dubai/US operations) — a global hybrid supplier with broad geographic reach. Their commercial footprint across diverse agroecologies positions them well to arbitrage regional price and margin differentials and to scale fast‑growing hybrids through licensed networks.
-
Bayer CropScience (Monheim, Germany) — brings integrated seed and crop protection capabilities to sorghum, emphasizing agronomic traits that reduce downstream handling costs (standability, threshability, stay‑green) — features that translate into farm‑gate value and adoption levers.
-
S&W Seed Company (Longmont, USA) — a specialist hybrid player concentrating on proprietary traits including herbicide resistance and portfolios aimed at animal protein and healthier consumer diets. Their recent strategic review and portfolio refocus signal an intent to sharpen core competencies rather than pursue broad diversification.
Collectively, these players illustrate two strategic archetypes that matter for 2026 planning: (1) integrated multinationals that leverage R&D scale and channel breadth to commercialize premium trait stacks, and (2) focused specialists that extract margin through proprietary traits and targeted market niches. Both archetypes will pursue different partnership, licensing and M&A playbooks as the market expands.
Recent developments with structural implications
-
S&W Seed Company initiated a strategic alternatives review in early 2025, refocusing on core U.S. sorghum and high‑margin trait portfolios — a move that could create short‑term transactional noise but longer‑term concentration opportunities for premium assets.
-
Corteva launched a drought‑tolerant hybrid in 2025 using advanced genomics; this elevates the technology baseline for market entrants and changes the minimum competitive offering for water‑limited regions.
-
USDA and the United Sorghum Checkoff Program updated variety listings and eligibility for program support in 2026, affecting program participation and the attractiveness of certain varieties under loan and deficiency programs.
-
Macro indicators such as rising export prospects to key markets have been reported alongside persistent price dispersion at local elevators — factors that together increase arbitrage opportunities but also amplify execution risk for exporters and seed distributors.
Key strategic implications for 2026 planning
-
Product and portfolio strategy: Prioritize breeding and licensing investments in traits that address water stress, harvest efficiency and market‑specific quality attributes. Portfolio pruning is likely to create value for firms that redeploy capital into high‑conviction hybrids.
-
Channel and go‑to‑market: Strengthen distributor economics in regions where price volatility drives short planting windows. Digital advisory and seed placement services can increase effective market share without equivalent increases in physical footprint.
-
M&A and alliances: Expect continued interest in bolt‑on acquisitions of breeding assets and trait licenses. For buyers, disciplined payoffs must be tied to demonstrable uplift in germplasm value and route‑to‑market synergies.
-
Risk management: Incorporate price‑scenario planning and targeted hedging into commercial programs. Regulatory and program changes (e.g., variety eligibility for support programs) must be tracked proactively as part of commercial contracts.
What PW Consulting’s full report delivers — practical, executable intelligence
Our Sorghum Seed Market study is structured to convert insight into action. The full deliverable includes:
-
Transparent market sizing and methodology (historical 2020–2025 benchmarking; base year 2025; forecast 2026–2032) with sensitivity scenarios reflecting commodity price and policy shifts.
-
Competitive benchmarking with capability heatmaps covering R&D pipelines, trait portfolios, channel reach and financial posture for primary market participants.
-
Commercial playbooks for four archetypal players (incumbent multinationals, regional leaders, focused specialists and new entrants), including suggested go‑to‑market moves, pricing strategies and potential alliance partners.
-
Scenario‑based M&A and investment roadmaps, complete with target profiles, valuation heuristics and integration risk checklists tailored to 2026 market realities.
-
Operational diagnostics and a set of KPI dashboards to monitor adoption curves, channel performance and trait premium realization on a rolling quarterly cadence.
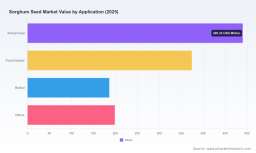
To preserve the strategic advantage for subscribing clients, the report intentionally withholds the granular sub‑segment tables and regional application splits from public summaries. Those data are available in the full report appendices and the interactive dashboards on our client portal.
Recommended near‑term moves for executives
-
Run a 90‑day portfolio stress test: Identify underperforming varieties, reallocate seed‑pipeline spend toward high‑probability trait programs, and establish stop‑loss criteria for low‑velocity SKUs.
-
Lock strategic partnerships: Negotiate conditional licensing deals that align trait payments with realized farm‑level premiums to reduce upfront R&D exposure.
-
Operationalize market intelligence: Deploy the report’s KPI dashboards to monitor export demand signals, elevator‑level price deviations and variety eligibility announcements that affect planting incentives.
-
Prepare M&A playbooks: Identify 2–3 bolt‑on targets and establish valuation ranges tied to royalty flows and trait capture models prior to market re‑rating events.
Closing — why access to the full study matters now
The sorghum seed market presents an atypical blend of steady aggregate growth and highly local execution risk. The headline CAGR of 5.5% masks important heterogeneity across traits, channels and geographies that will determine winners and losers through 2032. PW Consulting’s full Sorghum Seed Market report translates the top‑line trajectory into the specific levers that corporate leaders must pull in 2026 — from R&D prioritization and licensing strategies to channel economics and M&A timing.
For strategy teams, the difference between opportunistic and disciplined capture is access to the granular adoption curves, price‑elasticity tables and competitor capability matrices that we reserve for report subscribers. To request the full report, interactive dashboards and a tailored executive briefing for your leadership team, please follow the link on our publication page.
For detailed analysis of this topic, please visit the official page: Sorghum Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


