



PW Consulting: Stem Cell Media to Reach USD 856M by 2032, 8.97% CAGR (2026-2032)

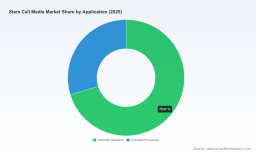
Stem Cell Media Market — Strategic Preview for 2026 Decision-Makers
As cell- and gene-based therapeutics move from promise to practice, the stem cell media market has consolidated into a mission-critical supply layer that determines both clinical credibility and commercial scalability. Our PW Consulting Stem Cell Media Market study (base year 2025; forecast 2026–2032) shows a market expanding at a compound annual growth rate of 8.97% — rising from roughly USD 478 million in 2025 to an estimated USD 856 million by 2032. This trajectory is not a passive trend: it reflects convergent forces — regulatory stringency, product standardization, industrial-scale manufacturing, and new clinical and industrial use cases — that will shape commercial strategy through 2026 and beyond.
Stem Cell Media Market
Why this review matters to C-suite and product leaders in 2026
-
Investment prioritization: With near-term market growth accelerating, leaders must decide whether to expand in-house media capabilities, secure preferred supply agreements, or pursue M&A to gain vertical control. The margin and time-to-market impact of those decisions is amplified by the market’s steady upward slope and clear regulatory direction.
Stem Cell Media Market -
Regulatory readiness equals commercial access: cGMP compliance and full traceability of raw materials are now prerequisites for submissions supporting advanced therapies. Companies that neglect validated media supply chains will face delayed approvals and constrained reimbursement conversations.
Stem Cell Media Market -
Operational leverage: Automation and process engineering are shifting cost structures. Our analysis highlights production workflows where automation can reduce labor costs by up to 70%, creating new unit-cost thresholds and enabling economically viable scale-up for clinical and industrial-grade media.
-
Partner and supplier selection: The market concentration and vendor capabilities observed in the report define bargaining power and partnership opportunity windows; choosing the right supplier archetype (platform provider vs. specialist innovator) is a strategic lever for both biotechs and CMOs.
What PW Consulting’s report gives you — practical, decision-ready content
-
Transparent macro sizing and a seven-year forecast model (2026–2032) that you can stress-test against your product roadmap and capital plan.
-
Scenario-led commercial playbooks that map actions to three industry trajectories (accelerated adoption, regulatory delay, and supply-constrained outcomes), with clear triggers for pivoting strategy.
-
Regulatory and reimbursement toolkit — pragmatic checklists and documentation templates that shorten time-to-compliance for cGMP and traceability expectations.
-
Supplier architecture and risk assessment — vendor scorecards, testimony-weighted reference checks, and contractual terms you should insist on for security of supply.
-
Go-to-market playbooks for research-grade vs. industrial-grade segments, including recommended pricing levers, channel models, and account penetration strategies.
-
M&A and partnership candidate shortlists built from capability maps, market share dynamics, and integration risk assessments.
-
Operational benchmarks: cost-per-liter ranges, automation impact models, and quality-control KPIs for manufacturing scale-up.
Market dynamics and structural drivers driving value in 2026
-
Regulatory and quality escalation: Regulators increasingly expect media used in clinical and commercial stem cell products to be cGMP-compliant with complete raw-material traceability. This changes procurement from a cost exercise into a compliance and risk-mitigation exercise.
-
Ethical and reproducibility norms: Chemically defined and animal-origin-free formulations are fast becoming the default design point, both for ethical reasons and to reduce batch-to-batch variability. This favors suppliers who have invested in defined formulations and validated supply chains.
-
Automation as a margin lever: Advances in production automation are not just productivity wins. They recast the economics of scale, lowering labor-driven variability and creating predictable cost curves that enable aggressive pricing in industrial applications.
-
Reimbursement conditionality: Payers and national health systems increasingly request evidence of validated manufacturing inputs (including media) before agreeing coverage. Early alignment on media validation can shorten reimbursement timelines for therapy developers.
-
Infrastructure and reproducibility: Xeno-free and chemically defined products address the reproducibility gap that has historically slowed technology transfer from the bench to GMP lines. Firms that standardize on such media reduce time-to-clinic and post-approval manufacturing risk.
Competitive landscape — how to interpret supply-side signals
The market exhibits moderate concentration: the combined market share of the top three suppliers sits comfortably above majority control, with the top five consolidating a clear dominant position. That structure creates both stability and strategic pressure: incumbents control distribution channels and regulatory credibility, while challengers compete on specialization, cost, and co-development agility.
-
Platform leaders (Thermo Fisher Scientific, Merck KGaA, Lonza Group AG): These players pair broad distribution, regulatory credentials, and integrated reagent portfolios. Their strategic advantage is the ability to supply validated, GMP-compatible media alongside platform services (analytics, QC, scale-up), making them default partners for large biopharma and CMOs.
-
Specialist innovators (STEMCELL Technologies, Miltenyi Biotec, FUJIFILM Biosciences): Focused product lines, rapid protocol development, and close ties to research communities allow specialists to capture early-adopter customers and niche clinical programs. Recent initiatives — including new protocols for cell enrichment and educational partnerships around standards — demonstrate how these firms convert technical leadership into commercial momentum.
-
Enablers and format specialists (Sartorius AG, Corning Incorporated, PromoCell GmbH): These firms compete on xeno-free formulations, GMP-grade supplements, and culture systems optimized for specific workflows (e.g., 3D culture). Their role in the value chain is often as trusted co-developers to therapy manufacturers.
Strategic implications: Large platform providers are best partners for program portfolios requiring global regulatory reach and supply redundancy. Specialist providers are ideal for early-stage or highly differentiated programs where formulation performance and protocol sophistication are differentiators. An optimal supplier strategy in 2026 will often be hybrid: primary supply agreements with a platform vendor plus strategic technical partnerships with specialists.
Commercial and regulatory playbook for 2026
-
Prioritize cGMP-ready suppliers early in program development. Lock in traceability and quality terms as pre-conditions for clinical transfers.
-
Design experiments and production runs with chemically defined, xeno-free media to minimize downstream validation scope and reduce variability risk during tech transfer.
-
Invest selectively in automation where unit economics matter most — i.e., clinical-scale and industrial production lines. Use automation ROI thresholds from our report to prioritize capital allocations.
-
Embed reimbursement evidence into media validation strategies: require suppliers to provide validation packages and stability data aligned with payer expectations.
-
Use vendor scorecards and staged qualification (pilot → bridged lots → full qualification) to manage supply risk while preserving negotiation leverage.
-
Consider bolt-on acquisitions to secure niche formulation IP or to bring specialized manufacturing capabilities in-house when strategic dependence on a supplier threatens program timelines.
Scenarios, leading indicators, and KPIs to monitor into 2026
-
Leading indicators: rate of adoption of chemically defined media in IND submissions; number and scale of cGMP-compliant production facilities commissioned; automation adoption rate in media manufacturing; supplier consolidation activity.
-
KPIs to track monthly/quarterly: validated lot release lead time, supplier qualification cycle time, cost per liter at scale, supplier concentration metrics for your supply chain, and time-to-tech-transfer for clinical production.
-
Scenario planning: model three baselines — rapid clinical adoption (highest growth, favorable pricing), measured adoption with reimbursement delays (moderate growth), and supply-constrained outcomes (slower growth, premium pricing). Each implies different inventory, contract, and investment choices.
Closing perspective — how to use our analysis in 2026
For executives and investment committees, the takeaway is straightforward: the stem cell media market is evolving from a fragmented, research-focused ecosystem into a regulated, industrial supply market with predictable growth and rising technical barriers to entry. Success in 2026 will favor companies that align procurement, regulatory, and product strategies to the new industrialized reality — securing validated supplier partnerships, adopting defined formulations, and selectively investing in automation and scale.
PW Consulting’s full study provides the granular segmentation, vendor scorecards, scenario models, and operational benchmarks that underpin the high-level guidance summarized here. To access the detailed data tables, sensitivity runs, and supplier dossiers referenced in this preview, please visit the PW Consulting report page for the Stem Cell Media Market and download the full research package.
For detailed analysis of this topic, please visit the official page: Stem Cell Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


