



Garage Door Openers Market Poised for 6.15% CAGR Through 2032 — PW Consulting

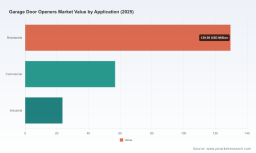
Garage Door Openers Market 2026: Strategic Imperatives from PW Consulting
As companies prepare strategy for 2026 and beyond, the Garage Door Openers market is transitioning from a mature mechanical product category into a digitally enabled, service-oriented ecosystem. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—provides the strategic blueprint executives need to convert disruption into competitive advantage. The market expanded from roughly USD 158 million in 2020 to an estimated USD 210 million in 2025, and our base forecast sees that trajectory continuing to roughly USD 319 million by 2032 at a compounded annual growth rate of about 6.15%. These macro dynamics are the springboard for four pragmatic decision levers covered in depth in our report: product-platform strategy, channel & commercial models, supply-chain resilience, and adjacent services monetization.
Garage Door Openers Market
Why this study matters for 2026 planning
For leadership teams allocating capital in 2026, three realities define the opportunity and the risk landscape:
Garage Door Openers Market
- Steady, above-inflation market growth. The mid-single-digit CAGR underpins predictable topline expansion but hides shifting margin pools as devices integrate sensors, cameras, and cloud services.
- Concentration and competitive intensity. The category exhibits moderate concentration — the top three and top five firms account for nearly half and three-fifths of the market respectively — creating both advantages for incumbents and entry points for nimble challengers.
- Structural shifts in productization. Hardware alone is no longer the primary value driver. Smart features, retrofitability, installation economics, and recurring service or subscription models are redefining customer lifetime value.
Understanding these forces at a granular yet actionable level is essential to prioritize R&D spend, shape go-to-market investments, and design M&A or partnership strategies that will produce measurable ROI in 2026.
Garage Door Openers Market
Key market dynamics shaping 2026 decisions
Several interlocking dynamics will determine winners and losers in the coming 18–36 months. Our report synthesizes quantitative forecasting with qualitative channel checks to identify which dynamics are transient and which are structural.
- Smart home convergence. Increasing household adoption of integrated home ecosystems is driving demand for openers that natively support video, voice, and secure cloud access. Recent product introductions from leading players signal a race to establish platform-level advantages (device + video + app + services).
- Retrofit and spatial innovation. A meaningful share of demand is now driven by retrofitable and space-optimized solutions—side-mount and compact-drive units are moving from niche to mainstream in constrained installations.
- Regulatory and safety continuity. Existing U.S. safety standards (e.g., the federal safety standard for residential automatic garage door operators) remain in force, setting a stable compliance baseline. Manufacturers can therefore focus R&D resources on feature differentiation rather than sudden compliance redesigns.
- Raw material and cost pressure. Input cost trajectories — exemplified by rising hot-rolled coil steel prices — are squeezing gross margins and prompting a closer look at material substitution, localized sourcing, and hedging strategies across the value chain.
- Channel economics and installation labor. The installer network remains a crucial differentiator. Speed of installation, compatibility with existing door systems, and installer-friendly digital tools will directly influence adoption curves and warranty costs.
Competitive landscape: what incumbents and challengers are doing
The competitive map is nuanced. Legacy manufacturers continue to leverage brand and distribution, while specialized innovators attack specific white spaces such as ultra-compact drives, high-duty industrial operators, and integrated video-enabled units. Our competitive benchmarking in the report profiles over a dozen firms, highlighting strategic posture, product roadmaps, and go-to-market footprints.
- Established global players (e.g., major U.S. and European manufacturers) are doubling down on platformization—integrating cameras, cloud services, and subscription models into premium lines while retaining traditional channels for volume products.
- Smaller, focused firms are commercializing modular and space-saving architectures that lower installation time and expand the addressable retrofit market.
- Recent product launches and trade show reveals through late 2025 and early 2026 underscore acceleration in smart and high-duty segments: several companies introduced next-gen video-enabled units, compact side-mount designs, and heavy-duty operator lines—moves that sharpen product differentiation and increase aftermarket service opportunities.
PW Consulting’s company dossiers objectively assess strategic positioning across the competitive set, including legacy advantages (brand, distribution), engineering differentiators (drive type, integration capability), and service potential (warranties, connected services). These dossiers also map ideal partnership and M&A targets for companies seeking to accelerate capability-building without building in-house from scratch.
What the full report contains (practical deliverables)
This study goes beyond high-level market narrative. It is structured to be immediately actionable for executive teams preparing 2026 plans:
- Quantified market size and forecast (2020–2032) with scenario analysis and sensitivity testing; clear implications for volume, revenue mix, and margin pools under alternative technology adoption curves.
- Go-to-market playbooks for OEMs, distributors, and installer networks—covering pricing strategies, bundling options (hardware + service), and channel-specific customer journeys.
- Technology and product roadmaps that prioritize features with the highest NPV uplift, including integration pathways for video, telematics, and over-the-air updates.
- Supply-chain and procurement playbooks addressing raw-material volatility, contract design, and inventory strategies to mitigate hot-rolled coil and component cost pressure.
- Competitive benchmarking and M&A screening: deep profiles of leading firms, capability heatmaps, and a short-list of tuck-in and scale-up targets by strategic intent.
- Installer economics and after-sales optimization: field data on installation times, warranty cost drivers, and service monetization levers.
- Regulatory and safety compliance matrix aligned to current standards—allowing product managers and compliance officers to prioritize design trade-offs without surprises.
To respect the "trailer" principle, we highlight that the report contains granular segmentation and regional breakouts, but those detailed splits are intentionally reserved for subscribers and purchasers of the full analysis.
Strategic actions for 2026 (executive checklist)
Based on our integrated analysis, here are prioritized, time-bound actions for leadership teams entering 2026 planning cycles:
- Define a platform thesis by Q2 2026. Determine whether to compete on integrated video/cloud platforms, retrofit-first compact hardware, or cost-leading fleet operators. Each thesis implies different capex, talent, and channel strategies.
- Accelerate installer enablement. Invest in digital installation tools, pre-configured kits, and training partnerships to reduce field labor costs and improve first-time-fix rates—key levers that boost installer preference and lower warranty exposure.
- Hedge material exposure. Implement a two-pronged procurement approach: negotiate multi-year agreements for critical steel inputs while qualifying alternative suppliers and material formulations to retain design flexibility.
- Pilot subscription services in 2026. Test video-storage, premium diagnostics, and extended-warranty bundles in selected markets to validate ARPU uplift and identify the right revenue share with dealer networks.
- Prioritize cybersecurity and data governance. As openers become connected endpoints, adopt secure-by-design principles and clear user-consent models—these will be non-negotiable for channel partners and large-scale customers.
- Use M&A selectively to buy time and capability. Target assets that accelerate time-to-market for digital features or provide strategic access to high-value installation channels.
Implications by stakeholder
Executives should interpret the market through their organization’s core mandate:
- For product teams: emphasize modularity—design common control platforms that can serve consumer, commercial, and industrial variants with minimal rework.
- For commercial leaders: reconfigure incentives for distributors and installers to prioritize high-margin, service-attach solutions rather than one-off hardware sales.
- For finance and corporate development: use the 6.15% CAGR and scenario outputs to stress-test valuations and prioritize investments with shorter payback windows.
- For supply-chain managers: treat raw-material price forecasts as a core input into contractual and inventory strategy; consider onshore sourcing or vertical integration options where defensible.
Final note: where this report adds unique value
PW Consulting’s Garage Door Openers study blends market forecasting, competitor intelligence, and operational playbooks into a single deliverable designed for immediate use in boardrooms and strategy offsites. The research balances the quantitative rigor executives require—highlighted by our detailed top-line trajectory and concentration metrics—with practical, field-tested recommendations for product and channel execution.
We intentionally withhold the full segmented tables and the most granular regional and application-level data in this overview to preserve the investigative depth available in the full report. If your team is evaluating product roadmaps, channel strategies, or acquisition targets for 2026, this study is structured to convert market insight into executable plans.
Contact PW Consulting to access the comprehensive dataset, scenario models, and company dossiers that will allow your team to operationalize these insights and set a winning course through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Garage Door Openers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


